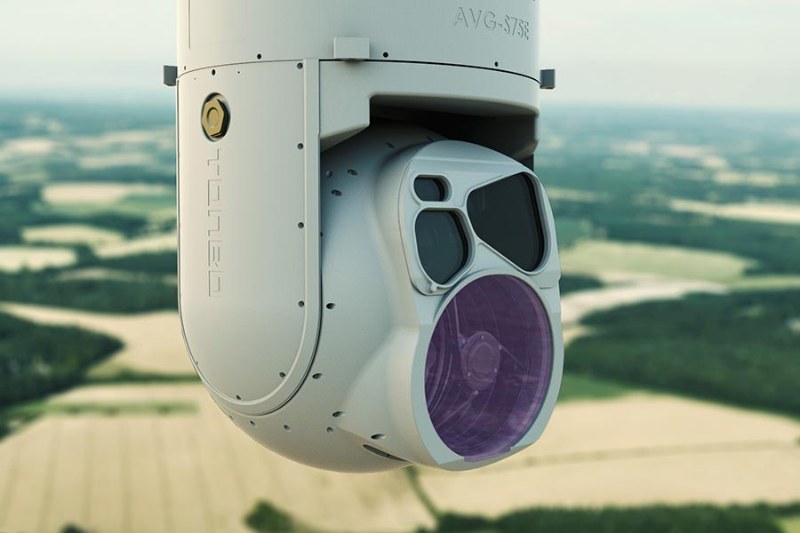
| COMPANY | Tonbo Imaging India Limited · thermal imaging cores, weapon sights, binoculars, targeting systems, missile seekers · promoters Arvind Kondangi Lakshmikumar, Ankit Kumar and Cecilia D'Souza |
|---|
| ISSUE | 100% offer for sale (no fresh issue; the company receives no proceeds) · about ₹852 Cr · price band ₹665–700 · face value ₹2 |
| VALUATION | ~₹4,010 Cr at the upper band (about US$480m) |
| ANCHORS | ₹255.4 Cr from 43 anchors at ₹700 (36.5 lakh shares), including 12 domestic mutual funds (57.7%), Goldman Sachs, BlackRock, WhiteOak and Allianz |
| FINANCIALS | Revenue FY24 ₹428.19 Cr · FY25 ₹469.08 Cr · FY26 ₹362.65 Cr (–22.7%) · PAT ₹68.54 Cr / ₹72.76 Cr / ₹50.88 Cr · Q1 FY27 loss ₹17.7 Cr on ₹36 Cr revenue |
| POSITION | 94.3% of India's thermal-imaging exports by units, FY24–FY26 · over 28,000 systems in 24 countries (Mar 2026) |
| INVESTORS SELLING | CEAQ Technologies, Artiman Partners and others; Qualcomm Ventures, Celesta, Edelweiss Value, HBL, Exim Bank and Florintree are investors |
| THE ACCESS POINT
Bidding ran from 15 to 19 October 2026 and shares list on BSE and NSE; the listing date and result were not in the sources read. This note analyses published information and is not a recommendation to subscribe. |
|---|
Executive decision summary
| THE BOTTOM LINE | Tonbo Imaging, an Indian defence-electronics maker, took its IPO to market in October 2026 as a pure offer for sale of about ₹852 crore at a price band of ₹665–700, valuing it at about ₹4,010 crore. Anchors put in ₹255.4 crore, with 12 domestic mutual funds taking 57.7% of the anchor book. The company sells thermal imagers, weapon sights and targeting systems to the Indian armed forces, NATO members, US Navy SEALs and Israeli defence forces, and says it holds 94.3% of India's thermal-imaging exports by units. The financials weakened, though: revenue fell 22.7% to ₹362.65 crore in FY26 and profit fell 30% to ₹50.88 crore, and the June 2026 quarter produced a ₹17.7 crore loss. At ₹700 the price is about 79 times FY26 earnings and 11 times revenue. |
|---|
| WHICH INVESTOR | Tonbo fits a watch-list IF you track Indian defence-electronics exporters and accept lumpy order timing.
Wait IF you need revenue growth: sales fell in FY26 and the first quarter of FY27 was loss-making. |
| COMFORT FIT | Tonbo = night-vision eyes for armies. Thermal cameras and sights that let soldiers and missiles see in the dark.
A 100% OFS = owners selling, company not raising. None of the ₹852 crore goes to Tonbo itself.
Lumpy orders = a builder paid on milestones. Revenue swings with when a defence contract is delivered.
Skyroot (Report 04) = an Indian deep-tech firm funded privately. Tonbo is the one taking public money. |
| THE RUPEIA NUMBER | ₹362.65 crore. FY26 revenue, 22.7% below FY25 (₹469.08 crore), against an IPO price that values the company at about 11 times that revenue (Rupeia calculation). |
1 CLAIM REGISTER: EVIDENCE GRADING
A = regulator or exchange filing. B = company filing summarised by press. C = independent press. D = third-party summary.
| Claim | Source | Grade | Rupeia assessment |
|---|
| 100% OFS; no proceeds to the company | Kotak Neo; Free Press Journal | C | Established |
| Price band ₹665–700; issue ₹852 Cr; valuation ~₹4,010 Cr | Inc42 (15 Oct 2026) | C | Established |
| Anchor ₹255.4 Cr from 43 investors at ₹700 | Inc42 (15 Oct 2026) | C | Established |
| Revenue ₹428.19 / 469.08 / 362.65 Cr (FY24–26); PAT ₹68.54 / 72.76 / 50.88 Cr | Groww table from the DRHP | C | Established |
| 94.3% of India's thermal-imaging exports by units | Kotak Neo (DRHP) | B | Company-stated |
| Over 28,000 systems in 24 countries | Groww (DRHP) | B | Company-stated |
2 THE ISSUE: OFS ONLY, AND HOW IT MOVED
| Item | Detail |
|---|
| DRHP size | 18,085,246 shares of ₹2 face value (about 1.81 crore), entirely OFS |
| At launch (Oct 2026) | About ₹852 Cr, roughly 1.22 crore shares at ₹700 |
| Price band | ₹665–700 |
| Valuation at ₹700 | ~₹4,009.8 Cr (about US$480m) |
| Bidding | 15–19 Oct 2026; listing on BSE and NSE |
| Lead managers | JM Financial, IIFL Capital Services; registrar KFin Technologies |
| DRHP history | Filed Dec 2025; a fresh DRHP reported 4 Aug 2026; SEBI approval reported between July and 28 Sep 2026 (sources differ) |
| Seller (DRHP) | Shares offered |
|---|
| CEAQ Technologies (Pvt Ltd and Pte Ltd) | Up to 1.5 crore |
| Promoters and Vinimaya Advisory | ~23 lakh combined |
| Timothy Guy Mitchell | 2.09 lakh |
| Artiman Partners | 1.97 lakh |
| Amit Dilip Shah; Ramesh Radhakrishnan | 84,600; 80,000 |
| RUPEIA READ
The issue shrank from about 1.81 crore shares in the DRHP to about 1.22 crore at the price band, a cut of roughly a third, and the sources read do not explain the difference. The anchor book of ₹255.4 crore covers 30% of the ₹852 crore issue (Rupeia calculation). |
|---|
3 FINANCIALS: THREE YEARS
| ₹ crore | FY24 | FY25 | FY26 |
|---|
| Revenue | 428.19 | 469.08 | 362.65 |
| EBITDA | 112.32 | 139.06 | 104.62 |
| Profit after tax | 68.54 | 72.76 | 50.88 |
| EBITDA margin (Rupeia) | 26.2% | 29.6% | 28.8% |
| PAT margin (Rupeia) | 16.0% | 15.5% | 14.0% |
| Revenue change | | +9.6% | –22.7% |
| RUPEIA CALCULATION
At ₹4,010 crore the valuation is about 79 times FY26 profit and about 11 times FY26 revenue, against FY25 multiples of about 55 and 8.5. Margins held near 29%, so the fall in profit came from lower sales. Q1 FY27 revenue was about ₹36 crore with a ₹17.7 crore loss, which leaves FY27 depending on the order book. The order book was ₹266.57 crore at 30 September 2025, with ₹71.68 crore more received in the next two months. |
|---|
4 ANCHOR AND ISSUE MATHS
| Measure (Rupeia calculation) | Value |
|---|
| Anchor ₹255.4 Cr ÷ issue ₹852 Cr | 30.0% |
| Anchor shares: 36.5 lakh × ₹700 | ₹255.5 Cr (matches) |
| Mutual funds' share of the anchor book (57.7%) | ~₹147 Cr |
| Issue ÷ valuation at ₹700 | ₹852 Cr ÷ ₹4,010 Cr = 21.2% of the company |
| Shares at ₹700 | ~1.22 crore (DRHP 1.81 crore) |
| RUPEIA READ
A fifth of the company is changing hands, and the sellers are shareholders, so Tonbo receives no cash. Domestic mutual funds, which put about ₹147 crore into the anchor book, are the largest named buyer group. |
|---|
5 REVENUE DIP AND THE ORDER BOOK
| Measure (Rupeia calculation) | Value |
|---|
| FY26 revenue vs FY24 | ₹362.65 Cr vs ₹428.19 Cr = –15.3% |
| FY26 PAT vs FY24 | ₹50.88 Cr vs ₹68.54 Cr = –25.8% |
| Order book at 30 Sep 2025 plus orders to 30 Nov 2025 | ₹266.57 Cr + ₹71.68 Cr = ₹338.25 Cr |
| That order book ÷ FY26 revenue | 0.93x |
| Exports of India's thermal imagers by units (FY24–FY26) | 94.3% share (company) |
| RUPEIA CALCULATION
The order book then reported covered about 11 months of FY26-level revenue, so a recovery in FY27 would require large new awards. Margins stayed near 29%, which says pricing held while volumes and timing fell. |
|---|
6 SUBSCRIPTION AND LISTING OUTCOME
| Fact | Published detail |
|---|
| Issue | ₹852.18 Cr offer for sale of 1.22 crore shares; price band ₹665–700; lot of 21 shares; fixed at ₹700. DRHP-stage reports (Kotak Neo, FPJ) cited up to 1.81 crore shares, so the final offer was smaller |
| Bidding | 15–19 Oct 2026 |
| Anchor book | ₹255.36 Cr raised on 14 Oct 2026 |
| Subscription | 132.81x on NSE and BSE data; 135.9x in other sources; QIB 293.56x, NII 170.94x, retail 31.07x (other sources differ slightly) |
| Listing (23 Oct) | NSE ₹1,160 (+65.71%); BSE ₹1,162; closed at ₹1,133.80 |
| Calculation (Rupeia) | Result |
|---|
| Cost of one lot at ₹700 | 21 × ₹700 = ₹14,700 |
| Listing gain per lot at ₹1,160 | 21 × ₹460 = ₹9,660 |
| Gain at the first-day close | 21 × ₹433.80 = ₹9,110; the close is 62% above the issue price |
| Anchor share of the issue | ₹255.36 Cr ÷ ₹852.18 Cr ≈ 30% |
| Value of the sold shares at the listing price | ₹852.18 Cr × 1,160 ÷ 700 ≈ ₹1,412 Cr |
| RUPEIA READ
Since the issue was an offer for sale, the whole ₹852 Cr went to the sellers and none to the company. The gap between the listing price and the close (about ₹26) was small for a 65% pop. A retail subscription of 31x against 294x from QIBs shows institutions, not individuals, drove the price. |
|---|
7 KEY TERMS USED IN THIS REPORT
The terms below are used throughout this report. The first table gives the general meaning; the second shows what each term refers to in this transaction.
| Term | Meaning |
|---|
| DRHP / UDRHP | Draft red herring prospectus, filed with SEBI before an IPO; an updated draft (UDRHP) replaces it after changes. |
| Fresh issue vs offer for sale (OFS) | A fresh issue creates new shares and the company gets the money. In an OFS existing holders sell and the company gets nothing. |
| Price band and anchor book | The range in which bids are accepted; anchors are large institutions allotted shares a day before the issue opens. |
| Pre-IPO placement | A private sale of shares shortly before the IPO that reduces the fresh issue by the same amount. |
| Lock-in | A period during which certain holders may not sell after listing; anchor shares are released in two steps. |
| Restated financials | Past accounts re-presented on a consistent basis for the prospectus. |
| Term in this report | What it refers to here |
|---|
| OFS only | Company receives no proceeds |
| Anchor book | ₹255.4 Cr from 43 investors |
| Face value | ₹2 |
| DRHP | Re-filed in 2026; sources differ on dates |
8 BUSINESS: PRODUCTS, CUSTOMERS AND RISKS
| Item | Detail (DRHP via press) |
|---|
| Products | Thermal imaging cores, weapon sights, thermal binoculars, targeting systems, missile seekers, fire-control and guidance systems |
| Customers | Indian armed forces, NATO members, US Navy SEALs, Israeli defence forces; Armenia's defence ministry |
| Exports | India about 92% of Q1 FY26 revenue; 94.3% of India's thermal-imaging exports by units, FY24–FY26 |
| Manufacturing partners | Kaynes Technology India; Avalon Technology |
| Installed base | Over 28,000 systems in 24 countries (31 Mar 2026) |
| Risk | Evidence | Severity | Kill condition |
|---|
| Falling revenue | FY26 –22.7%; Q1 FY27 loss ₹17.7 Cr | HIGH | No order recovery in FY27 |
| Lumpy defence orders | Order book ₹266.57 Cr (Sep 2025) | MEDIUM | Delays in deliveries |
| No proceeds to company | 100% OFS | MEDIUM | Sellers exit at the peak |
| Valuation | ~79x FY26 profit | MEDIUM | Trading below issue price |
| Manufacturing outsourcing | Partners Kaynes and Avalon | LOW | Supply disruption |
| Scenario | What happens | Outcome |
|---|
| Bull | Large Indian and export orders convert; revenue recovers above ₹470 Cr | Re-rating |
| Base | Revenue recovers slowly; margins hold near 28% | Trades near issue |
| Bear | Orders slip; losses continue | Below issue price |
Tonbo is a technologically credible defence exporter that listed at a rich valuation just after a down year. Rupeia's view is that the IPO is priced for recovery: the margins are strong, and the question for the next two results is whether the order book rebuilds. Listing-day performance was not in the sources read.
Frequently asked questions
How big is the Tonbo Imaging IPO?
About ₹852 crore, entirely an offer for sale, at a price band of ₹665–700 and a valuation of about ₹4,010 crore at the upper band.
When did the Tonbo IPO open?
Bidding ran from 15 to 19 October 2026; the anchor book was reported on 15 October.
Who invested as anchors?
43 anchors put in ₹255.4 crore at ₹700, including 12 domestic mutual funds (57.7%), Goldman Sachs, BlackRock, WhiteOak and Allianz.
Does Tonbo get any IPO money?
No. The issue is a 100% offer for sale by existing shareholders.
What are Tonbo's financials?
Revenue was ₹428.19 crore (FY24), ₹469.08 crore (FY25) and ₹362.65 crore (FY26); profit ₹68.54 crore, ₹72.76 crore and ₹50.88 crore.
What does Tonbo make?
Thermal imaging cores, weapon sights, binoculars, targeting systems and missile seekers, sold to armed forces in India, NATO members and others.
Who are Tonbo's promoters?
Arvind Kondangi Lakshmikumar, Ankit Kumar and Cecilia D'Souza.
Why did Tonbo's revenue fall in FY26?
The offer documents summarised in the press show revenue down 22.7%; Rupeia has not found a published explanation beyond order timing.
Source log
Inc42: IPO-bound Tonbo Imaging nets ₹255 Cr from anchor investors
Inc42: Tonbo Imaging files DRHP for OFS-only IPO
Kotak Neo: Tonbo Imaging gets SEBI nod for IPO; existing shareholders to sell up to 18.09 million shares
Groww: Tonbo Imaging India files DRHP with SEBI
Free Press Journal: Defence tech firm Tonbo Imaging files DRHP for IPO via full offer for sale
YourStory: Tonbo Imaging gets SEBI approval for IPO
Inc42: SEBI clears IPOs of Zetwerk, Tonbo Imaging
Chittorgarh: Tonbo Imaging India refiled draft prospectus with SEBI
| DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|