ITC and Sproutlife Foods (Yoga Bar): Last 52.5% bought for about ₹645
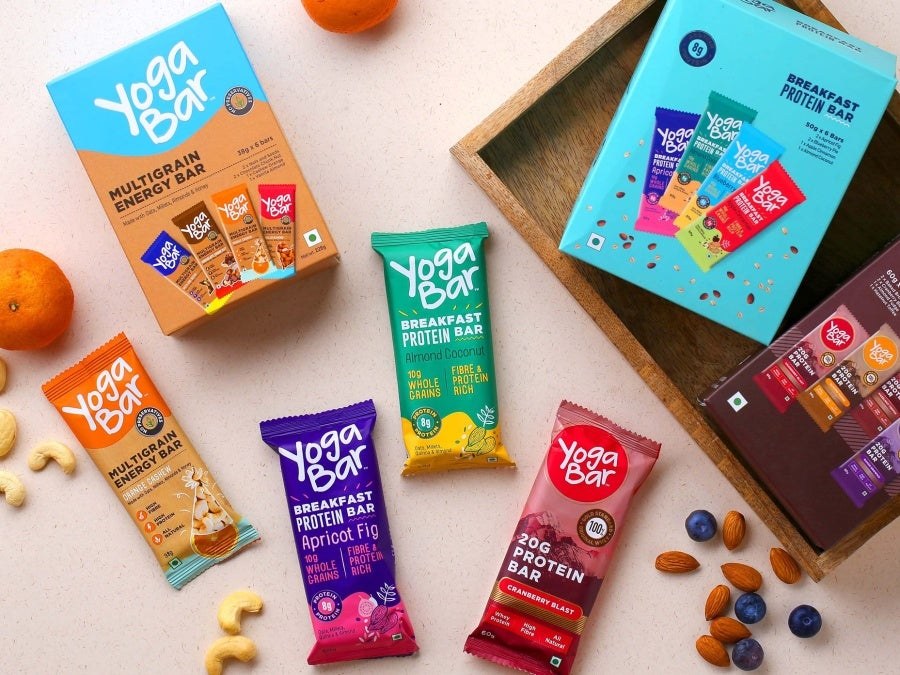
Yoga Bar range: multigrain energy bars and breakfast and protein bars · Image: Yoga Bar, via Just Food
Independent report content
| ACQUIRER | ITC Limited, listed FMCG, hotels, paperboards and agri group · FY26 FMCG revenue ₹24,210 Cr, Foods above ₹20,000 Cr (Outlook Business) |
|---|---|
| TARGET | Sproutlife Foods Private Limited, Bengaluru, incorporated 13 Feb 2015 · owns the Yoga Bar brand · founded by sisters Anindita and Suhasini Sampath |
| THIS TRANSACTION | 13,445 equity shares bought by secondary purchase for about ₹645 Cr cash · stake from about 47.5% to 100% · no regulatory approval needed (ITC) |
| EARLIER STEPS | ₹175 Cr for 39.4% (announced 18 Jan 2023) and ₹80 Cr more to 47.5% by 2025 · total outlay about ₹900 Cr |
| IMPLIED VALUE | About ₹1,229 Cr for 100% (645 / 52.5%) · about 2.7x FY26 turnover (Rupeia) |
| TURNOVER | FY24 ₹108 Cr · FY25 ₹200 Cr · FY26 ₹452 Cr (ITC disclosure) · FY26 loss ₹9.84 Cr vs FY25 loss ₹69.5 Cr (RoC and ITC annual report) |
| NEXT STEP | ITC board approved amalgamation into ITC on 2 Nov 2026, appointed date 1 Apr 2026, no new ITC shares (Multibagg) · ₹405.88 Cr Ind AS 103 gain booked in Q1 FY27 |
| THE ACCESS POINT Yoga Bar is no longer separately investable: ITC owns 100% of Sproutlife Foods, and a merger into ITC is proposed. Exposure now comes only through ITC's own listed shares, which are NSE and BSE traded (ITC was about ₹264 on 29 September 2026). |
|---|
Executive decision summary
| THE BOTTOM LINE | ITC has taken Yoga Bar from a 39% minority holding in 2023 to full ownership in 2026, paying about ₹900 crore in total, of which ₹645 crore was the final cheque to founders, early investors and employees for the last 52.5%. The price works out to about ₹1,229 crore for 100%, or 2.7 times FY26 turnover of ₹452 crore, a sharp fall from the 4–5 times that earlier tranches implied, because turnover more than doubled twice. The brand grew from ₹108 crore (FY24) to ₹200 crore (FY25) and ₹452 crore (FY26) and cut its loss from ₹69.5 crore to ₹9.84 crore in the last year. ITC booked a ₹405.88 crore accounting gain in Q1 FY27 for the earlier stake and now plans to merge Sproutlife into itself. The test is whether ITC's distribution can carry Yoga Bar to profit at its scale without losing the brand's direct-to-consumer edge. |
|---|---|
| WHICH INVESTOR | The deal fits you IF you want to understand how a large listed FMCG group buys a challenger brand in stages, at a multiple that fell as the brand grew, and you follow ITC's foods push. Wait IF you need audited Sproutlife FY26 accounts and the amalgamation scheme terms, which are not yet public, before judging profitability. |
| COMFORT FIT | A staged buy-out = buying a house on a payment plan. ITC paid for 39% first, 8% next, and the rest at a price fixed by formula once FY26 results were out. The multiple that fell = a price per rupee of sales that shrank because sales kept doubling while the price per share rose more slowly. The ₹405.88 crore gain = a revaluation, not cash. ITC marked up the stake it already owned to the price it paid for the rest. Report 10 (DailyObjects) and Report 05 (Curefoods) = other consumer brands valued at roughly 4–5 times revenue. Yoga Bar was bought at about 2.7 times. |
| THE RUPEIA NUMBER | 2.7x. ITC paid about 2.7 times FY26 turnover for the whole of Yoga Bar (₹1,229 crore implied value on ₹452 crore turnover), against about 4.4 times in the 2023 first tranche. |
1 CLAIM REGISTER: EVIDENCE GRADING
A = government, regulator, exchange or statutory filing. B = company or adviser release or website. C = independent press. D = third-party database, blog or aggregator.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| ITC acquired 13,445 shares, the remaining 52.5%, for about ₹645 Cr; wholly owned from 28 Sep 2026 | ITC exchange disclosure as reported by Angel One, PTI/ThePrint, Entrepreneur India, Inc42 | A | Established |
| No government or regulatory approval required; not a related-party transaction | ITC disclosure via Angel One and PSU Connect | A | Established |
| Turnover FY24 ₹108 Cr, FY25 ₹200 Cr, FY26 ₹452 Cr | ITC disclosure via PTI, Free Press Journal, Entrepreneur India | A | Established |
| ₹175 Cr for 39.4% and ₹80 Cr more to reach 47.5% | ITC 2023 announcement via IIFL, Inc42, StartupTalky | B | Established; date of first tranche differs (Jan or May 2023) |
| Pre-defined valuation criteria within three months of FY26 results | ITC 2023 announcement via IIFL, Business Today | B | Formula not published |
| FY25 revenue ₹201.66 Cr, net loss ₹69.5 Cr; FY24 ₹108 Cr and ₹60.5 Cr | RoC data via Startuppedia, D2C Insider | A | Established; secondary write-ups |
| FY26 net loss ₹9.84 Cr | ITC annual report as reported by Outlook Business and AskFuzz | B | Reported |
| ₹405.88 Cr gain on remeasuring the earlier stake, Q1 FY27 | ITC results via Multibagg and Quartr summaries | B | Reported |
| Board approved amalgamation on 2 Nov 2026; effective 1 Apr 2026; no new shares | Multibagg | C | Reported; scheme pending approvals |
| Implied 100% value about ₹1,229 Cr | INDmoney calculation; Rupeia calculation | D | Pro rata arithmetic only |
2 THE DEAL IN ONE PAGE
| Term | Detail | Source |
|---|---|---|
| Entity | Sproutlife Foods Private Limited, owner of the Yoga Bar brand; incorporated 13 February 2015, India | ITC disclosure via Angel One |
| Shares | 13,445 equity shares of ₹10 each, secondary purchase for cash | Angel One; Free Press Journal |
| Price | About ₹645 crore (Just Food: about ₹6.45bn, US$59.2m); price per share not stated | PSU Connect; Just Food |
| Per-share price (Rupeia) | ₹645 Cr / 13,445 = about ₹4.8 lakh per share | Rupeia calculation |
| Stake | About 47.5% to 100%; remaining 52.5% acquired | PTI; Entrepreneur India |
| Effective date | 28 September 2026 (8:05 pm confirmation) | Free Press Journal; PTI |
| Approvals | None required from government or regulators; not a related-party deal | Angel One; PSU Connect |
| Capital to the company | No fresh growth capital: seller consideration only | Entrepreneur India |
| Disclosure basis | Regulation 30, SEBI Listing Regulations | PSU Connect |
| Next step | Amalgamation into ITC approved by ITC board 2 Nov 2026; subject to approvals | Multibagg |
The ITC statement, as paraphrased by PTI, said the investment fits a "future-ready portfolio in the foods segment". Entrepreneur India notes that ITC has not disclosed specific plans for the brand. Hemant Malik, Divisional Chief Executive of ITC's Foods Division, said in 2023: "We look forward to scaling the Yoga Bar brand, offering superior and healthy consumer choices." The Sampath sisters said in 2023: "We are delighted to join hands with ITC in Yoga Bar's next phase of growth."
3 TIMELINE: 2014–2026
| Date | Milestone |
|---|---|
| 2014–15 | Founded in Bengaluru by Anindita and Suhasini Sampath; incorporated 13 Feb 2015; first multigrain energy bar launched Aug 2015 |
| 2015 | Fireside Ventures first outside investor (as reported) |
| 2020 | Elevation Capital joins in a later round (as reported) |
| FY22 | Revenue ₹68 Cr |
| 18 Jan 2023 | ITC announces plan to acquire 100% in tranches over three to four years; ₹175 Cr for 39.4%; run-rate about ₹100 Cr |
| 2023 | ₹175 Cr tranche completed (Feb 2023 per announcement; May 2023 per several reports) |
| Mar and Sep 2024 | Further ITC investments of ₹50 Cr and ₹30 Cr reported (INDmoney table: 44.74% then 47.50%) |
| FY25 | Revenue ₹201.66 Cr (+85%); net loss ₹69.5 Cr |
| Jan 2026 | Anuj Bansal of ITC Foods joins as Chief Business Officer |
| Q1 FY27 (Apr–Jun 2026) | ITC books ₹405.88 Cr Ind AS 103 gain on its earlier stake |
| 28 Sep 2026 | ITC buys remaining 52.5% for about ₹645 Cr; 100% owned |
| 2 Nov 2026 | ITC board approves amalgamation of Sproutlife into ITC |
4 COMPANY OVERVIEW: THE BRAND AND ITS FOUNDERS
Yoga Bar began as a multigrain energy bar sold in 2015 and grew into a nutrition brand with protein bars, muesli, oats and peanut butter, sold mostly online through its own website, e-commerce platforms and quick commerce, with a growing presence in offline stores. The founders are the sisters Anindita Sampath and Suhasini Sampath. Startuppedia describes their academic backgrounds as including LBS, Wharton, IIM Calcutta and BITS Pilani without saying which sister studied where. Sources differ on the founding year (2014 per Entrepreneur India and Inc42, 2015 per Just Food and others), but the company was incorporated on 13 February 2015.
| Item | Published detail | Source |
|---|---|---|
| Range | Protein bars, energy bars, muesli, oats, peanut butter | Indian Startup Times; Startuppedia |
| Channels | Mostly online; growing offline; quick commerce | Business Today; IIFL; Indian Startup Times |
| Employees | 63 (Inc42 data) | Inc42 |
| Leadership after ITC | Anuj Bansal, ITC Foods executive committee member, Chief Business Officer from January 2026 | Indian Startup Times; Startuppedia |
| Named peers | Pro Bar, U-Bars, Mojo Bars | Indian Startup Times |
5 THE 2023 STRUCTURE: A STAGED ROUTE TO 100%
ITC announced the first step on 18 January 2023. It said it would acquire 100% of Sproutlife in tranches over three to four years. The first tranche was up to ₹175 crore for 39.4% through a mix of share subscription and secondary purchase, to be completed by 15 February 2023 (IIFL). A second tranche of ₹80 crore by 31 March 2025 would bring ITC to 47.5%. The balance would be bought "based on predefined valuation criteria", within three months of Sproutlife releasing results for the fiscal year to March 2026 (IIFL). The valuation formula was not disclosed. INDmoney's table shows ITC at 44.74% (₹225 crore cumulative) in March 2024 and 47.50% (₹255 crore cumulative) in September 2024, which is consistent with the ₹175 crore plus ₹80 crore plan reached in two steps of ₹50 crore and ₹30 crore.
| Step | ITC stake after | Cash paid | Cumulative cash | Source |
|---|---|---|---|---|
| Tranche 1 (2023) | 39.4% | ₹175 Cr | ₹175 Cr | IIFL; Inc42 |
| Tranche 2a (Mar 2024) | 44.74% | ₹50 Cr | ₹225 Cr | INDmoney; D2C Insider |
| Tranche 2b (Sep 2024) | 47.50% | ₹30 Cr | ₹255 Cr | INDmoney; D2C Insider |
| Final tranche (28 Sep 2026) | 100% | ₹645 Cr | ₹900 Cr | ITC disclosure |
| RUPEIA READ Staged purchases let a large buyer see a start-up's numbers before committing. ITC paid about ₹255 crore for 47.5% while the brand was loss-making and then ₹645 crore for the rest after FY26 results were known. The structure moved the price risk to the sellers: because the final price followed a formula rather than a fixed number, strong FY26 numbers raised the price, but ITC had already locked in its first 47.5% at lower prices. |
|---|
6 THE PRICE LADDER: WHAT EACH TRANCHE IMPLIED
| Tranche | Calculation | Price per 1% (₹ Cr) | Implied 100% value (₹ Cr) |
|---|---|---|---|
| Tranche 1 | 175 / 39.4 | 4.44 | 444 |
| Tranche 2a | 50 / (44.74 − 39.40) | 9.36 | 936 |
| Tranche 2b | 30 / (47.50 − 44.74) | 10.87 | 1,087 |
| Final tranche | 645 / 52.5 | 12.29 | 1,229 |
| Tranche | Implied 100% value | Turnover reference | Multiple |
|---|---|---|---|
| Tranche 1 (2023) | ₹444 Cr | Run-rate about ₹100 Cr at announcement (Just Food) | About 4.4x |
| Tranche 2 (2024) | ₹936–1,087 Cr | FY24 turnover ₹108 Cr | About 8.7–10.1x |
| Final tranche (2026) | ₹1,229 Cr | FY26 turnover ₹452 Cr | About 2.7x |
| RUPEIA CALCULATION The price per 1% of the company rose 2.8 times from the first tranche to the last (12.29 / 4.44), while turnover rose about 4.5 times from the ₹100 crore run-rate to ₹452 crore. The 2024 tranches imply about 9–10 times turnover on FY24 sales, because ITC was paying for FY25 growth that had not yet appeared. Price per 1% in the final tranche is 31% above the late-2024 tranche (12.29 / 9.36 = 1.31 against 2a; 13% above 2b). A blended price for all 100% is ₹900 crore / 100 = ₹9.0 crore per 1%. |
|---|
7 WHO RECEIVED THE ₹645 CRORE
Inc42 shows the shareholding at 31 March 2025 as ITC 47.5% (largest), founders collectively about 24.7%, investors about 24.8% and an employee option pool of about 3.0%. A Startuppedia report of FY25 RoC filings gave a different split (Anindita Sampath 36.78%, Suhasini Sampath 30.73%, ITC 24.43%, Elevation Capital 8.06%), which does not match ITC's 47.5% and may reflect a stale filing. This note uses the Inc42 split. The 52.5% ITC bought must have come from those three groups.
| Seller group | Stake sold | Share of the 52.5% | Pro rata proceeds (₹ crore) |
|---|---|---|---|
| Founders (Sampath sisters) | About 24.7% | 47.0% | About 303 |
| Venture and other investors | About 24.8% | 47.2% | About 305 |
| Employee option holders | About 3.0% | 5.7% | About 37 |
| Total | 52.5% | 100% | 645 |
| RUPEIA CALCULATION These proceeds assume that every seller group received the same price per share, which the published disclosure does not state. On that assumption the founders took about ₹303 crore before tax and the investors about ₹305 crore. Venture rounds raised about US$11.6m (Signalbase) before ITC; ₹305 crore is about US$32m at ₹94.9 per US$, about 2.8 times that capital, before timing and earlier partial sales. The multiple is a rough guide and not an IRR. |
|---|
8 THREE CAP-TABLE VERSIONS AND WHY THEY DO NOT MATCH
Published shareholding data for Sproutlife cannot be reconciled from the sources read. Rupeia sets out the versions so that readers do not mix them.
| Source | Date | ITC | Founders | Investors | Other |
|---|---|---|---|---|---|
| Inc42 data | 31 Mar 2025 | 47.5% | About 24.7% combined | About 24.8% | ESOP pool 3.0% |
| Startuppedia (FY25 RoC) | FY25 | 24.43% | Anindita 36.78%; Suhasini 30.73% | Elevation 8.06% | Sums to 100% |
| INDmoney table (ITC steps) | Mar 2024 / Sep 2024 | 44.74% / 47.50% | n/s | n/s | n/s |
| ITC announcement | Jan 2023 | 39.4% planned | n/s | n/s | n/s |
| RUPEIA READ The Startuppedia split sums to 100% but shows ITC at 24.43%, which is below ITC's announced 39.4% from 2023, so it cannot describe the March 2025 position. It may be a pre-ITC list or a filing for a different date. The ITC announcements, the INDmoney steps and the Inc42 data are consistent with each other, so this note uses them. The proceeds table elsewhere in this report depends on the Inc42 split. |
|---|
9 FINANCIAL FORENSICS: FY22–FY26
| ₹ crore | FY22 | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|---|
| Turnover | 68 | 88 (INDmoney) | 108 | 200 (RoC: 201.66) | 452 |
| Growth | - | +29% | +23% | +85% | +126% |
| Materials consumed | n/s | n/s | 96 | 149 | n/s |
| Marketing | n/s | n/s | 25.88 | 49 | n/s |
| Employee benefits | n/s | n/s | 25.5 | 33.5 | n/s |
| Total expenses | n/s | n/s | 170 | 271 | n/s |
| Net loss | n/s | n/s | 60.5 | 69.5 | 9.84 |
| Operating cash flow | n/s | n/s | (52.86) | (71.81) | n/s |
| Ratio (Rupeia) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Net loss as % of turnover | 56.0% | 34.5% | 2.2% |
| Materials as % of turnover | 88.9% | 73.9% | n/s |
| Gross margin after materials | 11.1% | 26.1% | n/s |
| Marketing as % of turnover | 24.0% | 24.3% | n/s |
| Employee cost as % of turnover | 23.6% | 16.6% | n/s |
| Expense per ₹1 of revenue | ₹1.58 | ₹1.35 | n/s |
The FY24–FY25 lines come from RoC filings reported by Startuppedia and D2C Insider; FY26 turnover comes from ITC's disclosure; the FY26 loss of ₹9.84 crore comes from ITC's annual report as reported by Outlook Business and AskFuzz, which also said Ample Foods (Prasuma and Meatigo) lost ₹5.2 crore. Cash was ₹5 crore and total assets ₹87.5 crore at 31 March 2025, so the company depended on ITC's funding during FY25. Sproutlife's FY26 audited accounts have not been seen in any source read, and ITC did not disclose Sproutlife profit in its deal announcement (INDmoney).
| RUPEIA READ The turnaround is real in direction and steep in size: the loss fell from 56% of turnover in FY24 to 34.5% in FY25 and 2.2% in FY26 while turnover quadrupled. The FY25 drivers are visible in the accounts: gross margin after materials more than doubled from 11% to 26%, and employee cost fell from 24% to 17% of turnover. The FY26 break to near-profit is reported on ITC's numbers with no cost breakdown, and was achieved after ITC executives joined the management team, so scale, procurement and ITC's supply chain probably contributed. |
|---|
10 FY25 COST ANATOMY: WHERE EACH ₹100 OF SALES WENT
The FY25 RoC figures allow a line-by-line view of where revenue went. Rupeia expressed each reported cost as a share of FY25 revenue of ₹201.66 crore.
| FY25 line | ₹ crore | Per ₹100 of revenue (Rupeia) |
|---|---|---|
| Revenue from operations | 201.66 | 100.0 |
| Materials consumed | 149 | 73.9 |
| Marketing | 49 | 24.3 |
| Employee benefits | 33.5 | 16.6 |
| Freight outward | 20.65 | 10.2 |
| Depreciation | 2.5 | 1.2 |
| Finance cost | 0.25 | 0.1 |
| Other expenses (residual: 271 less the lines above) | 16.1 | 8.0 |
| Total expenses | 271 | 134.4 |
| Other income | 1.5 | 0.7 |
| Loss before tax and exceptional items (Rupeia: 201.66 + 1.5 − 271) | (67.8) | (33.6) |
| Reported net loss | (69.5) | (34.5) |
| RUPEIA READ Three lines make up 115 of every ₹134 of cost: materials (74), marketing (24) and employees (17). A typical packaged-food brand cannot reach profit with materials at 74% of sales and marketing at 24%; FY25 shows why. The ₹1.7 crore gap between the loss before tax computed from the published lines (₹67.8 crore) and the reported ₹69.5 crore may reflect tax, exceptional items or rounding, and the sources do not say which. For FY26 to reach a loss of only ₹9.84 crore on ₹452 crore, total costs had to be about ₹462 crore, or about ₹1.02 per ₹1 of revenue (452 + 9.84), against ₹1.35 in FY25. Total costs rose about 70% while revenue rose 126%. |
|---|
11 WHY ITC BOUGHT: THE FOODS PUSH
ITC's FY26 FMCG revenue was ₹24,210 crore (up 10.1%), with the foods business above ₹20,000 crore, and non-cigarette FMCG segment profit rose 14.1% to ₹1,802.63 crore (Outlook Business). Its annual report groups recent acquisitions together: Sresta Natural Bioproducts (24 Mantra Organic), Sproutlife Foods (Yoga Bar), Mother Sparsh Baby Care and Ample Foods (Prasuma and Meatigo). Together they grew about 60% and reached a combined annualised run-rate above ₹1,350 crore. In 2023 ITC described Yoga Bar as fitting its "Good for You" space alongside Aashirvaad Multi-Grain Atta and Sunfeast Protein Shake.
| Measure | Calculation | Result |
|---|---|---|
| Yoga Bar FY26 turnover share of ITC FMCG revenue | 452 / 24,210 | 1.9% |
| Same, share of Foods (above ₹20,000 Cr) | 452 / 20,000 | Under 2.3% |
| Yoga Bar share of the acquired-brands run-rate (₹1,350 Cr) | 452 / 1,350 | About 33% |
| ₹645 Cr as share of ITC's Q2 FY27 consolidated profit (₹4,229 Cr) | 645 / 4,229 | 15.3% |
| ITC total outlay of ₹900 Cr as share of Q2 FY27 profit | 900 / 4,229 | 21.3% |
| RUPEIA READ Yoga Bar is small for ITC (under 2% of FMCG revenue) but about a third of the acquired-brands group, and the whole ₹900 crore outlay is a bit over one-fifth of one quarter's profit. That makes the deal low in risk for ITC and large for the challenger-brand strategy. ITC's Q2 FY27 consolidated gross revenue was ₹30,431 crore (up 44.6%) and FMCG-Others revenue grew 19%, the fastest in 14 quarters, so the acquired brands sit inside a segment that is growing. |
|---|
12 ITC IN CONTEXT: THE PARENT'S OWN NUMBERS
Yoga Bar sits inside a group whose results moved sharply in the half-year of the purchase. For Q2 FY27 sources report consolidated gross revenue of ₹30,431 crore, up 44.6% (NiftyTrader, Investywise reports 46.6% growth led by non-cigarette businesses), against standalone profit after tax of ₹4,137 crore, down 20% (PSU Connect, Multibagg), and consolidated net profit of ₹4,229 crore against ₹5,187 crore a year earlier. ITC FMCG-Others revenue grew 19% in the quarter, the fastest in 14 quarters (Multibagg). In Q4 FY26 FMCG-Others revenue was ₹6,304–6,352 crore, up about 15%, with segment profit up about 51% to ₹521 crore (D2C Insider, Arihant Capital). The sources differ on the Q2 profit measure and on the Q4 revenue figure by a small margin; Rupeia shows both.
| ITC measure | Figure | Source |
|---|---|---|
| FY26 FMCG revenue | ₹24,210 Cr (+10.1%) | Outlook Business |
| FY26 non-cigarette FMCG segment profit | ₹1,802.63 Cr (+14.1%) | Outlook Business |
| Q4 FY26 FMCG-Others revenue | ₹6,304–6,352 Cr (+15%); segment profit about ₹521 Cr (+51%) | D2C Insider; Arihant Capital |
| Q2 FY27 consolidated gross revenue | ₹30,431 Cr (+44.6%) | NiftyTrader via search |
| Q2 FY27 consolidated net profit | ₹4,229 Cr vs ₹5,187 Cr | NiftyTrader via search |
| Q2 FY27 standalone PAT | ₹4,137 Cr (−20%); H1 ₹7,716 Cr | PSU Connect |
| Q2 FY27 FMCG-Others growth | +19% (14-quarter high) | Multibagg |
| RUPEIA CALCULATION Annualising the Q4 FY26 FMCG-Others revenue of about ₹6,350 crore gives about ₹25,400 crore a year, so Yoga Bar's ₹452 crore is about 1.8% of that run-rate (452 / 25,400). A deal that is 15% of one quarter's profit does not move ITC's numbers; it moves the proportion of the group that is growing in double digits. |
|---|
13 ACCOUNTING: THE ₹405.88 CRORE GAIN
ITC recorded a gain of ₹405.88 crore in the quarter ended 30 June 2026 (Q1 FY27) from remeasuring its earlier stake in Sproutlife at fair value under Ind AS 103, when it obtained control (Multibagg; Quartr summaries). Multibagg reports that ITC's Q2 FY27 exceptional expense was ₹25.66 crore, so the Sproutlife gain falls in the earlier quarter. INDmoney says Sproutlife became a subsidiary from 1 April 2026, which fits the Q1 timing. The September purchase itself carries no further remeasurement gain reported in the sources read.
| Item | Calculation | Result |
|---|---|---|
| Fair value of 47.5% at the final-tranche price | 47.5 × ₹12.29 Cr | About ₹583.6 Cr |
| Reported remeasurement gain | Reported | ₹405.88 Cr |
| Implied carrying value before remeasurement | 583.6 − 405.9 | About ₹177.7 Cr |
| ITC cash paid for the 47.5% | 175 + 50 + 30 | ₹255 Cr |
| Difference between cash paid and carrying value | 255 − 177.7 | About ₹77 Cr |
| RUPEIA READ If the earlier stake was fair-valued at the final-tranche price, its book value before remeasurement was about ₹178 crore, about ₹77 crore below the cash ITC paid. That gap is consistent with ITC having shown the stake under the equity method, in which its share of Sproutlife's losses reduces the carrying value. This is an inference from the published figures and not an ITC statement. The gain is non-cash and, as the 2023 structure implies, was triggered by the control date rather than by new money. |
|---|
14 THE AMALGAMATION PLAN
On 2 November 2026 ITC's board approved the amalgamation of Sproutlife Foods into ITC, subject to regulatory and other approvals. Multibagg reports the scheme is proposed to take effect from 1 April 2026 and that no new ITC shares will be issued because Sproutlife is already wholly owned. The ITC announcement does not, in the sources read, give the court or tribunal timetable. A wholly owned subsidiary amalgamation does not change ITC's ownership of the business; it brings Sproutlife's assets, liabilities, losses and contracts onto ITC's own balance sheet.
| Item | Published detail | Source |
|---|---|---|
| Board decision | 2 November 2026 | Multibagg |
| Appointed date | 1 April 2026 | Multibagg |
| Consideration | None: wholly owned; no ITC shares issued | Multibagg |
| Approvals | Regulatory and other approvals required; timetable not stated | Multibagg |
| Brand and operations | No specific plans disclosed | Entrepreneur India |
15 MARKET CONTEXT: PROTEIN BARS AND HEALTHY SNACKS
Market-size estimates for India's protein bars differ by about nine times. Food Research Lab put 2025 protein-bar sales at about US$130 million; Persistence Market Research projects about US$688 million for 2026; Coherent Market Insights and GII Research put 2026 at about US$1.22 billion. IMARC sizes the on-the-go healthy snacks market at about US$4.4 billion in 2025, and Expert Market Research puts all snack bars at about US$5.99 billion in 2025, growing 10.5% a year to 2035. Ken Research notes that Max Protein sells 10 g, 20 g and 30 g bars. No source read gives brand-level market shares.
| Source | Definition | Estimate |
|---|---|---|
| Food Research Lab | India protein bars, 2025 | About US$130m |
| Persistence Market Research | India protein bars, 2026 | About US$688m |
| Coherent Market Insights / GII Research | India protein bar, 2026 | About US$1.22bn |
| IMARC | On-the-go healthy snacks, 2025 | About US$4.4bn |
| Expert Market Research | Snack bars, 2025 | About US$5.99bn |
| RUPEIA CALCULATION Yoga Bar's FY26 turnover of ₹452 crore is about US$47.6m at ₹94.9 per US$. Against the range of protein-bar estimates that is 3.9% of US$1.22bn and 6.9% of US$688m, but Yoga Bar also sells muesli, oats and peanut butter, so the numbers are not like for like. The range shows how little the market size is agreed, not what Yoga Bar's share is. |
|---|
16 COMPETITIVE LANDSCAPE
| Competitor type | Named examples | Their edge | Yoga Bar's position |
|---|---|---|---|
| Protein-bar and nutrition specialists | Max Protein; Pro Bar; U-Bars; Mojo Bars | Focused ranges and fitness distribution | Broader breakfast and snack range |
| Large FMCG companies | ITC's own Sunfeast and Aashirvaad lines; others | National distribution | Now has the same distribution as its owner |
| Online-first D2C brands | Other health-food start-ups | Direct customer data | Early D2C base and quick-commerce presence |
The sources read describe the rivals in general terms only. The change from the 2023 position is that Yoga Bar now competes with the backing of a company whose foods business exceeds ₹20,000 crore.
17 WHAT HAS NOT BEEN DISCLOSED
| Item | Status in material read |
|---|---|
| Price per share and tranche split of the ₹645 Cr | Not stated; only the total and the 13,445-share count are published |
| Valuation formula in the 2023 agreement | Described as "predefined valuation criteria"; formula not published |
| Sproutlife audited FY26 accounts and EBITDA | Not seen; ITC has not disclosed Sproutlife profit in the announcement (INDmoney) |
| Roles of the Sampath sisters after the deal | Not stated in any source read |
| Plans for the Yoga Bar brand | Not disclosed (Entrepreneur India) |
| Tribunal timetable for the amalgamation | Not stated |
| Exact date of the first ₹175 Cr tranche | January/February 2023 per announcement; May 2023 per several reports |
| SKU count and distribution reach | Not stated |
Rupeia lists these items because they are the facts most often invented in summaries of this deal. None is estimated in this report.
18 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Red flag | Evidence | Severity | Kill condition | What would resolve it |
|---|---|---|---|---|
| Profitability not audited | FY26 loss ₹9.84 Cr from secondary reporting | MEDIUM | Audited FY26 shows a larger loss | Sproutlife or ITC audited accounts |
| Growth normalising | Turnover +126% in FY26 after +85% | MEDIUM | Growth falls below 30% | FY27 quarterly FMCG-Others growth |
| Brand integration | D2C identity inside a large distributor | MEDIUM | Brand loses its online base | Stable online share of sales |
| Competition in protein snacks | Many bars and large FMCG entrants | MEDIUM | Price wars cut margins | Gross margin holding above 25% |
| Input cost exposure | Materials were 74% of FY25 turnover | MEDIUM | Nut, oat or whey prices spike | Procurement scale from ITC |
| Undisclosed formula | Final-tranche valuation criteria not published | LOW | Disputes among sellers | Disclosure in ITC's annual report |
| Sources disagree on history | First tranche Jan or May 2023; shareholding splits differ | LOW | Misquotes in investor materials | ITC annual-report notes |
19 SENSITIVITY: WHAT FY27 TURNOVER DOES TO THE MULTIPLE AND THE LOSS
The price of ₹1,229 crore is fixed. What changes the multiple is turnover. The table recalculates it at four hypothetical FY27 turnover levels and shows the profit or loss at two hypothetical cost ratios. The FY26 cost ratio implied by ITC's numbers is about 1.02 per ₹1 of turnover (452 + 9.84 over 452). All FY27 figures are hypothetical and not forecasts.
| Hypothetical FY27 turnover (₹ crore) | Growth on FY26 | ₹1,229 Cr / turnover | Result at cost ratio 1.02 | Result at cost ratio 0.95 |
|---|---|---|---|---|
| 450 | 0% | 2.7x | (9.0) loss | 22.5 profit |
| 550 | +22% | 2.2x | (11.0) loss | 27.5 profit |
| 650 | +44% | 1.9x | (13.0) loss | 32.5 profit |
| 750 | +66% | 1.6x | (15.0) loss | 37.5 profit |
| RUPEIA READ Turnover growth alone does not produce profit; the cost ratio does. At the FY26 ratio of 1.02, higher turnover simply produces a larger loss. A seven-point improvement in the ratio, to 0.95, would give profits of ₹22–38 crore across the range. The FY25 cost anatomy shows the route: materials at 74% of sales and marketing at 24% are the lines where ITC's procurement scale and distribution must show up. Each point of margin on ₹452 crore is worth ₹4.5 crore. |
|---|
20 SCENARIO ANALYSIS: FY27 AND BEYOND
| Scenario | What happens | Implication |
|---|---|---|
| Bull | Turnover passes ₹700 Cr in FY27 with profit; ITC distribution adds offline reach | Yoga Bar becomes a core ITC foods brand; ₹900 Cr outlay looks cheap |
| Base | Turnover rises 40–60% to ₹630–720 Cr; near break-even | Brand sits as one of several ITC challenger brands |
| Bear | Growth stalls near ₹500 Cr as competition rises; losses return | Brand folded into a wider portfolio; write-down risk |
Scenarios are for discussion. They are not forecasts and use no unpublished data.
21 INVESTOR CLASS ANALYSIS
For HNIs
Yoga Bar is not separately investable. The only route is through ITC shares, where the brand is under 2% of FMCG revenue and a smaller share of group profit.
For family offices
The deal is a case study in how a staged acquisition lets a buyer pay a lower price for the early stake. A family office considering a minority in a challenger brand can ask whether a call option like ITC's is available.
For institutions
ITC investors will judge the deal through FMCG-Others margin and the FY27 profit contribution after merger.
For NRIs
NRIs can buy listed ITC shares through the portfolio investment scheme subject to RBI and FEMA limits.
22 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| Exposure to a scaled health-foods brand inside a large listed group | ITC | Yoga Bar and other brands under one distribution network | Brand is under 2% of FMCG revenue |
| A venture-stage consumer brand | DAILYOBJECTS (Report 10) | Private, capital-efficient | Unlisted; limited disclosure |
| A listed consumer-brand turnaround | CUREFOODS (Report 05) | Public disclosure | Cash-constrained |
23 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| Q3 FY27 results | First full quarter with Sproutlife wholly owned | Shows Yoga Bar contribution to FMCG-Others |
| 2026–27 | Tribunal process for the amalgamation | Completes the legal merger |
| FY27 annual report | Fair-value notes and Sproutlife standalone numbers | Audited view of FY26 and the final valuation basis |
| 2027 | Offline distribution expansion | Tests the ITC channel advantage |
24 HOW THIS DEAL COMPARES WITH OTHER ACQUISITIONS IN THE SERIES
| Measure | ITC–Yoga Bar (Report 44) | upGrad–Unacademy (Report 43) | Advent–Yatharth (Report 28) |
|---|---|---|---|
| Type | Staged buy-out to 100%, cash | 100% share swap and merger | Minority primary investment in a listed company |
| Value | ₹645 Cr for the last 52.5%; ₹900 Cr in total | About ₹1,955 Cr in upGrad stock | ₹3,150 Cr for 24.87% |
| Implied value to latest revenue | About 2.7x FY26 turnover | About 2.4x FY25 revenue (equity); 1.3x net of cash | About 6.3x LTM revenue (EV) |
| Target profitability | FY26 loss ₹9.84 Cr (near break-even) | FY25 net loss ₹436 Cr | FY26 PAT ₹170.3 Cr |
| Approvals | None required | CCI, 7 Jul 2026 | Shareholders and customary regulatory |
| Target growth | +126% in FY26 | −16% in FY25 | +36% in FY26 |
| RUPEIA READ The three deals show three kinds of buyer pricing. Advent paid a growth multiple for a profitable listed company. upGrad paid a distressed multiple for a shrinking, loss-making target. ITC paid a modest multiple for a fast-growing, almost break-even brand after watching it for three years. The lowest multiple belongs to the target whose sales were growing fastest, which is a result of the staged structure. |
|---|
25 RUPEIA FINAL INDEPENDENT VIEW
ITC's Yoga Bar purchase is a textbook case of a patient acquirer buying a challenger brand in steps and ending with the lowest multiple at the highest scale. The company paid about ₹255 crore for the first 47.5% in 2023–24 and ₹645 crore for the last 52.5% in 2026, about ₹900 crore in all. Over those three years Yoga Bar's turnover rose from roughly ₹100 crore to ₹452 crore and its loss fell from 56% of turnover to about 2%.
The numbers that are still missing are the ones that matter next: audited FY26 accounts, the valuation formula, and the terms and timetable of the merger scheme. The reported loss of ₹9.84 crore is the first sign that scale and ITC's supply chain can make the brand profitable.
| THE RUPEIA NUMBER 2.7x: ITC paid about 2.7 times FY26 turnover for 100% of Yoga Bar (₹1,229 crore on ₹452 crore). |
|---|
| RUPEIA VERDICT A well-structured, fairly priced strategic acquisition. The price is high against earnings, which are only just positive, and low against sales growth. The next evidence is audited profit and the merger terms. This note gives no buy, sell or subscribe view. |
|---|
Frequently asked questions
How much did ITC pay for the rest of Yoga Bar?
About ₹645 crore in cash for 13,445 equity shares representing the remaining 52.5% of Sproutlife Foods, effective 28 September 2026. ITC now owns 100%.
What was ITC's total investment in Yoga Bar?
About ₹900 crore: ₹175 crore for 39.4% (2023), ₹80 crore more to about 47.5% (2024), and ₹645 crore for the remaining 52.5% (2026).
What does the deal value Yoga Bar at?
About ₹1,229 crore for 100% on a simple pro rata calculation (645 / 52.5%), about 2.7 times FY26 turnover of ₹452 crore. The company did not state a valuation.
What is Yoga Bar's revenue?
Turnover was ₹108 crore in FY24, ₹200 crore in FY25 (RoC: ₹201.66 crore) and ₹452 crore in FY26, according to ITC's disclosure.
Is Yoga Bar profitable?
Not yet by the RoC record: the FY25 net loss was ₹69.5 crore. ITC's annual report, as reported by Outlook Business, shows a FY26 loss of ₹9.84 crore.
Who founded Yoga Bar?
Sisters Anindita Sampath and Suhasini Sampath, in Bengaluru. The company was incorporated on 13 February 2015.
Did the deal need regulatory approval?
ITC said no government or regulatory approval was required, and that it was not a related-party transaction.
What is the ₹405.88 crore gain?
A non-cash gain ITC booked in Q1 FY27 from remeasuring its earlier stake at fair value under Ind AS 103, when it took control of Sproutlife.
What happens to Yoga Bar now?
ITC's board approved merging Sproutlife into ITC on 2 November 2026, effective 1 April 2026 and with no new ITC shares, subject to approvals. ITC has not disclosed plans for the brand.
Source log
Entrepreneur India: ITC buys remaining Yoga Bar stake for INR 645 Cr
Free Press Journal: ITC completes Sproutlife Foods acquisition for ₹645 crore
ThePrint (PTI): ITC completes 100% acquisition in Sproutlife Foods
Angel One: ITC acquires remaining 52.5% in Yoga Bar maker Sproutlife
Inc42: ITC completes Yoga Bar acquisition for ₹645 Cr
Just Food: ITC buys Yoga Bar owner Sproutlife outright
PSU Connect: ITC completes full takeover of Yoga Bar maker Sproutlife
MediaNews4U: ITC takes full ownership of Yoga Bar
INDmoney: ITC Yoga Bar acquisition valuation analysis
StartupTalky: ITC acquires Yoga Bar maker Sproutlife Foods
Indian Television: ITC completes ₹645 crore acquisition of Yoga Bar parent
Multibagg: ITC approves Sproutlife merger after taking full control
Multibagg: ITC Q2 profit and revenue, Sproutlife
Multibagg: ITC FMCG-Others revenue growth hits 14-quarter high
PSU Connect: ITC Q2 results, standalone PAT ₹4,137 Cr
Investywise: ITC Q2 FY27 results media statement
Outlook Business: ITC FMCG revenue ₹24,210 Cr in FY26, Foods crosses ₹20,000 Cr
AskFuzz: ITC FMCG consumer spending hits ₹37,000 crore in FY26
IIFL: ITC announces acquisition of Yoga Bar (January 2023)
Business Today: ITC to acquire FMCG start-up Yoga Bar in the next 3-4 years
Just Food: India's ITC boosts healthy food portfolio with Yoga Bar buy
AFAQS: ITC to enter healthy foods space with the acquisition of Yoga Bar
Inc42: Yoga Bar cap table
Signalbase: Sproutlife Foods (Yoga Bar) closes US$11.6M Series A
Startuppedia: Yoga Bar crosses ₹200 Cr revenue in FY25; loss widens to ₹69.5 Cr
Indian Startup Times: Yoga Bar deep dive
D2C Insider Pulse: Yoga Bar FY25 financials
Persistence Market Research: India protein bars market
IMARC: India on-the-go healthy snacks market
Expert Market Research: India snack bars market
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|