Siguler Guff GEMGO II: US$500 million platform close
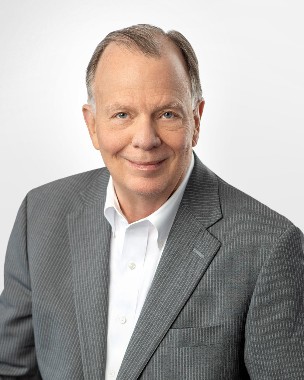
George W. Siguler, Executive Chairman and co-founder, Siguler Guff · Image: Siguler Guff website, Team page
Independent report content
| MANAGER | Siguler Guff & Company, New York · founded 1991 within PaineWebber, independent since 1995 · about US$18.4bn AUM at 31 Dec 2025 (Outlook Business/PTI) |
|---|---|
| FUND | Global Emerging Markets Growth Opportunities Fund II (GEMGO II) · final close announced 19 Aug 2026 |
| SIZE | US$500m of capital commitments across the fund, related co-investment vehicles and separately managed accounts · Form D (3 Sep 2026): US$185.4m sold by the main entity, 35 investors |
| STRATEGY | High-growth founder- and family-owned Indian companies · average investment about US$50m · consumer, healthcare, financial services, technology |
| INDIA RECORD | About US$1bn invested in India across emerging-markets vehicles, 23 companies, including IEX, GlobalLogic, City Union Bank, Luker, Baazar Kolkata, Sterling Hospitals |
| FIRST DEALS | Trimex Foods (US$40m, Apr 2026), Rajasthan Royals, Valliance.ai, La Renon (Outlook Business/PTI) |
| TERMS | Fees, carry, hurdle, fund life, DPI and IRR: not disclosed |
| THE ACCESS POINT GEMGO II has reached its final close and is closed to new investors. It is an offshore US fund structure reported on SEC Form D; no Indian AIF feeder has been published. The Form D lists 35 investors and a sold amount of US$185.4 million for the main entity. Siguler Guff’s adviser filing notes a US$5 million minimum for its advisory clients. Individuals in India can reach the strategy only through the manager’s distribution to eligible investors. |
|---|
Executive decision summary
| THE BOTTOM LINE | Siguler Guff is a 35-year-old New York private-markets firm with about US$18 billion of assets, a long record in emerging markets and a meaningful India book (about US$1 billion in 23 companies). On 19 August 2026 it announced the final close of its second India-focused growth fund, GEMGO II, at US$500 million. The headline combines three things: the fund itself, co-investment vehicles and separately managed accounts. The SEC Form D for the main entity shows US$185.4 million sold to 35 investors, so about 37% of the headline sits in the fund vehicle on that filing and the rest is in related vehicles that are not itemised. The manager has not published fees, returns or the split. What it has published is a clear strategy (about US$50 million cheques into founder-led mid-market businesses), a named India team and early deals including Trimex Foods and Rajasthan Royals. |
|---|---|
| WHICH INVESTOR | GEMGO II fits you IF you are an institution or a family office that already has access to Siguler Guff, you want India mid-market growth exposure through a US-regulated offshore manager, and you accept that terms and returns are private. Wait IF you need fund-level net returns, fee terms or the split between fund, co-investment and managed accounts. None of these is published. |
| COMFORT FIT | GEMGO II = a mid-sized ship with escort vessels. The US$500 million is the whole convoy; the Form D describes only the lead ship. Siguler Guff in India = a lender-turned-investor with 20-plus years of relationships. It backs founder-led businesses rather than building platforms from scratch. ChrysCapital Fund X (US$2.2bn, Nov 2025) = the domestic heavyweight. Four times the size, with first-time domestic LP capital. The fund’s US$50 million ticket = the middle of the road: bigger than venture, smaller than large buyouts, aimed at companies with ₹500–5,000 crore of enterprise value. |
| THE RUPEIA NUMBER | 37%. Form D says US$185.4m was sold by the main fund entity to 35 investors as of 3 September 2026. That is 37% of the US$500m headline (185.365 ÷ 500). The other 63% (about US$314.6m) is the combined capacity of related vehicles. The manager has not split it. |
1 CLAIM REGISTER: EVIDENCE GRADING
A = government, regulator or statutory filing (including SEC Form D data as reported by aggregators). B = company or manager release, website or filing. C = independent press. D = third-party database, blog or aggregator.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| GEMGO II final close announced 19 Aug 2026; US$500m across fund, co-invest vehicles and SMAs | Siguler Guff release via Outlook Business/PTI; Venture Intelligence, 20 Aug 2026 | B | Established |
| Form D: US$185.365m sold; 35 investors (amendment 3 Sep 2026) | SEC Form D data via FormDs and PipelineRoad | A | Established; covers the "Fund II (A), LP" entity only |
| Interim: over US$110m of a US$300m target (Jul 2024) | Venture Intelligence citing Business Line | C | Established |
| About US$1bn invested in India; 23 companies | Siguler Guff release via Outlook Business/PTI | B | Manager-reported |
| Spandana Sphoorty: ₹240 Cr for about 3.5% (May 2024) | ANI via ThePrint; Hans India | B | Established; price and share count not stated |
| Trimex Foods: US$40m (29 Apr 2026) | Hospemag; Whalesbook | C | Established; stake not stated |
| Predecessor India deployment of US$238m | Secondary summaries only; not in release text read | D | Not used as fact |
| Fees, carry, DPI, IRR, LP names | None published | — | Not disclosed |
2 FUND SNAPSHOT: GEMGO II AGAINST THREE REFERENCE FUNDS
| Fund | Size | Year | Scope | Published status |
|---|---|---|---|---|
| Siguler Guff GEMGO II | US$500m incl. co-invest and SMAs; Form D US$185.4m | Aug 2026 | India growth equity; ~US$50m average ticket | Final close; deploying |
| Siguler Guff Global Emerging Markets Direct Investment Fund | US$240m final close | May 2021 | China, India, Southeast Asia; expansion-stage companies | Predecessor direct fund (GPCA) |
| Siguler Guff BRIC Opportunities Fund III | About US$650m | Mar 2014 | Brazil, Russia, India, China; fund investments and co-investments | Multi-manager (PE Professional, PEI) |
| ChrysCapital Fund X | US$2.2bn | Nov 2025 | India growth and buyouts; US$75–200m deals | Largest India-focused PE raise reported; first domestic LPs |
| RUPEIA READ GEMGO II is the first Siguler Guff fund dedicated to a single country’s mid-market. Its predecessors were either multi-country direct funds (US$240m, 2021) or fund-of-funds (US$650m, 2014). The strategy has moved from picking managers to picking companies, with a US$50 million ticket that puts it between venture growth funds and the US$75–200 million deals of the largest Indian PE funds. |
|---|
3 TIMELINE: 1991–2026
| Date | Event |
|---|---|
| 1991 | Siguler Guff founded within PaineWebber by George Siguler, Drew Guff and Donald Spencer |
| 1995 | Becomes independent; emerging-markets platform established |
| 2006 | First BRIC fund-of-funds closes at about US$600m (Private Equity Analyst, hosted by Siguler Guff) |
| Mar 2014 | BRIC Opportunities Fund III closes at about US$650m |
| 2015 | Small business credit strategy established (firm website) |
| May 2021 | Global Emerging Markets Direct Investment Fund closes at US$240m |
| Aug 2023 | GEMGO II Form D filed: US$83.1m sold to 12 investors |
| May 2024 | Invests ₹240 Cr in Spandana Sphoorty for about 3.5% |
| Jul 2024 | GEMGO II raised over US$110m against a US$300m target |
| Apr 2026 | US$40m in Trimex Foods |
| 19 Aug 2026 | GEMGO II final close at US$500m |
| 3 Sep 2026 | Form D amendment: US$185.4m sold, 35 investors |
| 17 Sep 2026 | Firm announces a record US$3bn raise for its small-buyout strategy |
4 THE MANAGER: SIGULER GUFF & COMPANY
Siguler Guff describes itself on its website as founded by George Siguler, Drew Guff and Donald Spencer as the private-equity group of PaineWebber in 1991 and independent since 1995. It is headquartered in New York with offices that include Boston, West Palm Beach, London, Mumbai, São Paulo, Shanghai, Tokyo, Seoul, Houston and Hong Kong. Its strategies, per the website navigation, are small-business buyout, small-business credit, emerging markets, credit and special situations, real estate and energy, delivered through multi-manager funds, direct funds and separate accounts. The site says it serves more than 800 institutional clients and more than 1,000 family offices and high-net-worth investors.
| Date | Assets under management (as published) | Source |
|---|---|---|
| Apr 2014 | Over US$10bn | PE Professional |
| Jun 2021 | Over US$15bn | Siguler Guff release |
| May 2024 | Over US$16bn | ANI via ThePrint |
| Oct 2024 | Over US$16bn | Siguler Guff release |
| 31 Dec 2025 | About US$18.4bn | Outlook Business/PTI, 19 Aug 2026 |
| Apr 2026 | Over US$18bn | Hospemag |
| Undated website | "Approximately US$19bn"; emerging-markets platform US$5bn | sigulerguff.com |
| RUPEIA READ AUM has grown from US$10 billion to about US$18–19 billion in twelve years, with the latest growth in US small-business credit and buyout (US$3 billion for the small-buyout strategy in September 2026). India is a small part of a large platform, which brings resources and a brand, and also competition for the firm’s attention and for allocation of its best ideas. |
|---|
5 THE FRANCHISE BEHIND THE BRAND: CREDIT, BUYOUT AND REAL ESTATE
GEMGO II sits inside a firm whose recent fundraising has been dominated by US small-business strategies. The firm’s own releases give the sequence:
| Strategy | Date | Amount raised (as published) | Detail |
|---|---|---|---|
| Small business lending platform | 13 Oct 2017 | US$300m | Seed of the small-business credit strategy; firm page says "established in 2015" |
| Small Business Credit Opportunity Fund II | 24 Jun 2021 | Over US$450m, with related accounts | Firm had invested over US$400m since the 2015 launch; "nearly 90%" of institutional investors in the first vehicle continued into Fund II |
| Small Business Credit Opportunities Fund III | 10 Oct 2024 | Over US$580m against a US$500m target; over US$900m with US$355m of related accounts | "More than doubling" the 2021 fundraise; mezzanine, first-lien and equity co-investments in companies with US$2–15m of EBITDA |
| Small buyout strategy | 17 Sep 2026 | Record US$3bn | Headline on the firm’s news page; article body not read |
| GEMGO II | 19 Aug 2026 | US$500m incl. related vehicles | India mid-market growth |
| RUPEIA CALCULATION Fund III’s over US$580m against Fund II’s over US$450m is up about 29% (580 ÷ 450). With related accounts, the over-US$900m aggregate is about twice the US$450m of 2021 (900 ÷ 450), matching the firm’s "more than doubling". GEMGO II’s US$500m is 17% of the US$3bn small-buyout raise (500 ÷ 3,000). In the firm’s own credit funds, "nearly 90%" of first-fund institutions came back for Fund II: that is the only re-up statistic Siguler Guff has published, and it relates to credit, not India. |
|---|
The firm’s news page for 2026 also shows a steady stream of real-estate mezzanine loans: US$25 million for a Wynwood condominium development (12 May), US$10.25 million for the Pomeroy multifamily apartments (13 July) and US$16.2 million for the Park Square multifamily development (5 November). These headlines do not involve India. They show where the firm’s deal flow and announcements are concentrated.
6 WHAT THE US$500 MILLION IS MADE OF
Siguler Guff’s release says the fund closed "alongside related co-investment vehicles and various separately managed accounts" and that "together, these vehicles represent US$500 million of capital commitments" (Outlook Business/PTI, 19 August 2026). No split between the three pools is given. The SEC Form D for Siguler Guff Global Emerging Markets Growth Opportunities Fund II (A), LP records the main entity’s sales over time:
| Filing date | Type | Reported sold | Investors |
|---|---|---|---|
| 9 Aug 2023 | Initial | US$83.11m | 12 |
| 29 Jul 2024 | Amendment | US$105.66m | 17 |
| 30 Jul 2025 | Amendment | US$105.66m | 17 |
| 3 Sep 2026 | Amendment | US$185.365m | 35 |
FormDs shows the first sale on 4 August 2023 and promoters Siguler Guff Advisers, Siguler Guff & Company and Siguler Guff GEMGO II GP, with Kenneth Burns, Andrew Guff and George Siguler as executive officers. The July 2024 Form D amount (US$105.66 million) matches the "over US$110 million" interim figure that Business Line reported against the then US$300 million target (Venture Intelligence, 3 July 2024).
| RUPEIA CALCULATION US$185.365m ÷ US$500m = 37.1%. US$500m − US$185.365m = US$314.6m. The second figure is the most that could sit in co-investment vehicles, separately managed accounts and any other fund entities not covered by this Form D; the actual split is not published. The Form D average of US$185.365m ÷ 35 investors = US$5.3m per investor. Between July 2025 and September 2026 the main entity added US$79.7m and 18 investors (185.365 − 105.66; 35 − 17). The original target was US$300m, so the final US$500m is 1.67 times that target (500 ÷ 300). |
|---|
The Form D covers one legal entity. Siguler Guff’s adviser filing (Form ADV dated 25 March 2026, as summarised by FormDs) shows a much smaller gross asset value of US$70.5 million and 13 beneficial owners, and FormDs notes that the two filings measure different things. Neither is a substitute for a fund-level capital statement.
7 THE FORM D HISTORY: WHAT FUNDRAISING PACE TELLS YOU
| Interval | Change in amount sold | Change in investors | Reading |
|---|---|---|---|
| Aug 2023 to Jul 2024 (11 months) | +27% (83.11 to 105.66) | 12 to 17 (+5) | Initial close and early adds |
| Jul 2024 to Jul 2025 (12 months) | 0% (105.66 to 105.66) | No change | A year with no reported sales on the main entity |
| Jul 2025 to Sep 2026 (14 months) | +75% (105.66 to 185.365) | 17 to 35 (+18) | Final-close push |
| Aug 2023 to Sep 2026 (about 3.1 years) | +123% (83.11 to 185.365) | 12 to 35 (+23) | Overall |
| RUPEIA CALCULATION Ratios: 105.66 ÷ 83.11 = 1.27; 185.365 ÷ 105.66 = 1.75; 185.365 ÷ 83.11 = 2.23. The US$185.4m on the main entity is 62% of the original US$300m target (185.365 ÷ 300), while the US$500m headline is 167% of it. Form D amounts are cumulative sales as reported on filing dates, so a flat figure means no new sales were reported at those dates, not necessarily that none occurred in between. |
|---|
Read together, the Form D history and the headline say two different things. On the main entity the fund took three years to reach about three-fifths of its original target. On the platform, which includes co-investment and managed accounts, it ended above target. Which is the better description of investor appetite depends on whether the managed accounts and co-investment commitments are as discretionary as fund commitments. The manager has not said.
8 THE STRATEGY: INDIA MID-MARKET GROWTH
The release describes GEMGO II as investing in high-growth, founder- and family-owned businesses with average investment sizes of about US$50 million across consumer, healthcare, financial services and technology, aiming at both domestic consumption and global demand. Venture Intelligence’s 2024 report adds technology-enabled services and the India–US investment corridor. Drew Guff, Chief Investment Officer and co-portfolio manager, said "India is a highly compelling long-term global investment opportunity". Shaun Khubchandani, Partner and co-portfolio manager, said "India’s mid-market continues to offer an attractive opportunity to partner with founder-led and family-owned businesses".
| Parameter | Published | Source |
|---|---|---|
| Average investment | About US$50m | Outlook Business/PTI; Venture Intelligence |
| Targets | Founder- and family-owned, high-growth | Same |
| Sectors | Consumer, healthcare, financial services, technology | Same |
| Emerging-markets platform terms (firm page) | Direct target enterprise value US$50–500m; 65+ direct equity investments; 80+ fund managers | sigulerguff.com |
| Fund life, hurdle, fees, carry | Not disclosed | — |
| Co-investment | Parallel vehicles exist; terms not disclosed | Outlook Business/PTI |
| RUPEIA CALCULATION US$500m ÷ US$50m = 10 average-sized investments if all commitments were deployed in tickets of that size. On the Form D entity alone, US$185.4m ÷ US$50m = about 3.7 tickets. The platform number includes co-investment capacity, which is invested alongside the fund in selected deals, so the realistic count for the fund entity is a handful of primary positions plus follow-ons. |
|---|
9 WHAT A US$50 MILLION TICKET BUYS IN INDIA
| Stake acquired | Implied equity value of company (US$) | In ₹ crore at ₹96.5 per US$ |
|---|---|---|
| 10% | 500m | 4,825 |
| 15% | 333m | 3,217 |
| 20% | 250m | 2,413 |
| 25% | 200m | 1,930 |
| 30% | 167m | 1,608 |
| RUPEIA CALCULATION Equity value = ticket ÷ stake: 50 ÷ 0.15 = 333; 50 ÷ 0.20 = 250; 50 ÷ 0.25 = 200. In rupees: 333 × 96.5 = ₹32,133m = ₹3,217 Cr; 250 × 96.5 = ₹2,413 Cr; 200 × 96.5 = ₹1,930 Cr. GEMGO II’s stake sizes are not published; the table shows the range of companies a US$50m cheque could back. The firm’s emerging-markets page gives a direct-investment target enterprise value of US$50–500m. |
|---|
At a ₹2,000–3,000 crore equity value the company is large by Indian family-business standards and small by listed-market standards. Such companies often have a promoter who wants a partner for the next stage rather than a sale: a minority investor with a seat at the table and a route to an IPO or a sponsor sale in four to six years. The release’s phrase "founder and family-owned" describes this segment. Trimex Foods, at US$40 million for a first institutional round, fits the lower end of it.
10 GP QUALITY & TEAM
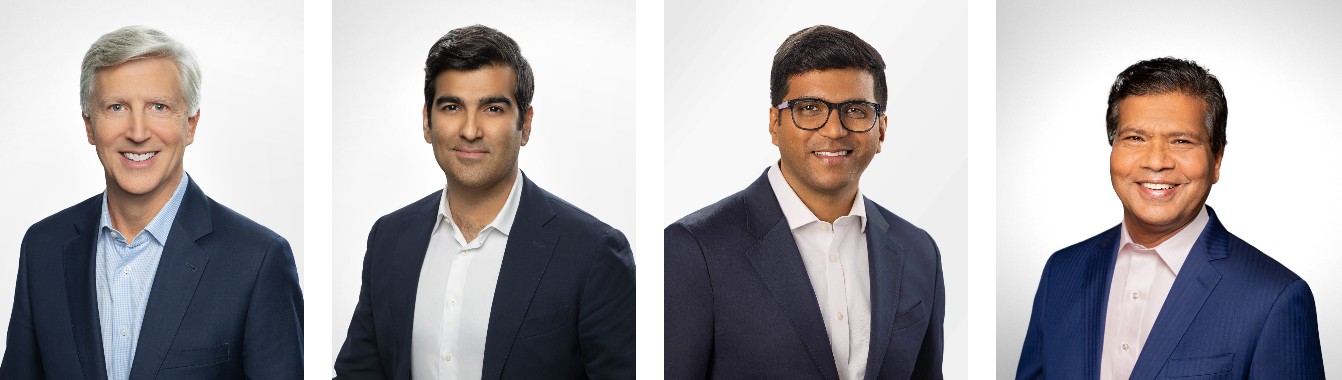
| Person | Published role | Source |
|---|---|---|
| Drew Guff | Co-Managing Partner and CIO; co-portfolio manager, GEMGO II; founding partner | Siguler Guff team page; release 19 Aug 2026 |
| Shaun Khubchandani | Partner; co-portfolio manager, GEMGO II; Co-Head of Emerging Markets | Release; team page; ANI 2024 |
| Sean R. MacDonald | Partner and Co-Head of Emerging Markets | Team page |
| Aviral Jain | Managing Director and Head of India (May 2024); not on the team page read on 7 Nov 2026 | ANI via ThePrint |
| Ranjan Panda; Prabhas Panigrahi | Managing Directors, listed on the team page (locations not given) | Team page |
| Other India-related staff | Sumil Sethi (VP) and four analysts or associates named on the team page | Team page |
| George Siguler | Executive Chairman | Team page |
The team page lists 144 named professionals firm-wide, and does not state locations or label any person as India head. The firm website states the emerging-markets platform was established in 1995 and that the firm’s partners have invested in emerging markets since the early 1990s. Drew Guff said in 2014 that the firm was in 1995 the first US private-equity firm to invest in Russia and in 2005 the first to raise a multi-manager fund targeting the BRICs (PE Professional, 1 April 2014).
| RUPEIA READ The investment team is seasoned and stable at the top (Guff has been a founding partner since 1991), and the published India team is mid-sized. The caution is attribution: the 2024 head of India (Aviral Jain) does not appear on the current team page, and no page names who leads each India deal. An LP would ask for the deal-by-deal attribution and the key-person terms. |
|---|
11 TRACK RECORD: EARLIER FUNDS AND THE INDIA BOOK
| Fund or platform | Year | Size | Published detail |
|---|---|---|---|
| BRIC Opportunities Fund I | 2006 | About US$600m (fund of funds) | Closed above a revised US$500m target (Private Equity Analyst) |
| BRIC Opportunities Fund II | Not stated | US$1bn target (PE Hub headline); final size not read | Not stated |
| Emerging-markets fund of funds | 2011 | Not stated | PEI notes a 2011 launch |
| BRIC Opportunities Fund III | Mar 2014 | About US$650m | Fund investments and co-investments; multi-manager |
| Global Emerging Markets Direct Investment Fund | May 2021 | US$240m | China, India, Southeast Asia; direct |
| GEMGO II | Aug 2026 | US$500m incl. related vehicles | India direct |
No page read gives DPI, TVPI or IRR for any Siguler Guff emerging-markets fund. The India book is described only by amount and names: about US$1 billion invested in 23 companies, including Indian Energy Exchange, GlobalLogic, City Union Bank, Luker Electric Technologies, Baazar Kolkata and Sterling Hospitals (release, 19 August 2026). The May 2024 coverage adds Manappuram Finance, Repco Home Finance, Relisys and Verse Innovation. The firm’s emerging-markets page lists "Current 14, Realized 12" without saying which names are in which group. No entry years, exits or returns are given.
| RUPEIA READ The India record is a list of companies with no returns attached. Listed names (IEX, GlobalLogic, City Union Bank, Manappuram, Repco) mean an outside reader could in principle reconstruct some outcomes from public prices, but not Siguler Guff’s entry price or holding period, so no return can be stated here. |
|---|
12 READING THE AUM STATEMENTS OVER TIME
| RUPEIA CALCULATION AUM rose from over US$10bn (April 2014) to about US$18.4bn (31 December 2025): +84% in about 11.75 years, or about 5.3% a year compounded (1.84^(1/11.75) − 1). The firm describes "assets under management" with affiliates, across multi-manager, direct and separate-account strategies, and the emerging-markets platform is US$5bn on its own page. GEMGO II’s US$500m is about 2.7% of the firm total (500 ÷ 18,400) and 10% of the emerging-markets platform (500 ÷ 5,000). |
|---|
These ratios are context rather than evidence of quality. They say that India is a significant but not dominant exposure for the firm and that a US$500 million India fund is a large single commitment inside an emerging-markets platform of about US$5 billion. The firm’s own history, a first fund-of-funds in 2006 and multi-country direct funds since, shows a repeated pattern of building a specialist team in a geography after earlier allocation through managers.
13 RECENT INVESTMENTS: SPANDANA, TRIMEX AND OTHERS
| Company | Sector | Date | Amount | Stake | Source |
|---|---|---|---|---|---|
| Spandana Sphoorty Financial | Microfinance NBFC (listed) | 6 May 2024 | ₹240 Cr | About 3.5% | ANI via ThePrint; Hans India |
| Trimex Foods | Franchise restaurants and bakery-cafés | 29 Apr 2026 | US$40m | Not stated | Hospemag; Whalesbook |
| Rajasthan Royals | IPL franchise | 2025–2026 | Reported US$40m, sub-10% (one report) | Not confirmed | Left Field; Outlook Business/PTI |
| Valliance.ai | AI-native consulting | 2026 | Not stated | Not stated | Outlook Business/PTI |
| La Renon | Domestic formulations | 2026 | Not stated | Not stated | Outlook Business/PTI; Venture Intelligence |
ANI’s May 2024 release put Spandana’s assets under management at about ₹11,970 crore and return on assets rising from 1.6% to 4.5% over two years; it did not state the price per share or whether the investment was a preferential issue or a market purchase. Trimex Foods, founded in 2010, operates Chili’s Grill & Bar, PAUL and Cinnabon in India across more than 50 restaurants and bakery-cafés in 13 cities with about 1,900 employees, and the investment was described as its first institutional capital raise (Hospemag, 29 April 2026; Whalesbook). A Left Field report on the Rajasthan Royals sale said Siguler Guff had invested US$40 million for under 10% and that the Mittal family agreed to buy 75% for US$1.65 billion, with completion subject to approvals; Outlook Business/PTI lists Rajasthan Royals among the first GEMGO II deals.
| RUPEIA CALCULATION ₹240 Cr for about 3.5% implies Spandana’s equity valued at about ₹6,860 Cr at the price paid (240 ÷ 0.035), if the 3.5% is taken as exact. The release gives no price per share, so this is an approximation only. Trimex’s US$40m at about ₹96.5 per US$ is about ₹386 Cr (40 × 96.5). |
|---|
14 CASE NOTES: SPANDANA SPHOORTY, TRIMEX FOODS AND RAJASTHAN ROYALS
Spandana Sphoorty (May 2024): the listed route
Siguler Guff’s ₹240 crore stake of about 3.5% in Spandana was made public by ANI on 6 May 2024. Aviral Jain, then Managing Director and Head of India, was quoted saying Spandana "stands overlooked amongst India’s publicly traded lending institutions", and Khubchandani said the firm was "excited about deepening our commitment to India". The release gave Spandana’s assets under management at about ₹11,970 crore and return on assets rising from 1.6% to 4.5% over two fiscal years. It did not name which Siguler Guff fund held the stake, which means a reader cannot tell whether GEMGO II, an earlier fund or a managed account owns it. The deal shows that the firm’s India approach includes minority positions in listed financial companies, not only unlisted founder-led businesses.
Trimex Foods (April 2026): the franchise consumer bet
Trimex Foods operates Chili’s Grill & Bar, PAUL and Cinnabon franchises in India: more than 50 restaurants and bakery-cafés in 13 cities, about 1,900 employees, founded 2010 and, per Hospemag and Whalesbook, raising its first institutional capital. Khubchandani called it "a structural shift as consumers increasingly gravitate toward globally recognized dining experiences". A Trimex spokesperson said the company was "delighted to welcome Siguler Guff as our partner".
| RUPEIA CALCULATION US$40m × ₹96.5 = about ₹386 Cr. Spread over more than 50 outlets that is about ₹7.7 Cr per existing outlet (386 ÷ 50), a ratio that has no meaning for returns, because the money is for growth and the stake is not disclosed. It does show that the cheque is large relative to a franchise business of this footprint, which is consistent with a plan for rapid roll-out. |
|---|
Rajasthan Royals: what is and is not known
Outlook Business/PTI lists Rajasthan Royals among GEMGO II’s first deals. Left Field reports that Siguler Guff bought a stake of under 10% for about US$40 million, and that the Mittal family agreed to buy 75% for US$1.65 billion, with Adar Poonawalla taking about 18% and existing shareholders keeping about 7% (Statesman, as summarised by search results); completion was expected in the third quarter of 2026, subject to BCCI, CCI and IPL Governing Council approvals. Whether the sale has closed, and what share of the 7% retained or the 75% sold relates to Siguler Guff, is not stated in the sources read.
| Illustrative stake held | Value at US$2.2bn (implied 100%) | Multiple of a US$40m cost |
|---|---|---|
| 4% | US$88m | 2.2x |
| 6% | US$132m | 3.3x |
| 8% | US$176m | 4.4x |
| RUPEIA CALCULATION US$1.65bn for 75% implies US$2.2bn for 100% (1,650 ÷ 0.75). The stake sizes in the table are illustrations only: the reported "under 10%" is not a number, and a US$40m cost is the only reported entry figure (one source). The table shows the range of outcomes, not Siguler Guff’s result. |
|---|
15 LP BASE
| Question | Published |
|---|---|
| Investors in the main entity | 35 (Form D, 3 Sep 2026); 12 in Aug 2023 |
| Investor types | "Pension plans, family offices, financial institutions, foundations and ultra-high-net-worth individuals" (Venture Intelligence) |
| Named LPs | None |
| GP commitment | Not disclosed |
| Firm client base | More than 800 institutional and 1,000 family-office and HNW clients (website) |
| Indian LPs or feeder | None published |
The investor count rose from 17 to 35 between July 2025 and September 2026 while the sold amount rose by US$79.7 million, which implies the new investors averaged about US$4.4 million each (79.7 ÷ 18). That is small for an institutional commitment and consistent with a late-closing group of family offices and individuals.
16 FUND MATHS: WHAT IT TAKES TO RETURN THE FUND
| Target gross multiple | On US$500m | On US$185.4m (Form D entity) |
|---|---|---|
| 1.0x | US$500m | US$185.4m |
| 2.0x | US$1,000m | US$370.7m |
| 2.5x | US$1,250m | US$463.4m |
| 3.0x | US$1,500m | US$556.1m |
Gross to net: an illustration
Siguler Guff has not published fees or carry for GEMGO II. Using a conventional growth-equity structure purely to show the mechanics: management fees of 2% a year for 8 years on US$185.4m cost US$29.7m, leaving US$155.7m to invest. A 2.5x gross multiple on US$155.7m returns US$389.3m. A 20% carry on profit above the US$185.4m paid in is US$40.8m ((389.3 − 185.4) × 20%). LPs receive US$348.5m, a net multiple of about 1.88x on US$185.4m paid in. These are Rupeia’s assumptions, not Siguler Guff terms.
The currency layer
The fund invests in rupee assets and reports in US dollars. At an illustrative 3% a year of rupee depreciation, a 15% dollar IRR needs an 18.45% rupee return (1.15 × 1.03 − 1). The 3% rate is Rupeia’s assumption; the brief rate for 2026 is about ₹96.5 per US$.
| RUPEIA CALCULATION Fees: 185.4 × 2% × 8 = 29.7. Investable: 185.4 − 29.7 = 155.7. Proceeds at 2.5x: 155.7 × 2.5 = 389.3. Carry: (389.3 − 185.4) × 20% = 40.8. Net: 389.3 − 40.8 = 348.5; ÷ 185.4 = 1.88x. Taxes depend on the investor’s jurisdiction and are not modelled. |
|---|
17 THE CURRENCY LAYER IN DETAIL
| Assumed annual rupee depreciation | Rupee return needed for a 15% dollar IRR | Rupee return needed for a 20% dollar IRR |
|---|---|---|
| 0% | 15.0% | 20.0% |
| 2% | 17.3% | 22.4% |
| 3% | 18.5% | 23.6% |
| 4% | 19.6% | 24.8% |
| RUPEIA CALCULATION Rupee return = (1 + dollar IRR) × (1 + depreciation) − 1. For 15% and 3%: 1.15 × 1.03 − 1 = 18.45%. For 20% and 3%: 1.20 × 1.03 − 1 = 23.6%. The depreciation rates are Rupeia’s assumptions for illustration. Whether GEMGO II hedges is not disclosed; hedging would replace the drag with a cost. |
|---|
Siguler Guff describes an investment style of buying growth in companies serving both domestic consumption and global demand. Exporters and technology services companies earn dollars and so are partly naturally hedged; domestic consumer and financial companies are not. The release names both types of sector. Because the fund is denominated in dollars, the mix of the portfolio between those two groups matters for the final dollar return.
18 REFERENCE FUND IN DETAIL: CHRYSCAPITAL FUND X
| Item | ChrysCapital Fund X | Siguler Guff GEMGO II |
|---|---|---|
| Size | US$2.2bn | US$500m incl. related vehicles |
| Announced | 5 Nov 2025 | 19 Aug 2026 |
| Previous fund | US$1.35bn (2022) | US$240m (2021, three-country direct fund) |
| Deal size | US$75–200m | About US$50m |
| Deployment plan | Three to four years | Not stated (one report says deployment has begun) |
| Investor base | First time domestic investors included (Business Standard) | 35 investors on Form D; no domestic route |
| Firm track record | About US$8.5bn raised across ten PE funds, a continuation vehicle and a public-markets fund | About US$18bn AUM across all strategies |
| RUPEIA CALCULATION Fund X ÷ Fund IX = 2.2 ÷ 1.35 = 1.63, up 63%. GEMGO II’s US$500m is 23% of Fund X (500 ÷ 2,200). GEMGO II’s US$50m ticket is 25% of the top of ChrysCapital’s range (50 ÷ 200) and 67% of the bottom (50 ÷ 75). The two funds therefore overlap only at the large end of GEMGO II’s tickets, which is the segment where Siguler Guff competes with a domestic firm four times its size. |
|---|
19 MARKET CONTEXT: INDIA PRIVATE EQUITY IN 2026
| Measure | Published figure | Source |
|---|---|---|
| PE/VC funds raised, H1 2026 | US$21.2bn across 48 funds vs US$10.1bn in H1 2025 | EY-IVCA via IANS |
| Largest raise in the period | Bain Capital Asia Fund VI at US$10.5bn (pan-Asian) | EY-IVCA via IANS |
| PE/VC investment, H1 2026 | Down 36% to US$20.5bn; Q2 weakest in six years by value | EY-IVCA |
| ChrysCapital Fund X | US$2.2bn in Nov 2025; 60% above US$1.35bn Fund IX; first domestic LP money; deals US$75–200m | Business Standard; Inc42 |
Fund-raising has recovered while deal value has fallen, a mismatch that favours managers with dry powder and a defined segment. Siguler Guff’s US$50 million ticket sits below the US$75–200 million range ChrysCapital described for Fund X and above typical venture growth rounds, so competition for deals comes from both sides.
20 CAPABILITY MATRIX
| Capability | GEMGO II | Evidence |
|---|---|---|
| India-dedicated growth fund | YES | Release, 19 Aug 2026 |
| Named India-focused investment team | PARTIAL | Team page lists names, not locations or an India head |
| Fund-level returns published | NO | None in any source read |
| Domestic Indian LP route published | NO | US offshore structure on Form D |
| Co-investment programme | YES | Related co-investment vehicles in the US$500m |
| Multi-decade emerging-markets history | YES | Platform established 1995; BRIC funds from 2006 |
| Fees and terms disclosed | NO | Not in any source read |
| Open to new LPs | NO | Final close, 19 Aug 2026 |
The matrix records what is published in the sources read; NO means not published, not poor.
21 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Red flag | Evidence | Severity | Kill condition | What would resolve it |
|---|---|---|---|---|
| Headline mixes pools | US$500m vs Form D US$185.4m | MEDIUM | Fund entity much smaller than needed for 10 tickets | Split of fund, co-invest, SMA |
| No published returns | No DPI or IRR for any EM fund | HIGH | Weak realised record | Performance schedule by fund |
| Attribution | Head of India in 2024 not on team page | MEDIUM | Key-person departures | Named deal leads |
| Currency | Dollar fund, rupee assets | MEDIUM | Sustained rupee decline above 3–4% a year | Hedging policy |
| Concentration | About 10 tickets at US$50m | MEDIUM | One or two failures drive the fund | Diversification limits |
| Exit markets | Listed IPO window and sponsor sales | MEDIUM | Window closes | Completed exits |
| Access | Closed; offshore structure | INFO | n/a | Next fund |
22 SCENARIO ANALYSIS
| Scenario | What happens | Implication |
|---|---|---|
| Bull | Trimex, Rajasthan Royals and La Renon mark up; exits via IPOs or sponsor sales return capital early | Larger GEMGO III and domestic LPs |
| Base | Steady deployment of about 10 deals; mixed outcomes; returns in a low-to-mid-teens dollar IRR range | Platform stays at US$400–600m |
| Bear | Two or three write-offs; rupee falls; exit delays | Net returns under 1.5x; no follow-on fund |
23 LP SIGNAL AND RE-UP
The platform grew from a US$300 million target to US$500 million, and the Form D investor count rose from 12 in August 2023 to 35 in September 2026, which shows continuing demand. The 18 additional investors in the final 14 months at about US$4.4 million each suggest the incremental money came from smaller institutions and family offices. The strongest signal in the sources is the manager’s own: Siguler Guff raised US$500 million for India after raising US$240 million for a three-country strategy, and announced a record US$3 billion for its small-buyout strategy a month later, which indicates firm-wide fundraising momentum rather than India-specific pull alone.
24 INVESTOR CLASS ANALYSIS
For HNIs
GEMGO II is closed and is a US offshore structure. HNIs in India cannot subscribe; the practical route is the firm’s co-investment offerings to eligible investors, if available, and public-market positions in listed investees.
For family offices
Family offices were part of the final closes. Ask for the co-investment allocation policy, fee on co-invest, and the split between fund and managed accounts.
For institutions
Institutions with India allocations compare GEMGO II with ChrysCapital Fund X and domestic managers. The attraction is a US-regulated manager with a long emerging-markets record; the limit is the absence of India-specific returns.
For NRIs
NRIs face the same constraints as other individuals; investment in an offshore fund is subject to the NRI’s country of residence rules and FEMA reporting for any onward investment.
25 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| An offshore manager with long emerging-markets history | SIGULER GUFF | Since 1995; India book of about US$1bn | Returns unpublished |
| A larger domestic India PE manager | CHRYSCAPITAL | US$2.2bn Fund X | Larger tickets |
| Early-stage India exposure | ACCEL INDIA (Report 35) | Seed and Series A | Different stage |
| A mid-market India fund from a domestic sponsor | MIRAE ASSET MAVOF II (Report 07) | Similar ticket band | Different manager type |
26 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| Next Form D | Updated amount sold and investor count | Fund entity size |
| 2026–2027 | Rajasthan Royals sale completion | First reported liquidity event touching the portfolio |
| 2027 | Further GEMGO II deals | Pace of deployment |
| 2027 | Spandana and other listed holdings | Public marks |
| Next fund cycle | GEMGO III size | Re-up signal |
27 RUPEIA FINAL INDEPENDENT VIEW
Siguler Guff GEMGO II is a credible India mid-market growth fund from a large, long-established US manager. It is also an opaque headline: US$500 million is a platform number, the Form D entity holds US$185.4 million, and no fund-level returns are published for any of the firm’s emerging-markets funds.
The India book of about US$1 billion in 23 companies and early GEMGO II deals (Trimex, Rajasthan Royals) show the strategy is real and active. Anyone with access should ask for the split, the performance schedule and deal attribution before treating the headline as the fund size.
| THE RUPEIA NUMBER 37%: the share of the US$500m headline that the Form D entity had sold by September 2026 (US$185.4m). |
|---|
| RUPEIA VERDICT A well-pedigreed offshore manager with a focused India strategy, a closed fund and thin disclosure. It fits institutions and family offices already inside the Siguler Guff relationship. For everyone else, the useful signals are the Form D updates and the listed holdings. |
|---|
Frequently asked questions
How much did Siguler Guff raise for GEMGO II?
US$500 million of capital commitments across the fund, related co-investment vehicles and separately managed accounts, announced on 19 August 2026. The Form D for the main entity shows US$185.4 million sold as of 3 September 2026.
What does GEMGO II invest in?
High-growth, founder- and family-owned Indian businesses with an average investment of about US$50 million in consumer, healthcare, financial services and technology.
Who runs GEMGO II?
Drew Guff, Chief Investment Officer, and Shaun Khubchandani, Partner, are co-portfolio managers.
What has GEMGO II invested in so far?
Outlook Business/PTI names Trimex Foods, Rajasthan Royals, Valliance.ai and La Renon. Trimex was reported at US$40 million in April 2026.
How much has Siguler Guff invested in India?
About US$1 billion across emerging-markets vehicles in 23 companies, per the firm’s release of 19 August 2026.
How large is Siguler Guff?
About US$18.4 billion of assets under management at 31 December 2025, per Outlook Business/PTI.
What returns has the firm published for India?
None at fund level. No DPI, TVPI or IRR appears in the sources read.
Can Indian investors subscribe?
No Indian route has been published; the fund is closed and structured as a US offshore fund.
How does GEMGO II compare with ChrysCapital Fund X?
ChrysCapital closed US$2.2 billion in November 2025 for US$75–200 million deals; GEMGO II is US$500 million including related vehicles with about US$50 million tickets.
What are the main risks?
Unpublished returns, a headline that mixes pools, key-person attribution, rupee depreciation, concentration in about ten positions and exit-market conditions.
Source log
Outlook Business / PTI: Siguler Guff raises US$500 Mn for India mid-market private equity strategy
DealStreetAsia: Siguler Guff raises US$500m fund to back high-growth businesses in India
Venture Intelligence: Siguler Guff raises US$500m fund to invest in mid-market companies
Venture Intelligence: Siguler Guff raises US$110m for US$300m fund GEMGO II
FormDs: Siguler Guff GEMGO II (A), LP filings
PipelineRoad: Siguler Guff GEMGO II Form D/A, 3 Sep 2026
Siguler Guff: About
Siguler Guff: Team
Siguler Guff: News
Siguler Guff: Small business credit strategy
Siguler Guff: closes over US$900 million for latest small business credit fund (2024)
Siguler Guff: raises over US$450 million for second small business credit fund (2021)
Siguler Guff: raises US$300 million to seed small business lending platform (2017)
PE Hub: Siguler Guff hits market with US$1b emerging-market fund of funds
PE Professional: Siguler Guff closes third BRIC fund
Private Equity International: Siguler Guff closes BRIC FoF on US$650m
Global Private Capital Association: Siguler Guff reaches US$240m final close
Private Equity Analyst (via Siguler Guff): emerging-markets fund of funds at US$600m (2006)
ANI via ThePrint: Siguler Guff builds ₹240 crore stake in Spandana Sphoorty
The Hans India: Siguler Guff to invest ₹240 crore in Spandana Sphoorty
Hospemag: Siguler Guff invests US$40 million in Trimex Foods
Whalesbook: Siguler Guff pours US$40M into Trimex Foods
The Left Field: The Rajasthan Royals close
ThePrint: Mittal family buys 75% stake in Rajasthan Royals
Business Standard: ChrysCapital raises record US$2.2 bn fund
Inc42: ChrysCapital closes Fund X at US$2.2 Bn
IANS: India’s PE and VC fundraises more than double to US$21.2bn in Jan–June
Entrepreneur India: PE/VC investments in India reach USD 20.5 Bn
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|