Accel India Fund IX: US$550 million
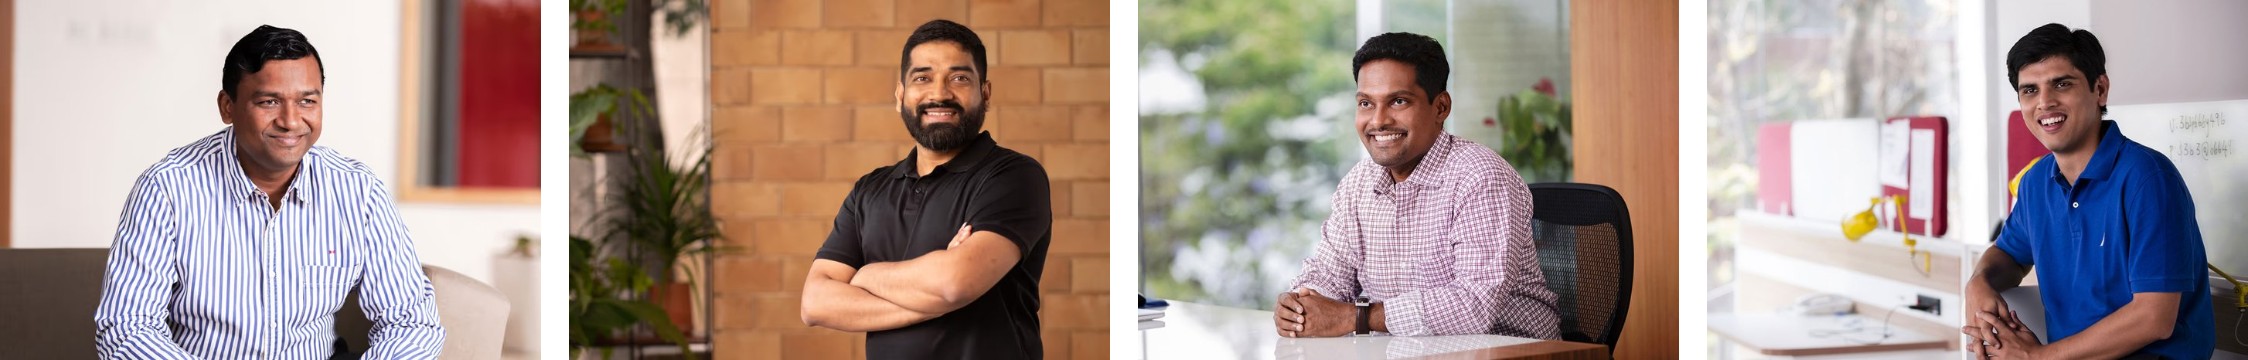
Accel India team, left to right: Shekhar Kirani, Prayank Swaroop, Anand Daniel, Abhinav Chaturvedi · Image: Accel website, People page
Independent report content
| MANAGER | Accel, founded 1983 by Arthur Patterson and Jim Swartz (TNW) · India office since 2008 · India team led by partners including Shekhar Kirani and Prayank Swaroop |
|---|---|
| FUND | Ninth India early-stage fund · US$550m · announced 11 Aug 2026 as one of four vehicles totalling US$3.5bn |
| SPEED | TechCrunch: oversubscribed and closed within weeks, 19 months after the US$650m Fund VIII; more than 55% of Fund VIII still unspent |
| DEPLOYMENT | Fund IX starts investing in 2027; Fund VIII keeps investing until then (Kirani to TechCrunch) |
| STRATEGY | Seed to Series A in AI, consumer, fintech, advanced manufacturing and deep tech; Accel says it is first institutional cheque in the vast majority of backings |
| HISTORY | Funds of US$155m (III), US$325m (IV), US$450m (V), US$650m (VII), US$650m (VIII), US$550m (IX) · ~US$3bn+ committed to India (Inc42) |
| TERMS | Fees, carry, LP names and DPI: not disclosed. Fund VIII had 131 undisclosed investors in SEC filings |
| THE ACCESS POINT Accel India Fund IX has closed and was oversubscribed. No retail or AIF feeder route has been published. Fund VIII investors were 131 undisclosed institutions and individuals per SEC filings. Individuals can reach the portfolio only through co-investments offered by Accel to existing relationships, through portfolio-company secondaries, or through listed holdings. |
|---|
Executive decision summary
| THE BOTTOM LINE | Accel is the most proven early-stage venture firm in India and it did something unusual on 11 August 2026: it shrank its India fund. Fund IX is US$550 million, US$100 million smaller than the US$650 million Fund VII and Fund VIII, and it closed within weeks, 19 months after Fund VIII, even though more than 55% of Fund VIII is still uninvested. It was one of four funds raised together (US$3.5 billion in total, the first time in 43 years that Accel has raised its full global lineup in one go, per Techfundingnews citing Bloomberg). The record behind it is public in pieces: Swiggy sold at about 35x, Urban Company at 27x, BlueStone at 8x, Amagi at 3.3x, and a pipeline that includes Cult.fit. What is not public is fund-level DPI, net IRR, fees or the LP list. |
|---|---|
| WHICH INVESTOR | Accel India fits you IF you are an institution or family office with an existing Accel relationship, you want the most documented Indian seed and Series A franchise, and you accept that the fund is closed and fund-level returns are not published. Wait IF you need net IRR and DPI by vintage before committing. None of the Accel India fund-level return numbers are public in the sources read for this report. |
| COMFORT FIT | Accel India = the oldest orchard in the district. Planted in 2008, ten harvests of Flipkart, Swiggy, Freshworks, Urban Company. The trees are known; the soil is the question. Fund IX at US$550m = a restaurant that closed a table to keep the service sharp. Smaller than the last two funds on purpose. The US$3.5 billion global raise = four kitchens opened on the same day. India is the smallest of the three regional ones. Peak XV (US$1.3bn across three funds, Feb 2026) and Nexus (US$700m Fund VIII, Dec 2025) = the two rivals closest in style and size. |
| THE RUPEIA NUMBER | US$100 million. The amount by which Fund IX (US$550m) is smaller than Fund VIII (US$650m), a 15.4% cut, in the same weeks as the US and Europe-and-Israel funds were raised at US$800m each against US$650m predecessors (TNW). India is the one regional fund in the set that is smaller than its predecessor. |
1 CLAIM REGISTER: EVIDENCE GRADING
A = government, regulator or statutory filing. B = company or manager release, website or filing. C = independent press. D = third-party database, blog or aggregator.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Accel raised US$3.5bn across four vehicles on 11 Aug 2026 | Accel announcement; TechCrunch; TNW; Dealroom | B | Established |
| India fund size US$550m; ninth India fund | TechCrunch, Inc42, Entrepreneur India, DealStreetAsia headline | C | Established; Accel’s own post does not name the India fund |
| Oversubscribed; closed within weeks | TechCrunch, citing people familiar | C | Single-source, anonymous |
| More than 55% of Fund VIII unspent | TechCrunch, citing people familiar; Kirani declined to give a figure | C | Anonymous source |
| Fund VIII US$650m; 131 investors | SEC filings via Entrepreneur India; Inc42 | A | Established |
| Fund IX targeted US$700m | Whalesbook, 3 Jun 2026 (carries an AI-content disclaimer) | D | Conflicts with all other sources |
| Swiggy ~35x; Urban Company 27x; BlueStone 8.12x; Amagi 3.3x | Outlook Business; Inc42 | C | Company-level, not fund-level |
| Fees, carry, LP list, DPI, net IRR | None published | — | Not disclosed |
2 FUND SNAPSHOT: FUND IX AGAINST THREE PEERS
| Fund | Size | Timing | Scope | Published status |
|---|---|---|---|---|
| Accel India Fund IX | US$550m | Aug 2026 | India; seed to Series A; AI, consumer, fintech, manufacturing, deep tech | Closed; deploys from 2027 |
| Accel India Fund VIII (predecessor) | US$650m | Dec 2024 / Jan 2025 | India; AI, consumer "Bharat", fintech, manufacturing | 131 investors; more than 55% unspent (Aug 2026) |
| Peak XV Partners, three funds | US$1.3bn | Feb 2026 | India Seed, India Venture, APAC | Prior fund US$2.85bn (TechCrunch) |
| Nexus Venture Partners Fund VIII | US$700m | Dec 2025 | India and US; inception, seed, Series A | Fund VII also US$700m (2023) |
| RUPEIA READ All three leading India early-stage managers have now held or cut fund size: Accel from US$650m to US$550m, Peak XV from US$2.85bn to US$1.3bn across three funds, Nexus flat at US$700m. The 2021 pattern of each fund being bigger than the last has ended in India. Smaller funds need smaller exits to return capital, which is the argument Accel has made in public since January 2025. |
|---|
3 TIMELINE: 2008–2026
| Date | Event |
|---|---|
| 2008 | Accel establishes its India office; acquires the Erasmic Venture Fund (TechCrunch, AVCJ) |
| Nov 2011 | US$155m third India fund (PR Newswire dated 16 Nov 2011; PEI gives Jan 2013) |
| Nov 2016 | US$450m fifth India fund, closed about two years after the fourth (TechCrunch, AVCJ) |
| Late 2019 | Sixth India fund unveiled (TechCrunch, Mar 2022) |
| Mar 2022 | US$650m seventh India fund (TechCrunch) |
| Nov 2024 – Jan 2025 | US$650m eighth India fund; Swiggy lists; Accel sells 10.5m shares (Outlook Business) |
| Apr 2025 | Rachit Parekh and Pratik Agarwal promoted to partner (Outlook Business/PTI) |
| Oct–Nov 2025 | Accel and Prosus launch Atoms X; Google AI Futures Fund and Accel launch the Atoms AI cohort |
| Apr 2026 | US$5bn late-stage raise: US$4bn Leaders Fund V plus US$650m sidecar (TNW) |
| 11 Aug 2026 | US$3.5bn across four funds including US$550m India Fund IX |
| Aug–Sep 2026 | Accel sells Urban Company, Amagi and BlackBuck shares; RentoMojo lists with an Accel offer for sale |
| 2027 | Fund IX expected to begin deploying (Kirani) |
4 THE MANAGER: ACCEL
Accel was founded in 1983 by Arthur Patterson and Jim Swartz (TNW, 15 April 2026). TNW says the firm wrote the first institutional cheque into Atlassian, CrowdStrike, Flipkart and Slack and cites a portfolio of 1,199 companies, 107 unicorns and 46 IPOs; Pulse 2.0 says "more than 800 companies over its history". Offices differ by source: Silicon Valley, London and Bangalore (tech.eu) or Palo Alto, San Francisco, London and India (TNW). In 2026 it has raised a US$5bn late-stage pool in April and US$3.5bn of early-stage and growth funds in August: TNW and Techfundingnews both estimate about US$8.5bn in new capital since spring.
| Vehicle | Size | Purpose | Source |
|---|---|---|---|
| Leaders Fund V | US$4bn | Late-stage AI; 20–25 deals at about US$200m average cheque | TNW, 15 Apr 2026 |
| Leaders sidecar | US$650m | Lets LPs raise exposure to selected deals | TNW; Pulse 2.0 |
| Global expansion (growth) fund | US$1.35bn | Larger early-stage rounds and rapid follow-ons; can back companies of any regional fund | Dealroom; tech.eu; TechCrunch |
| US early-stage fund | US$800m | US | tech.eu; TNW |
| Europe and Israel early-stage fund | US$800m | Europe and Israel (TNW: ninth fund) | TNW citing Sifted |
| India early-stage fund | US$550m | India | TechCrunch; Inc42 |
On the novelty of the August raise, TNW says "all four were raised at the same time, which the firm has not done before in 43 years", and Techfundingnews, citing Bloomberg, calls it the first time the firm raised its full global lineup in one go. Dealroom, tech.eu and Pulse 2.0 do not carry the claim. Accel’s own post says "today we’ve raised US$3.5 billion across four vehicles" without naming the India fund or its size.
| RUPEIA READ The India fund is 16% of the August total (550 ÷ 3,500) and 6.4% of the combined US$8.5bn raised since April (550 ÷ 8,500). India is a regional fund inside a global franchise, not the centre of it. That cuts both ways: Indian companies get the global growth and late-stage platform, but Fund IX LPs share the franchise’s brand with much larger pools of capital. |
|---|
5 WHAT FUND IX IS: SIZE, SPEED AND UNSPENT CAPITAL
TechCrunch (11 August 2026) reported that Accel "closed an oversubscribed US$550 million India fund within weeks", 19 months after the previous US$650 million India fund, citing people familiar with the matter. Inc42 says roughly 18 months; TechCrunch’s body says less than two years. TechCrunch also reports that Accel "still has more than 55%" of the previous fund available for investment, again from anonymous sources, and that Kirani declined to say how much remains. Kirani said Accel expects to begin deploying Fund IX in 2027, and until then continues investing from Fund VIII.
| Item | Published | Source |
|---|---|---|
| Size | US$550m | TechCrunch, Inc42, Entrepreneur India, DealStreetAsia |
| Alternative figure | US$700m target, "ninth India-focused vehicle" | Whalesbook, 3 Jun 2026 |
| Gap to Fund VIII | 19 months (TechCrunch); about 18 months (Inc42) | As listed |
| Fund VIII unspent | More than 55%, anonymous | TechCrunch |
| Deployment start | 2027 | Kirani, TechCrunch |
| Stated focus | "AI, consumer, fintech, and now advanced manufacturing, and deep tech" | Kirani, TechCrunch |
| Stage | Early stage; first institutional cheque in roughly 80% of backings | TechCrunch |
| India commitments to date | "Over US$3bn" | Inc42 |
| RUPEIA CALCULATION More than 55% of US$650m is more than US$357.5m still to invest from Fund VIII in August 2026 (0.55 × 650). That is 65% of Fund IX’s size (357.5 ÷ 550). US$650m + US$550m = US$1.2bn raised for India across the two funds, which Techfundingnews reports as raised "in 18 months". The new fund was therefore raised while the old one was more than half unspent: the signal is LP demand and pre-emptive fundraising, not an investment-pace constraint. |
|---|
Numbering differs by source: Inc42 calls the January 2025 fund the eighth and the 2022 fund the seventh, while TechCrunch’s August report calls the January 2025 fund "the previous US$650 million India fund". Accel’s own post calls the Fund VIII announcement "our VIII fund for India’s boldest founders". This report follows Accel and Inc42: Fund VII (2022), Fund VIII (2025), Fund IX (2026).
6 GP QUALITY & TEAM
| Partner | Published role or focus | Source and date |
|---|---|---|
| Shekhar Kirani | Partner; argued against raising a bigger India fund; quoted on Fund IX | TechCrunch, 5 Jan 2025 and 11 Aug 2026 |
| Prayank Swaroop | Partner; leads the Google AI cohort; "significant opportunity in the application layer" | TechCrunch, Nov 2025 and Aug 2026 |
| Anand Daniel | Partner; led the Swiggy seed at a US$2m valuation | TechCrunch, 5 Jan 2025 |
| Pratik Agarwal | Promoted to partner Apr 2025; Atoms X with Prosus | Outlook Business/PTI; TechCrunch |
| Rachit Parekh | Promoted to partner Apr 2025; joined 2019; sourcing and founder partnerships | Outlook Business/PTI |
| Prashanth Prakash | Partner; expects six to seven portfolio companies to list in one to two years | Kotak Neo, 1 Oct 2026 |
| Abhinav Chaturvedi; Barath Shankar Subramanian | Listed on Accel’s people page; Subramanian paraphrased on AI adoption (TechCrunch) | Accel website; TechCrunch |
No page read reports partner departures from the India team; the only team change found is the April 2025 promotions. Accel’s own statement on the promotions promised "a hands-on approach, deep sector knowledge, and long-term alignment to every partnership". Kirani on the earlier size decision: "What we have at Accel is the perfect combination."
| RUPEIA READ The team looks stable and is getting younger at the top: two partners were promoted from inside in 2025 and portraits of eight India investors sit on the people page. For a venture fund, attribution of past wins to current partners matters more than headcount: Daniel led the Swiggy seed, and Kirani and Swaroop lead the AI and deep-tech push that Fund IX is built around. |
|---|
7 TRACK RECORD OF EARLIER FUNDS
| Fund | Year | Size | Published detail |
|---|---|---|---|
| Fund I and II | 2008 onwards | Not stated | India office opened 2008; Erasmic Venture Fund acquired |
| Fund III | 2011 (PR Newswire); Jan 2013 (PEI) | US$155m | Seed and early stage; 34 portfolio companies at announcement incl. Flipkart, Myntra |
| Fund IV | c. 2014 | US$325m (TechCrunch) / US$305m (AVCJ) | Held Urban Company, BlackBuck via Accel India IV (Mauritius) |
| Fund V | Nov 2016 | US$450m | Consumer, SaaS, fintech, B2B services, healthcare; Swiggy, BookMyShow, BlackBuck, BlueStone, Freshdesk |
| Fund VI | Late 2019 | Not on pages read (one aggregator: US$550m) | Holds Amagi via Accel India VI (Mauritius); first invested Sep 2021 |
| Fund VII | Mar 2022 | US$650m | Flipkart, Freshworks, Swiggy, Spinny, Zetwerk, Infra.Market, Moglix named |
| Fund VIII | Jan 2025 | US$650m | 131 investors; ~₹5,500 Cr; AI, "Bharat", fintech, manufacturing |
| Fund IX | Aug 2026 | US$550m | Deploys from 2027 |
The sizes in this table are the published ones: US$155m, US$325m or 305m, US$450m, US$650m, US$650m, US$550m. The fund-size path is therefore up from Fund III to Fund VII, flat for Funds VII and VIII, and down for Fund IX. No page read gives DPI, TVPI or IRR for any Accel India fund. Outlook Business reports Accel’s Flipkart exit in 2023 at about US$1.5–2bn of returns while also stating that Accel "retained its 1.1 percent stake"; TechCrunch (2022) said Accel would net more than US$1 billion from Flipkart; and TechCrunch (2025) calls Accel "the strongest returns of any venture fund in India", an industry assessment rather than a published figure.
| RUPEIA READ Accel’s India record is the best-documented in the market at company level and the least documented at fund level. A buyer of access to Fund IX is buying a brand and a pattern of repeat first cheques, with no published net return to anchor the price. |
|---|
8 CASE STUDIES: SWIGGY, URBAN COMPANY, BLUESTONE AND AMAGI
| Company | Entry | Exit event | Published return | Rupeia check |
|---|---|---|---|---|
| Swiggy | Daniel led the seed at a US$2m valuation (TechCrunch) | Nov 2024 IPO at about US$11.3bn; Accel sold 10.5m shares at ₹390 | ~35x (Outlook); 3,391% (Entrepreneur); ~₹412 Cr | 10.5m × ₹390 = ₹409.5 Cr, consistent with ₹412 Cr after rounding |
| Urban Company | Accel invested in the "formative years" (Angel One) | 2025 IPO sale, then Aug 2026 market sale | ₹390 Cr on ₹14.28 Cr cost = 27x (Inc42) | 390 ÷ 14.28 = 27.3x |
| BlueStone | Fund V-era backing (AVCJ) | 2025 IPO sale | ₹134.62 Cr on ₹16.58 Cr cost = 8.12x (Inc42) | 134.62 ÷ 16.58 = 8.12x |
| Amagi | First invested Sep 2021 (Venture Intelligence) | Jan 2026 IPO OFS of 50.73 lakh shares | 3.3x on ₹183.2 Cr (Inc42) | 183.2 ÷ 3.3 = about ₹55.5 Cr implied cost |
Two things stand out in the cases. First, the holdings are not fully sold. Accel said it wanted to "keep the 7%" of Urban Company for as long as it can, and after the 13 August 2026 sale it held 4.84% (Lapaas Voice). It held 1.76 crore Amagi shares worth about ₹637.8 crore after the IPO at ₹361 (Inc42). It still held 7.17% of BlackBuck at the end of June 2026 (Inc42). The returns quoted are therefore returns on the part sold, not on the whole position. Second, the multiples differ widely: 35x, 27x, 8x and 3.3x. A fund-level multiple is a weighted outcome of such results plus the many positions that return less than cost, and none of the sources give that weighted figure.
| RUPEIA READ Four named exits in the 3x to 35x range are the evidence for Accel’s repeat first-cheque pattern. They are not evidence of a fund multiple: the cost of each position and the full ledger of positions that returned less are private, and fund-level DPI needs both. |
|---|
9 THE FUND-SIZE PATH: WHAT THE NUMBERS SHOW
| Step | From | To | Change |
|---|---|---|---|
| Fund III to Fund IV | US$155m | US$325m | +110% |
| Fund IV to Fund V | US$325m | US$450m | +38% |
| Fund V to Fund VII (Fund VI size not on pages read) | US$450m | US$650m | +44% |
| Fund VII to Fund VIII | US$650m | US$650m | 0% |
| Fund VIII to Fund IX | US$650m | US$550m | −15.4% |
| RUPEIA CALCULATION The percentages are simple ratios of the published sizes: 325 ÷ 155 = 2.10; 450 ÷ 325 = 1.38; 650 ÷ 450 = 1.44; 550 ÷ 650 = 0.846. Between Fund III in 2011 and Fund VII in 2022 the India fund grew about 4.2 times (650 ÷ 155). Fund IX is the first reduction in the published series. Using AVCJ’s US$305m for Fund IV instead of TechCrunch’s US$325m changes the Fund III to IV step to +97% and Fund IV to V to +48%; the conclusion does not change. |
|---|
Kirani’s January 2025 reasoning, as TechCrunch reported it, was that historic studies in the United States and China show returns fall as funds grow beyond about US$600–650 million, even in well-established markets. Anand Daniel said Accel wanted "to raise the right size early-stage fund to be able to generate good returns". Fund IX takes the argument one step further: it is below the range Kirani described, which means Accel is not treating US$650 million as a ceiling to be reached but as a level to step back from when the opportunity set does not justify it.
10 EXITS AND DISTRIBUTIONS, 2025–2026
| Company | Event | Proceeds | Multiple or stake | Source |
|---|---|---|---|---|
| Swiggy | OFS at IPO, 10.5m shares | ~₹412 Cr at ₹390 | ~35x (Outlook); 3,391% (Entrepreneur) | Outlook Business; Entrepreneur India, 2 Jan 2025 |
| Urban Company | IPO sale | ₹390 Cr vs ₹14.28 Cr cost | 27x | Inc42, 13 Dec 2025 |
| BlueStone | IPO sale | ₹134.62 Cr vs ₹16.58 Cr cost | 8.12x | Inc42 |
| Amagi | IPO OFS, Jan 2026 | ₹183.2 Cr (50.73 lakh shares) | 3.3x; 1.76 cr shares held | Inc42, 20 Jan 2026 |
| Urban Company | Open-market sale, 13 Aug 2026 | ~₹272 Cr (2 cr shares) | 6.14% to 4.84% (Accel India IV) | Lapaas Voice |
| BlackBuck | Block deal, 11 Sep 2026 | ₹155.5 Cr (27 lakh shares at ₹576.05) | 7.17% held end-June 2026 | Inc42, 12 Sep 2026 |
| Amagi | Block deal, Aug 2026 | ₹587.3 Cr combined, with Avataar | Accel share not split | Venture Intelligence |
| RentoMojo | IPO, Sep 2026 | Accel OFS ~₹317 Cr | n/a | Kotak Neo, 1 Oct 2026 |
| Rapido | Secondary purchase | Accel paid ~₹144 Cr (~US$16m) | Bought 11,997 shares from TVS Motor | TechCrunch, 6 Nov 2025 |
| RUPEIA CALCULATION Disclosed Accel sales: 2025 IPOs (Urban Company ₹390 Cr + BlueStone ₹134.62 Cr = ₹524.62 Cr, matching Inc42’s total) plus 2026 sales (Urban ₹272 Cr + BlackBuck ₹155.5 Cr + Amagi OFS ₹183.2 Cr + RentoMojo ₹317 Cr = ₹927.7 Cr). Total about ₹1,452 Cr, or about US$150m at ₹96.5. These come from older funds (Accel India IV and VI are named), not from Fund VIII. The only two sales tied to Fund IV (Urban Company and BlackBuck in 2026) are ₹427.5 Cr, about US$44m, about 14% of a US$325m fund. Accel’s Swiggy, Flipkart and Freshworks proceeds are not included. |
|---|
Prashanth Prakash told Kotak Neo that six to seven portfolio companies could list in the next one to two years, naming HomeLane and BookMyShow, and said Accel looks for growth above 30% and double-digit EBITDA margins. Cult.fit filed a draft prospectus in July 2026 with Accel among the selling shareholders; Moneyview listed on 1 October 2026. Inc42 listed Zetwerk, Moglix and Cult.fit as IPO-ready.
11 LP BASE
Fund VIII drew commitments from 131 investors in a 31 December 2024 SEC filing, all undisclosed (Entrackr and Entrepreneur India). Fund IX’s investors are not named in any source read. TechCrunch’s oversubscription claim comes from anonymous sources. Accel’s institutional programmes (Atoms X with Prosus, the Google AI Futures Fund co-investment) are separate vehicles and not LP disclosures.
| LP question | Status |
|---|---|
| Number of investors in Fund IX | Not disclosed |
| Named LPs | None published |
| Fund VIII investors | 131, undisclosed (SEC filing) |
| GP commitment | Not disclosed |
| Domestic Indian LP route | No AIF feeder or retail route published |
| Re-up evidence | Fund IX raised US$550m in weeks while Fund VIII was more than half unspent: indirect |
12 STRATEGY
Accel describes Fund VIII as investing in "AI, consumer ‘Bharat’, fintech, manufacturing". Fund IX adds "deep tech" to the list (Kirani to TechCrunch), and Inc42 calls Accel "increasingly focused on AI/ML, deeptech and consumer startups, while retaining a largely sector-agnostic investment approach". Swaroop told TechCrunch there is "a significant opportunity in the application layer". Kirani told TechCrunch in January 2025 that Accel sees about 300 high-quality companies a year at pre-seed to Series A and aims for "about 40 through 60 to 70 total investments per fund cycle", a wording that is ambiguous as published.
| Programme | Terms (published) | Source |
|---|---|---|
| Atoms (pre-seed and seed) | Launched 2021; 36 start-ups and over US$200m raised (Outlook, Apr 2025); "more than 40" and over US$300m (TechCrunch, Nov 2025) | Outlook Business; TechCrunch |
| Atoms X with Prosus | Prosus matches Accel’s cheque; initial cheques US$100,000–1m; sectors automation, energy transition, manufacturing | TechCrunch, 26 Oct 2025 |
| Atoms AI with Google AI Futures Fund | Up to US$2m per start-up co-invested; up to US$350,000 in credits; three-month programme | Accel Atoms; Inc42, 25 Nov 2025 |
| Growth vehicle | US$1.35bn; can back companies from any regional fund "from inception through IPO and beyond" | TechCrunch |
| RUPEIA READ The strategy is a funnel: Atoms for the earliest cheques, Fund IX for seed to Series A, the growth vehicle and Leaders funds for later rounds. That is attractive for founders and for Accel’s deal flow, and it raises allocation questions for each fund’s LPs, covered in the next sections. |
|---|
13 PIPELINE: THE LISTING WINDOW FOR ACCEL’S INDIA PORTFOLIO
| Company | Status (as published) | Source |
|---|---|---|
| Cult.fit | DRHP filed July 2026: ₹950 Cr fresh issue plus offer for sale of up to 17.86 crore shares; Accel among sellers | Kotak Neo, 1 Oct 2026 |
| Moneyview | Listed 1 Oct 2026 | Kotak Neo |
| RentoMojo | Listed Sep 2026; Accel offer for sale about ₹317 Cr within a ₹1,255.57 Cr IPO | Kotak Neo |
| HomeLane; BookMyShow | Named by Prakash as future listing candidates | Kotak Neo |
| Curefoods; Captain Fresh; Amagi | Draft papers filed (as of Sep 2025); Amagi listed Jan 2026 | Angel One, 17 Sep 2025; Inc42 |
| Zetwerk; Moglix; Cult.fit | Described as "IPO-ready" | Inc42, 13 Dec 2025 |
Chaturvedi told Angel One in September 2025: "We are 10 years into the fund. So there’s clearly a three-year window, at least for us." The remark refers to an older fund approaching the end of its life; it is a reminder that Accel’s India funds are run to a clock, and that the listing pipeline is partly a function of that clock. Prakash told Kotak Neo that Accel looks for growth above 30% and double-digit EBITDA margins in listing candidates.
14 ATOMS, PROSUS AND GOOGLE: THE EARLIEST-STAGE FUNNEL IN DETAIL
| Programme | Eligibility | Money and support | Source |
|---|---|---|---|
| Atoms (core) | Pre-seed and seed, Indian and Indian-origin founders | Equity-backed; Accel counts 36 start-ups and over US$200m raised (Outlook, Apr 2025) or more than 40 and over US$300m follow-on (TechCrunch, Nov 2025) | Outlook Business; TechCrunch |
| Atoms X | "Leap tech" start-ups; launched in July (TechCrunch, Oct 2025) | Prosus matches Accel’s cheque; initial US$100,000–1m "that could increase over time"; prior co-investments Arivihan and Wiom | TechCrunch, 26 Oct 2025 |
| Atoms AI cohort 2026 | Idea or prototype stage; traction not mandatory; apply by 26 Jan 2026 | Up to US$2m co-invested with Google; up to US$350,000 of cloud and Gemini credits; three months; at least one Gemini integration (Accel) though TechCrunch says no exclusivity is required | Accel Atoms; Inc42; TechCrunch |
Prosus’s head of India ecosystem said Prosus is not seeking an equal equity stake (TechCrunch). Google’s representative said Google would be on cap tables and have "a material presence" but declined to compare its equity with Accel’s. Swaroop described the Atoms AI idea as a ready stack to help Indian founders "build and scale globally from day one" (joint statement with Kirani, Inc42). TechCrunch reports more than 30% of Atoms companies raised follow-on capital and that Accel led more than half of those rounds.
| RUPEIA CALCULATION If more than 30% of "more than 40" Atoms companies raised follow-on rounds and Accel led more than half of them, that is at least 12 follow-on rounds and at least 6 led by Accel (0.30 × 40 = 12; 12 × 0.5 = 6). Each is a first call on Fund IX capital at a price Accel has seen before anyone else. That is an information advantage for Accel’s funds and a question about allocation for LPs. |
|---|
15 PORTFOLIO: WHAT IS PUBLICLY NAMED
Accel names the following India backings on its Fund VIII page: Flipkart, Swiggy, Acko, BlackBuck, BrowserStack, Freshworks, Urban Company and Zetwerk. TechCrunch (2022) lists Flipkart, Freshworks, Swiggy, FalconX, Spinny, Vedantu, Zetwerk, Infra.Market and Moglix as Fund VII-era companies. Outlook Business adds FirstClub and Simplismart. Inc42 says Atoms X backed Praan, QOSMIC, Dognosis, Ferra and EtherealX. No page read gives portfolio-level marks, so Fund VIII and IX valuations are not disclosed.
16 CONFLICTS AND AFFILIATED VEHICLES
| Overlap | What is published | Question for an LP |
|---|---|---|
| Fund VIII and IX | More than 55% of VIII unspent when IX closed; both US$550–650m India funds | Allocation policy between the two for 2026–2027 deals |
| India funds and the global growth fund | Growth vehicle can back any regional fund company from inception | Who takes the follow-on cheque and at what price |
| Atoms X and Prosus | Prosus matches Accel’s cheque in each company | Whether Atoms companies are offered to Fund IX at the next round |
| Google AI Futures Fund | Google to be on cap tables, "a material presence" | Information rights and conflicts with Accel’s fund |
| Secondary purchases | Accel paid about US$16m for Rapido preference shares sold by TVS Motor | Which vehicle buys secondaries and how it is priced |
| Mauritius vehicles | Accel India IV and VI (Mauritius) are the sellers in 2026 block deals | Whether IX uses the same structure |
TechCrunch (January 2025) describes Accel India as operating a hybrid model with an India affiliate. No page read describes fee-sharing, allocation rules or investment-committee governance.
17 FUND MATHS: WHAT IT TAKES TO RETURN THE FUND
| Ownership at exit | Aggregate exit value to return US$550m (1x gross) | To return 3x gross (US$1.65bn) |
|---|---|---|
| 2% | US$27.5bn | US$82.5bn |
| 3% | US$18.3bn | US$55.0bn |
| 5% | US$11.0bn | US$33.0bn |
| RUPEIA CALCULATION Required aggregate exit value = fund size ÷ ownership at exit. Ownership at exit is not published for Accel India; 2%, 3% and 5% are illustrative. Swiggy’s IPO valued the company at about US$11.3bn (TechCrunch) and Accel sold 10.5m shares for about ₹412 Cr, which shows how a single outcome moves the maths. Kirani’s argument for capping funds at about US$600–650m is this equation: smaller funds need fewer billion-dollar outcomes. |
|---|
Gross to net: an illustration
Accel has not published fees or carry for Fund IX. Using the market-standard "2 and 20" purely to show the mechanics: fees of 2% a year for 10 years on US$550m cost US$110m, leaving US$440m to invest. A 3.0x gross return on that US$440m gives US$1,320m of proceeds. A 20% carry on profit above the US$550m returned is US$154m ((1,320 − 550) × 20%). LPs then receive US$1,166m, a net multiple of about 2.12x on US$550m paid in. Taxes depend on the LP’s jurisdiction and structure and are not modelled. These are Rupeia’s assumptions, not Accel terms.
18 PEERS IN DETAIL: PEAK XV AND NEXUS
| Measure | Accel India IX | Peak XV (Feb 2026) | Nexus VIII (Dec 2025) |
|---|---|---|---|
| Size | US$550m | US$1.3bn across India Seed, India Venture, APAC | US$700m (about ₹6,300 Cr) |
| Previous fund | US$650m | US$2.85bn (TechCrunch) | US$700m (2023) |
| Firm scale | US$3.5bn raised in Aug 2026 across four funds | More than US$10bn across 16 funds; over 450 companies | About US$3.2bn AUM (one report) |
| Geography | India | India, APAC | India and US |
| Cadence | Funds VII to IX in about 4.4 years (Mar 2022 to Aug 2026) | First major raise since the 2023 split from Sequoia | A new fund about every three years |
| RUPEIA CALCULATION Accel India IX ÷ Peak XV 2026 = 550 ÷ 1,300 = 42%. Accel India IX ÷ Nexus VIII = 550 ÷ 700 = 79%. Fund IX is the smallest of the three. Peak XV’s 2026 raise is 46% of its prior US$2.85bn (1.3 ÷ 2.85), a deeper cut in percentage terms than Accel’s 15.4%; Nexus held flat. Peak XV is reported not to plan a new growth fund until more of its existing dry powder is deployed (TechCrunch, via search summary). |
|---|
19 MARKET CONTEXT: INDIA’S VENTURE MARKET IN 2026
| Measure | Published figure | Source |
|---|---|---|
| PE/VC funds raised, H1 2026 | US$21.2bn across 48 funds vs US$10.1bn a year earlier (includes Bain Capital Asia Fund VI at US$10.5bn) | EY-IVCA via IANS |
| PE/VC investment, H1 2026 | Down 36% to US$20.5bn; Q2 weakest in six years by value | EY-IVCA |
| Start-up funding, H1 2026 | US$6.9bn, +21% (YourStory); US$5.2bn, −9% (Inc42); US$7.2bn, +12% (Tracxn) | As listed |
| AI start-ups, H1 2026 | US$676m across 57 deals | Inc42 |
The three start-up funding totals differ by definition and are shown side by side rather than reconciled. What the data agree on is that fund-raising has outpaced deployment: capital for funds has doubled while investment into companies fell or was flat. Peak XV’s February 2026 raise of US$1.3bn across three funds (about half of the prior US$2.85bn) and Nexus’s US$700m in December 2025 show the same pattern of flat or smaller funds.
20 CAPABILITY MATRIX
| Capability | Accel India | Peak XV | Nexus |
|---|---|---|---|
| Published exits above US$1bn of value (company level) | YES | YES | PARTIAL |
| Fund size cut or held in the latest fund | YES | YES | YES |
| Pre-seed programme | YES | YES | PARTIAL |
| Global growth platform behind the India fund | YES | PARTIAL | NO |
| Fund-level DPI published | NO | NO | NO |
| Open to new LPs for this fund | NO | NO | NO |
| AI and deep-tech thesis stated | YES | YES | YES |
The matrix records what is published in the sources read. A NO for DPI means the figure is not published, not that it is poor.
21 DISCLOSURE MAP: WHAT IS PUBLISHED AND WHAT IS NOT
| Item | Fund VIII | Fund IX |
|---|---|---|
| Fund size | US$650m (SEC filing) | US$550m (press; Accel names no figure for India) |
| Investors | 131, undisclosed | Not disclosed |
| Fees and carry | Not disclosed | Not disclosed |
| Investments to date | More than 55% unspent (anonymous source) | Deployment from 2027 |
| Named portfolio | Accel’s website list of eight companies | None yet |
| Realisations | Not itemised by fund | None |
| DPI, TVPI, IRR | Not disclosed | Not disclosed |
| Partners | Names on Accel website | Same team |
Nothing in this table is a criticism: Accel is a private firm with private LPs and no obligation to publish. It is a map of what a reader outside the LP base can and cannot know. The company-level facts in the exits table and the fund-level facts above are the whole of the public evidence.
22 THE GLOBAL AI PORTFOLIO AND WHAT IT MEANS FOR THE INDIA FUND
TNW and Pulse 2.0 name Accel’s global AI-era backings as Anthropic, Cursor, Perplexity, Vercel, Lovable, Monzo, Trade Republic, Vinted, Legora, n8n, Synthesia and Cyera, among others. TNW cites a statement that Accel invested in Anthropic when it was valued at about US$183bn and reports Anthropic valued near US$800bn since. These are global funds’ holdings: the India fund does not share in them. The relevance for Fund IX is the platform effect. Accel’s partners meet the leading AI companies, which shapes the questions they ask Indian founders, and the global growth vehicle can follow Indian winners with large cheques.
Kirani told TechCrunch that "the quality of ideas and quality of founders are significantly better" than before, and that Accel "will continue to invest, looking for the best of the best local winners". Swaroop said the opportunity is in the application layer rather than foundation models. That is a narrower bet than the global funds: India applications built on third-party models, where compute costs, model dependence and customer concentration drive margins.
| RUPEIA READ Fund IX has an AI tilt but is not an AI-model fund. The India AI numbers in the market are small against the global ones: Inc42 puts H1 2026 Indian AI start-up funding at US$676 million across 57 deals. A US$550 million fund concentrating on that segment alone would be oversized, which is why the stated mix also includes consumer, fintech, manufacturing and deep tech. |
|---|
23 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Red flag | Evidence | Severity | Kill condition | What would resolve it |
|---|---|---|---|---|
| Fund-level returns not published | No DPI, TVPI or IRR in any source | HIGH | Net returns well below the brand | LP-grade performance schedule |
| Pace of Fund VIII | More than 55% unspent 19 months after close | MEDIUM | Slow deployment, dated deals | Quarterly investment pace |
| IPO window | Pipeline depends on listings (Cult.fit, HomeLane, BookMyShow) | MEDIUM | Listing freeze for 24 months | Completed IPOs at prices above entry |
| AI valuations | Fund IX leans to AI and deep tech | MEDIUM | Down-rounds in AI seed | Revenue-backed AI portfolio |
| Overlap of vehicles | Atoms, growth fund, Leaders, two India funds | MEDIUM | Allocation disputes | Published allocation policy |
| Data conflicts | Fund numbering and sizes differ by source | LOW | n/a | Accel’s own fund disclosures |
| Access | Closed, no feeder route | INFO | n/a | Next fund cycle |
24 SCENARIO ANALYSIS
| Scenario | What happens | Implication |
|---|---|---|
| Bull | Cult.fit, HomeLane, BookMyShow and others list above entry; Fund VIII and IX AI bets mark up; growth vehicle takes follow-ons | Next India fund (about 2028–2029) could be larger |
| Base | Listings proceed slowly; sales from IV and VI continue; Fund IX begins in 2027 at a steady pace | Fund size holds near US$550–650m |
| Bear | IPO window closes; AI marks fall; deployment slows | Fund VIII drags into 2028; next fund smaller |
25 LP SIGNAL AND RE-UP
The re-up signal is indirect but strong: Fund IX closed in weeks and was oversubscribed (TechCrunch, anonymous), while Fund VIII was more than half unspent. A manager does not normally raise a successor in that position unless LPs ask for it. Against that, Accel cut the fund, so the signal is demand at a smaller size, not pressure to grow. The size cut is consistent with Kirani’s stated view that returns degrade above about US$600–650m.
26 INVESTOR CLASS ANALYSIS
For HNIs
Fund IX is closed and no AIF or feeder route is published. HNIs can reach Accel’s portfolio only through co-investment offers to existing relationships or private secondaries in portfolio companies, where pricing is set by sellers.
For family offices
A family office with an Accel relationship is the likely co-investor. Ask for allocation policy, co-invest fee terms and the difference between the growth and India funds before committing.
For institutions
The next realistic window is the following India fund. Institutions diligence the fund-size discipline, partner continuity and the overlap of vehicles.
For NRIs
NRIs have the same constraint as other individuals: no published route. Listed Accel holdings (Swiggy, Urban Company, Amagi, BlackBuck, RentoMojo) are open to the public market.
27 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| The most documented Indian early-stage franchise | ACCEL INDIA | Named exits at company level; stable team; size discipline | Closed; fund-level returns unpublished |
| A larger, multi-fund India platform | PEAK XV | US$1.3bn across three funds | Smaller than before |
| India plus US early-stage exposure | NEXUS | US$700m Fund VIII | Different mix |
| An AI-specific fund | ACTIVATE (Report 39) | US$105m AI venture fund | Smaller, newer |
28 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| Q4 2026 – 2027 | Cult.fit, HomeLane, BookMyShow listings | Tests the pipeline Prakash described |
| 2027 | Fund IX deployment begins | Shows pace and thesis |
| 2026–2027 | Fund VIII unspent share | Pace of the older fund |
| Ongoing | Further block sales from IV and VI | Realisations |
| Next cycle | Size of the following India fund | Whether discipline holds |
29 RUPEIA FINAL INDEPENDENT VIEW
Accel India Fund IX is the cleanest expression in the Indian market of a manager choosing a smaller fund because it believes returns fall above a certain size. The raise was fast, the team looks stable and the company-level record (Swiggy 35x, Urban Company 27x) is real and published.
What the market cannot see is the part that matters to an LP: net return by fund, fees, the LP list and the allocation rules between the many Accel vehicles that now share a pipeline.
| THE RUPEIA NUMBER US$100 million: the cut from Fund VIII (US$650m) to Fund IX (US$550m), 15.4%. |
|---|
| RUPEIA VERDICT A top-tier early-stage franchise with disciplined sizing and a closed fund. For institutions with an Accel relationship it is the reference point in Indian venture. For everyone else, the practical route is through listed portfolio companies and the signals in the early-warning table. |
|---|
Frequently asked questions
How big is Accel’s ninth India fund?
US$550 million, announced on 11 August 2026 as one of four funds totalling US$3.5 billion.
When does Fund IX start investing?
Kirani told TechCrunch that Accel expects to begin deploying Fund IX in 2027, and until then invests from the US$650 million Fund VIII.
Why is Fund IX smaller than Fund VIII?
Accel has not given a Fund IX-specific reason. In January 2025 Kirani said returns become "extremely hard" above roughly US$600–650 million, citing historic studies in the US and China.
What are the other three funds in the US$3.5 billion raise?
A US$1.35 billion global growth fund, an US$800 million US fund and an US$800 million Europe and Israel fund.
Who runs Accel India?
Partners named in the sources include Shekhar Kirani, Prayank Swaroop, Anand Daniel, Pratik Agarwal, Rachit Parekh and Prashanth Prakash; Abhinav Chaturvedi and Barath Shankar Subramanian appear on Accel’s people page.
What returns has Accel India published?
No fund-level DPI, TVPI or IRR. Company-level figures include Swiggy about 35x, Urban Company 27x, BlueStone 8.12x and Amagi 3.3x.
Can individuals invest in Accel India Fund IX?
No route has been published. The fund is closed. Individuals can buy listed Accel portfolio companies on the stock market.
How does Accel compare with Peak XV and Nexus?
Peak XV raised US$1.3 billion across three funds in February 2026 (prior US$2.85 billion); Nexus closed US$700 million for Fund VIII in December 2025. Accel’s India fund is US$550 million.
What is Accel Atoms?
Accel’s pre-seed and seed programme, launched in 2021, with Atoms X (with Prosus) and Atoms AI (with Google’s AI Futures Fund) tracks.
Which Accel India companies could list next?
Prakash named HomeLane and BookMyShow; Cult.fit filed a draft prospectus in July 2026; Inc42 lists Zetwerk and Moglix as IPO-ready.
Source log
TechCrunch: Accel closes oversubscribed US$550M India fund within weeks
Inc42: Accel closes ninth India fund with US$550 Mn corpus
Entrepreneur India: Accel closes oversubscribed USD 550 Mn India fund in weeks
DealStreetAsia: Accel raises US$550m for ninth India early-stage fund
Whalesbook: Accel launches US$700M India Fund IX
Accel: Our enduring commitment to investing at the earliest stages
TNW: Accel raised US$3.5bn; Europe now gets the same fund as the US
tech.eu: Accel raises enlarged US$800M early-stage fund
Dealroom: Accel raises US$3.5B across four new funds
Pulse 2.0: Accel raises US$3.5 billion to invest in emerging global AI start-ups
Private Equity Wire: Accel raises US$3.5bn across four funds
Techfundingnews: Accel raises US$3.5B across four funds
TNW: Accel US$5 billion fund, April 2026
PR Newswire: Accel closes US$155 million seed and early-stage fund for India
Private Equity International: Accel closes US$155m third India fund
TechCrunch: Accel India closes its newest fund with US$450 million (2016)
AVCJ: Accel closes fifth India VC fund at US$450m
TechCrunch: Accel announces new US$650 million fund to back Indian start-ups (2022)
TechCrunch: Accel closes US$650 million for new India fund (Jan 2025)
TechCrunch: Accel can raise billions for India, it is sticking to US$650 million
Entrepreneur India: Accel secures USD 650 Mn for eighth India fund
Accel: Announcing our VIII fund for India’s boldest founders
Outlook Business: Accel raises US$650 million for 8th India fund after IPO wins
Outlook Business: Accel promotes Rachit Parekh, Pratik Agarwal to partner
TechCrunch: Accel and Prosus team up to back early-stage Indian start-ups
TechCrunch: Google teams up with Accel to hunt for India’s next AI breakouts
Accel Atoms: AI cohort 2026 with Google
Inc42: Startup IPOs in 2025, Peak XV, Accel, Y Combinator mint hefty returns
Lapaas Voice: Accel India sells 1.3% Urban Company stake worth ₹272 crore
Angel One: Accel retains 7 percent stake in Urban Company post IPO
Inc42: Accel offloads ₹156 Cr stake in BlackBuck via block deal
Inc42: Amagi IPO, Premji Invest cashes out, Accel mints 3.3X
Venture Intelligence: Accel, Avataar sell Amagi shares worth ₹587.3 Cr
Kotak Neo: Cult.fit IPO, Accel portfolio companies public listings
TechCrunch: Accel backs Uber rival Rapido as Prosus boosts stake
Peak XV: Three new funds for exceptional founders in India, APAC and beyond
Entrepreneur APAC: Peak XV raises USD 1.3 Bn across new India and APAC funds
DealStreetAsia: Nexus Venture Partners closes Fund VIII at US$700m
Inc42: Nexus Venture Partners closes US$700 Mn fund for early-stage bets
IANS: India’s PE and VC fundraises more than double to US$21.2bn in Jan–June
YourStory: Indian start-ups raise US$6.9B in H1 2026
Inc42: Indian start-up funding slips 9% to US$5.2 Bn in H1 2026
Entrepreneur India: PE/VC investments in India reach USD 20.5 Bn
Accel: People page (partner portraits)
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|