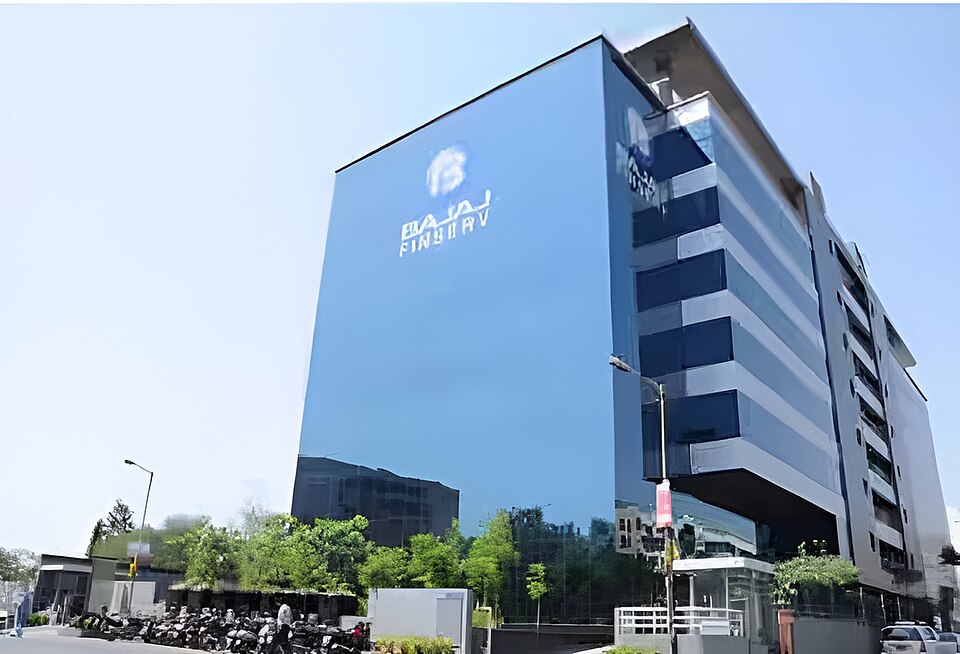
| MANAGER | Bajaj Alts, a wholly owned Bajaj Finserv subsidiary incorporated in 2025 · strategies across real estate, private equity and listed equities · group president for investments and MD and CEO: Lakshmi Iyer |
|---|
| FUND | Bajaj Alts Real Estate-Growth Fund I · initial close about ₹950 Cr (Rs 9.5 bn) reported 14–16 Oct 2026 |
| TARGET | ₹2,000 Cr (Rs 20 bn) including a greenshoe option |
| STRATEGY | Equity-led joint ventures with developers to build Grade A commercial office assets for corporates and global capability centres |
| INVESTORS | Family offices, institutional investors and high-net-worth individuals (unnamed) |
| NOT DISCLOSED | AUM, developer partners, locations, fees, first-close date, return target |
| THE ACCESS POINT
The fund has an initial close and is raising towards its ₹2,000 crore target. Family offices, institutions and HNIs are named as investors. AIF commitments start at ₹1 crore. |
|---|
Executive decision summary
| THE BOTTOM LINE | Bajaj Alts, the alternatives arm of Bajaj Finserv, reported in mid-October 2026 an initial close of about ₹950 crore for its maiden real estate fund, against a target of ₹2,000 crore including a greenshoe. The fund will invest equity alongside developers in Grade A office buildings aimed at corporates and global capability centres. The first close is 47.5% of the target (Rupeia calculation), and the manager has been in existence only since 2025, so there is no earlier fund or track record. What is available is a strong sponsor, a clear asset class and a named leader, Lakshmi Iyer. What is missing is nearly everything an investor would price: fees, return target, partners, cities and the first-close date. |
|---|
| WHICH INVESTOR | The fund fits a watch-list IF you want office-asset exposure through a large financial group's new alternatives arm.
Wait IF you need developer partners, locations, returns targets and fees, none of which have been disclosed. |
| COMFORT FIT | Bajaj Alts = a famous bank opening a new branch. The brand is known; the branch has no history.
Grade A office JVs = building the offices a tenant wants. Developers build, the fund provides equity, tenants such as global capability centres rent.
Equity-led = sharing the upside and the risk. Unlike Sundaram's real estate credit (Report 12), investors here are owners, not lenders.
47.5% raised = half-way there. The rest depends on how quickly Bajaj's network converts. |
| THE RUPEIA NUMBER | 47.5%. The first close of about ₹950 crore is under half of the ₹2,000 crore target (Rupeia calculation). |
1 CLAIM REGISTER: EVIDENCE GRADING
| Claim | Source | Grade | Rupeia assessment |
|---|
| Initial close of about Rs 9.5 bn (₹950 Cr) | Construction World (14–16 Oct 2026) | C | Reported |
| Target Rs 20 bn including greenshoe | Construction World | C | Single source |
| Strategy: Grade A offices via developer JVs; GCC and corporate tenants | Construction World | C | Stated |
| Bajaj Alts incorporated 2025; wholly owned by Bajaj Finserv | Construction World | C | Stated |
| Lakshmi Iyer: group president investments, MD and CEO | Construction World | C | Stated |
2 STRATEGY, PEERS AND MARKET CONTEXT
| Item | Detail |
|---|
| Assets | Grade A commercial office buildings built with developer joint-venture partners |
| Tenants | Corporates and global capability centres (GCCs) |
| Return type | Equity-led; no target return published |
| Other Bajaj Alts strategies | Private equity and listed equities; long-short and quant planned |
| Peer real estate funds (press headlines) | Reported |
|---|
| Motilal Oswal Alternates real estate fund | First close ₹1,250 Cr (Feb 2024) |
| Kotak Alts 14th real estate fund | US$1bn final close |
| Arnya real estate fund | First close US$45m |
| Sundaram Alternates RE Credit Fund V (Report 12) | ₹2,500 Cr final close; credit, not equity |
| RUPEIA READ
Bajaj Alts enters a field where larger managers have already reported real estate fund closes from ₹1,250 crore to US$1 billion. Its ₹950 crore first close is respectable for a manager in its first year, and its equity-in-office strategy is a different risk from Sundaram's secured lending. The brand is the edge; the missing disclosure is the gap. |
|---|
3 THE FUND SIZE LADDER
| Measure (Rupeia calculation) | Value |
|---|
| First close ₹950 Cr in US$ | ~US$98m at ₹96.5 |
| Target ₹2,000 Cr in US$ | ~US$207m |
| First close ÷ target | 47.5% |
| Versus Motilal Oswal real estate first close (₹1,250 Cr) | 76% |
| Target versus Kotak Alts' 14th fund (US$1bn ≈ ₹9,650 Cr) | 21% |
| Illustrative deployment (assumed ticket, not published) | Projects |
|---|
| ₹100 Cr equity per office JV | 9–10 projects with the first close; 20 with the full target |
| ₹200 Cr equity per office JV | 4–5 projects with the first close; 10 with the full target |
| RUPEIA READ
At nearly half its target, Bajaj Alts has enough money for five to ten office projects. The unknowns that decide the outcome are the partners, cities and entry yields, none of which has been published. |
|---|
4 EQUITY OFFICES VERSUS REAL ESTATE CREDIT
| Feature | Bajaj Alts Growth Fund I (equity) | Sundaram RE Credit Funds (Report 12) |
|---|
| Position | Owner alongside developer | Senior secured lender |
| Return source | Rent and sale value | Contracted interest (18–21% on loans) |
| Published result | None; no target return | Net IRR 12.5–16.5%; DPI 1.36x and 1.56x for Funds I and II |
| Main risk | Construction and leasing | Borrower default |
| RUPEIA READ
An equity fund carries development and leasing risk that a lender does not, so it has to promise more than the 12.5–16.5% net that Sundaram's senior-secured funds have delivered to be worth choosing. Bajaj Alts has not stated a target, which leaves that comparison open. |
|---|
5 THE PLATFORM BEHIND THE FUND
| Item | Published detail |
|---|
| Legal name | Bajaj Alternate Investment Management (Bajaj Alts), a wholly owned Bajaj Finserv subsidiary |
| Leader | Lakshmi Iyer, group president for investments and MD and CEO; earlier CEO for investments and strategy at Kotak Alternate Asset Managers |
| Sept 2025 plan | Raise ₹1,500–2,000 Cr for each of its first funds, up to ₹4,000 Cr in total, for early-stage venture and commercial real estate |
| Feb 2026 plan | Up to US$1bn platform across private equity, liquid alternatives, listed equity and real estate; ₹1,500–2,000 Cr per strategy over 18–24 months |
| Other strategies | AI-focused fund planned to invest ₹400–450 Cr; SEBI portfolio-management licence approved |
| RUPEIA CALCULATION
US$1 billion is about ₹9,650 crore. The ₹950 crore first close is about 10% of that platform ambition, and the full ₹2,000 crore real estate target is about 21%. The platform number is a multi-year, multi-strategy goal, not a target for this fund. |
|---|
6 WHY OFFICES, AND WHY NOW
| Factor | What the record shows |
|---|
| Tenant demand | Fund aims at corporates and global capability centres |
| Sponsor distribution | Bajaj Finserv's customer and wealth network supplies LPs |
| Manager experience | CEO has run an alternatives business at Kotak |
| Competition | Kotak Alts closed a US$1bn 14th real estate fund; Motilal Oswal had a ₹1,250 Cr first close |
| RUPEIA READ
Bajaj Alts has an experienced chief and a large distribution channel, which explains a ₹950 crore first close in the manager's first year. It has not shown a track record, and no partner or city has been named. |
|---|
7 THE MANAGER AND ITS HEAD OFFICE
| Calculation (Rupeia) | Result |
|---|
| Initial close ÷ ₹2,000 Cr target | ₹950 Cr ÷ ₹2,000 Cr = 47.5% |
| Amount still to raise to reach the target | ₹2,000 Cr − ₹950 Cr = ₹1,050 Cr |
| RUPEIA READ
Less than half of the target had been raised at the initial close, and the target includes the greenshoe. The manager was incorporated in 2025, so the fund has no earlier fund track record to refer to; the balance sheet and name of the parent group are what investors rely on. |
|---|
8 KEY TERMS USED IN THIS REPORT
The terms below are used throughout this report. The first table gives the general meaning; the second shows what each term refers to in this transaction.
| Term | Meaning |
|---|
| First close | The date a fund first accepts investor money and may start investing; later closes add more investors until the final close. |
| Final close | The last date investors can join; the fund's size is fixed from here. |
| Greenshoe | An agreed amount above the base target that the manager may accept if demand is strong. |
| DPI | Distributions to paid-in capital: cash returned divided by cash invested. 1.0x means investors have their money back. |
| IRR | Annualised return that accounts for when cash went in and came out. Gross is before fees and carry; net is after. |
| Category I and II AIF | SEBI classes for alternative investment funds. Minimum commitment is ₹1 crore per investor. |
| Term in this report | What it refers to here |
|---|
| First close | About ₹950 Cr, October 2026 |
| Greenshoe | Included in the ₹2,000 Cr target |
| Grade A office | Modern commercial building leased to corporates |
| Global capability centre | An offshore corporate unit, a target tenant |
9 RISKS, SCENARIOS AND FINAL VIEW
| Risk | Evidence | Severity | Kill condition |
|---|
| No track record | Manager incorporated 2025 | HIGH | Early project delays |
| Development risk | JVs build new assets | MEDIUM | Cost or timeline overruns |
| Office demand | Depends on GCC and corporate leasing | MEDIUM | Weak leasing |
| Disclosure | Fees, returns and partners unpublished | MEDIUM | Terms unfavourable to LPs |
| Fundraising | 47.5% of target at first close | LOW | Final close well below ₹2,000 Cr |
| Scenario | What happens | Outcome |
|---|
| Bull | Quick close at target; early projects pre-leased to GCCs | Strong Fund II case |
| Base | Final close ₹1,400–1,800 Cr | Moderate returns |
| Bear | Slow close; leasing delays | Small fund; weak returns |
Bajaj Alts has a name and a clear asset class but no record. Rupeia's view: wait for the partner names, the first assets and a return target before judging; the sponsor lowers the risk of a collapse but says little about returns.
Frequently asked questions
What is Bajaj Alts Real Estate Growth Fund I?
It is the maiden real estate fund of Bajaj Alts, the alternatives arm of Bajaj Finserv, investing in Grade A commercial offices through developer joint ventures.
How much has it raised?
About ₹950 crore (Rs 9.5 billion) at its initial close in October 2026, against a ₹2,000 crore target including a greenshoe.
Who leads Bajaj Alts?
Lakshmi Iyer is group president for investments and MD and CEO.
Who invested?
Family offices, institutional investors and high-net-worth individuals; none are named.
What returns does it target?
No return target has been published.
What kind of properties will it buy?
Grade A office buildings developed with partners, aimed at corporates and global capability centres.
Source log
Construction World: Bajaj Alts raises Rs 9.5 bn in first close of real estate fund
Business Standard: Motilal Oswal secures ₹1,250 Cr in first close for AIF real estate fund
DealStreetAsia: Kotak Alts completes US$1b final close for 14th real estate fund
DealStreetAsia: Arnya real estate fund hits first close at US$45m
The Realty Today: Sundaram Alternates ₹2,500 crore final close for fifth real estate credit fund
Geosquare: Bajaj Finserv expands into alternative investments with VC and real estate funds
| DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|