JSW One Platforms: ₹3,054 Cr = ₹1,300 Cr fresh + ₹1,754 Cr offer for
November 7, 2026 · By Somyesh
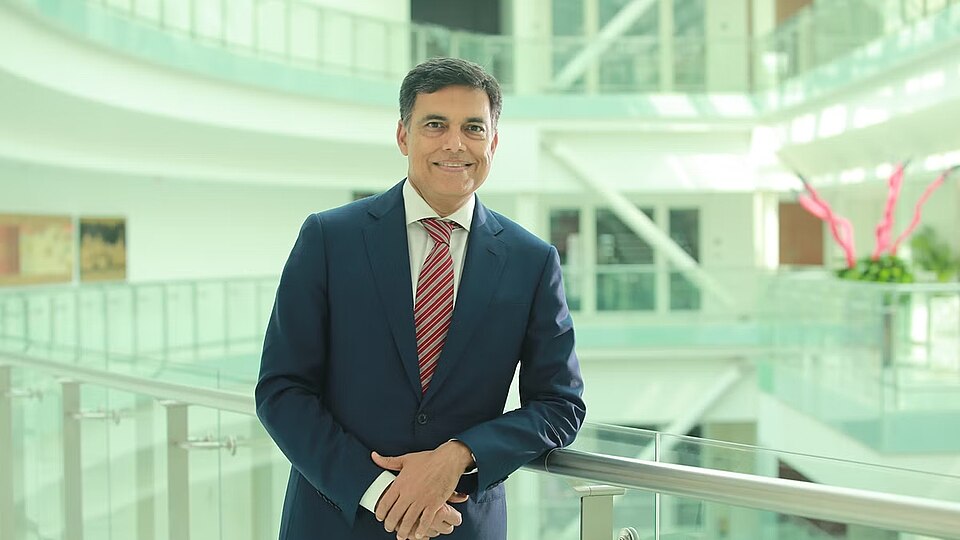
Sajjan Jindal, chairman of the JSW Group, which founded JSW One in 2020 · Image: JSW Group via Wikimedia Commons, CC BY-SA 2.0
Independent report content
COMPANY
JSW One Platforms Limited, the JSW Group's B2B digital marketplace for construction and building materials; JSW Steel and JSW Cement held 78.60% before the issue
ISSUE
Up to ₹3,054.01 Cr: fresh issue ₹1,300 Cr + OFS up to ₹1,754.01 Cr · price band not set · pre-IPO placement up to ₹260 Cr possible
SELLERS
JSW Steel up to ₹811 Cr · JSW Cement up to ₹123 Cr · Mitsui & Co. up to ₹820.01 Cr
USE OF FRESH ISSUE
₹500 Cr into JSW One Finance · ₹350 Cr technology and platform · ₹125 Cr marketing for JSW One Distribution · balance general corporate purposes
THE ACCESS POINT
The DRHP was filed on 24 September 2026 and is subject to regulatory approvals; none had been reported in the sources read. No price band exists yet. This note analyses published information and is not a recommendation to subscribe.
Executive decision summary
THE BOTTOM LINE
JSW One Platforms filed on 24 September 2026 for a ₹3,054 crore IPO, of which ₹1,300 crore is new money and ₹1,754 crore is shares sold by JSW Steel, JSW Cement and Japan's Mitsui & Co. FY26 revenue rose 44.9% to ₹5,743 crore and gross merchandise value to ₹18,597 crore, while the restated loss halved to ₹106 crore, and the June 2026 quarter showed a small profit of ₹14 crore. The weakness is concentration: steel products were 98.79% of net merchandise value and JSW Group supplied 85.70% of it, so this is closer to the JSW Group's own sales channel than an open marketplace. Only ₹14 crore of FY26 revenue came from financial services, which is where ₹500 crore of the fresh money is going.
WHICH INVESTOR
JSW One fits a watch-list IF you want listed exposure to construction-materials digitisation with a group sponsor behind it.
Wait IF you need a diversified marketplace: nearly all sales are steel, and most steel comes from the parent group.
COMFORT FIT
JSW One = the JSW Group's online storefront. Builders and dealers order steel, cement and paints through an app, delivered by the group and a few outside brands.
GMV vs revenue = shelf price vs shop income. The company books most sales as its own revenue (₹5,743 crore of ₹18,597 crore GMV), so it carries inventory-like risk, not just a commission.
JSW One Finance = the buy-now-pay-later arm. It received ₹500 crore of the fresh money but earned only ₹14 crore in FY26.
Zetwerk (Report 22) = another platform that routes work to third parties at thin margins.
THE RUPEIA NUMBER
85.70%. The share of JSW One's net merchandise value supplied by JSW Group companies in FY26, with steel products 98.79% of the total (Outlook Money, from the DRHP).
1 CLAIM REGISTER: EVIDENCE GRADING
A = regulator or exchange filing. B = company filing summarised by press. C = independent press. D = third-party summary.
FY26 revenue ₹5,743.39 Cr; loss ₹106.49 Cr; FY25 loss ₹217.02 Cr
Kotak Neo; Outlook Money; Inc42
C
Established
GMV ₹18,596.91 Cr (FY26), ₹12,564.84 Cr (FY25)
Kotak Neo; Nifty Trader
C
Established
Steel 98.79% of NMV; JSW Group supply 85.70%
Outlook Money
C
Established
JSW Steel and JSW Cement held 78.60% pre-issue
Outlook Money
C
Established
2 ISSUE STRUCTURE AND USE OF PROCEEDS
Item
Detail
Fresh issue
Up to ₹1,300 Cr (the company receives this)
Offer for sale
Up to ₹1,754.01 Cr: JSW Steel ₹811 Cr; JSW Cement ₹123 Cr; Mitsui & Co. ₹820.01 Cr
Pre-IPO placement
Up to ₹260 Cr, which would reduce the fresh issue
Lead managers
JM Financial, Kotak Mahindra Capital, ICICI Securities, SBI Capital Markets, PL Capital Markets
Registrar
KFin Technologies
Object of the fresh issue
₹ crore
Capital for JSW One Finance
500
Technology and platform development
350
Marketing and brand-building for JSW One Distribution
125
General corporate purposes (balance)
325 (before any pre-IPO placement)
RUPEIA READ
The OFS is 57% of the issue and all of it goes to JSW Group companies and Mitsui, not to the platform. JSW Steel and JSW Cement are therefore taking money out of a business they built inside the group, while the company keeps ₹1,300 crore, 38% of which funds a lending arm that earned ₹14 crore in FY26.
3 FINANCIALS AND OPERATING METRICS
₹ crore
FY25
FY26
Change
Revenue from operations
3,962.81
5,743.39
+44.9%
Gross merchandise value (GMV)
12,564.84
18,596.91
+48.0%
Restated net loss
217.02
106.49
Loss halved (–50.9%)
Financial services revenue
2.3
14.2
0.2% of revenue
Sales of goods
5,619.6
+45.5%
Services revenue
109.6
Quarter to 30 Jun 2026
Figure
GMV
₹5,949.73 Cr
Revenue
₹1,642.45 Cr
Profit after tax
₹14.21 Cr
Registered customers
95,611
Sellers; brands; pin codes
1,713; 165; 6,963
Logistics partners
81
RUPEIA CALCULATION
Revenue as a share of GMV is 30.9% in FY26 (5,743 ÷ 18,597), far above the single-digit commissions of a pure marketplace, which confirms that most sales are booked as the company's own. Net loss fell from 5.5% to 1.9% of revenue. At the June 2026 quarter's run-rate, revenue annualises to about ₹6,570 crore and GMV to about ₹23,800 crore. EBITDA is not shown on the pages read.
4 WHO GETS THE MONEY: SELLERS AND THE COMPANY
Component
₹ crore
Share of total issue (₹3,054 Cr)
Fresh issue (to the company)
1,300
42.6%
JSW Steel OFS
811
26.6% (46.2% of the OFS)
JSW Cement OFS
123
4.0% (7.0% of the OFS)
Mitsui & Co. OFS
820.01
26.9% (46.8% of the OFS)
Use of the ₹1,300 Cr fresh issue
₹ crore
Share
JSW One Finance capital
500
38.5%
Technology and platform
350
26.9%
JSW One Distribution marketing
125
9.6%
General corporate purposes
325
25.0%
RUPEIA READ
Group companies and Mitsui together take 57% of the issue. Mitsui's ₹820 crore is almost equal to JSW Steel's ₹811 crore, so the foreign partner is selling as much as the largest group seller.
5 GMV, REVENUE AND CUSTOMER DEPTH
Measure (Rupeia calculation)
FY25
FY26
Revenue ÷ GMV
31.5%
30.9%
Net loss ÷ revenue
5.5%
1.9%
GMV growth
+48.0%
Revenue growth
+44.9%
Non-steel share of net merchandise value
1.2% (steel was 98.79%)
Non-JSW-Group share of net merchandise value
14.3% (group supply 85.70%)
Depth measure (30 Jun 2026)
Figure
FY26 GMV per unit
Registered customers
95,611
₹19.5 lakh each (if all active)
Sellers
1,713
₹10.9 Cr each
Brands
165
₹113 Cr each
RUPEIA CALCULATION
Revenue grew a little slower than GMV, so the share of each sale kept as revenue slipped from 31.5% to 30.9%. The loss shrank faster than revenue grew, which means cost control, not pricing, drove the improvement. More than 98% of sales being steel and about 86% coming from JSW Group means the marketplace claim rests on the other 1% and 14%.
6 ORIGINS, BACKERS AND THE CREDIT BOOK
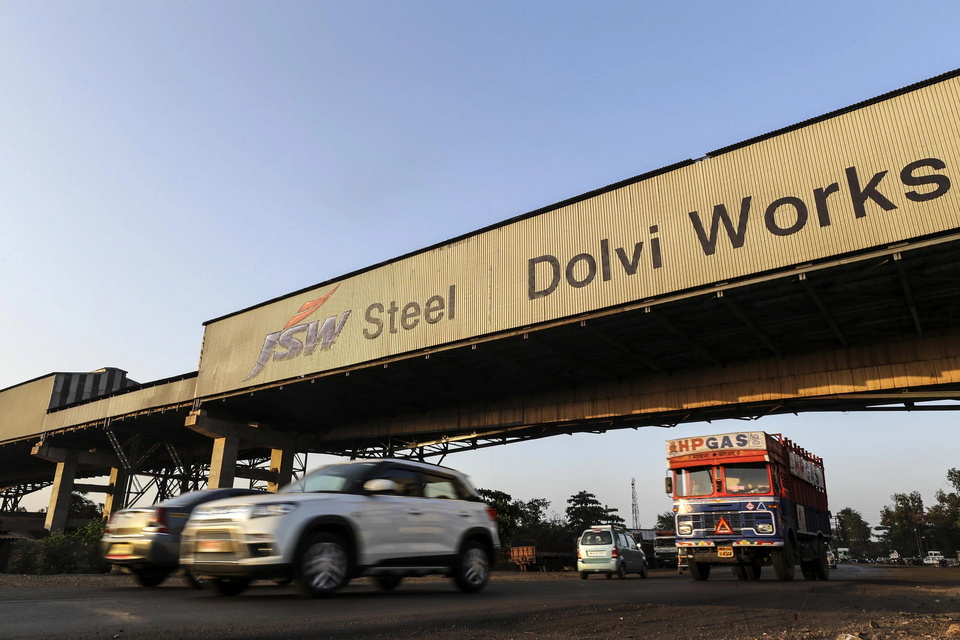
JSW Steel Dolvi Works in Maharashtra; JSW Steel is a selling shareholder in the IPO · Image: JSW Group via Wikimedia Commons, CC BY-SA 2.0
Fact
Published detail
Founded
2020 by the JSW Group, to digitise procurement for small and medium businesses
Focus
Steel, cement and paints for small manufacturers and builders; customers with annual turnover of ₹25 Cr to ₹2,500 Cr
Mitsui & Co (Apr 2023)
₹205 Cr (reported as about US$25m) at a valuation above ₹2,750 Cr
Unicorn round
₹340 Cr at a US$1bn valuation, led by Principal Asset Management and OneUp with JSW Steel
Credit
About 30% of GMV was sold on credit in a 2023 interview; the NBFC arm had applied for a licence
SBI
Reported to have joined a ₹575 Cr funding round for the lending arm
Leadership
Gaurav Sachdeva, CEO in 2023, is now joint managing director and chief executive
Timeline stated
Break-even and an IPO by FY28; the 2023 plan said FY27
Calculation (Rupeia)
Result
Mitsui cheque ÷ valuation
₹205 Cr ÷ ₹2,750 Cr ≈ 7.5% (valuation is stated as "above", so this is a ceiling)
Share of FY26 GMV (₹18,597 Cr) sold on credit, if 30% still held
≈ ₹5,580 Cr (the 30% is a 2023 figure, not an FY26 one)
IPO timeline slip
FY27 (2023 plan) to FY28: one year
RUPEIA READ
The marketplace is the front door and credit is where the capital goes. A 2023 credit share cannot be carried forward to FY26 without a current figure, which the DRHP will show. The shift of break-even from FY27 to FY28 is the clearest published signal that the path to profit has taken longer than first planned.
7 KEY TERMS USED IN THIS REPORT
The terms below are used throughout this report. The first table gives the general meaning; the second shows what each term refers to in this transaction.
Term
Meaning
DRHP / UDRHP
Draft red herring prospectus, filed with SEBI before an IPO; an updated draft (UDRHP) replaces it after changes.
Fresh issue vs offer for sale (OFS)
A fresh issue creates new shares and the company gets the money. In an OFS existing holders sell and the company gets nothing.
Price band and anchor book
The range in which bids are accepted; anchors are large institutions allotted shares a day before the issue opens.
Pre-IPO placement
A private sale of shares shortly before the IPO that reduces the fresh issue by the same amount.
Lock-in
A period during which certain holders may not sell after listing; anchor shares are released in two steps.
Restated financials
Past accounts re-presented on a consistent basis for the prospectus.
Term in this report
What it refers to here
DRHP
Filed 24 Sep 2026; no SEBI approval reported
GMV
₹18,597 Cr in FY26
OFS
JSW Steel, JSW Cement and Mitsui, ₹1,754 Cr
Pre-IPO placement
Up to ₹260 Cr
8 RISK ANALYSIS, SCENARIOS AND FINAL VIEW
Risk
Evidence
Severity
Kill condition
Group dependence
85.70% of NMV from JSW Group; steel 98.79%
HIGH
Group changes channel strategy
Steel price cycle
Revenue tracks steel prices
MEDIUM
Prolonged steel downturn
Lending-arm risk
₹500 Cr into JSW One Finance; ₹14 Cr FY26 revenue
MEDIUM
Credit losses
Marketplace claim
165 brands but narrow product mix
MEDIUM
No diversification
Related-party pricing
Parent supplies most goods and sells shares
MEDIUM
Adverse governance findings
Losses
Loss ₹106.49 Cr in FY26
MEDIUM
Loss persists after IPO
Scenario
What happens
Outcome
Bull
Non-steel categories and third-party brands grow; finance arm scales; profit continues
Re-rating as a platform
Base
Growth 30–40%; steel stays dominant
Priced as a group distribution arm
Bear
Steel cycle turns; group channel mix changes
Weak listing
JSW One has grown quickly and nearly halved its loss, and its latest quarter was profitable. But the numbers also show a platform that is mostly one group's steel, sold to the group's customers, with the group and a Japanese partner taking more than half of the IPO as sellers. Rupeia's view: the investment question is whether JSW One becomes a marketplace in the strict sense, with outside brands and non-steel categories, which the pages read show only at an early stage.
Frequently asked questions
What is the JSW One Platforms IPO size?
Up to ₹3,054.01 crore: a fresh issue of ₹1,300 crore plus an offer for sale of up to ₹1,754.01 crore.
Who is selling shares in the IPO?
JSW Steel (up to ₹811 crore), JSW Cement (up to ₹123 crore) and Mitsui & Co. (up to ₹820.01 crore).
What will JSW One do with the money?
₹500 crore into JSW One Finance, ₹350 crore on technology, ₹125 crore on marketing for JSW One Distribution and the balance for general purposes.
What are JSW One's FY26 financials?
Revenue ₹5,743.39 crore (up 44.9%), GMV ₹18,596.91 crore and a restated loss of ₹106.49 crore, against ₹217.02 crore in FY25.
Is JSW One profitable?
FY26 was a loss, but the quarter to June 2026 showed a profit after tax of ₹14.21 crore.
How dependent is JSW One on the JSW Group?
JSW Group companies supplied 85.70% of net merchandise value and steel products were 98.79% of it in FY26.
When will the JSW One IPO open?
No dates or price band had been announced; the DRHP was filed on 24 September 2026 and awaits regulatory approval.
Source log
Kotak Neo: JSW One Platforms files IPO papers for ₹3,054 crore issue
Inc42: IPO-bound JSW One's FY26 loss narrows 51% to ₹107 Cr, revenue jumps 45%
Nifty Trader: JSW One Platforms IPO, revenue up 45%, where the ₹1,300 crore fresh issue will go
Outlook Money: JSW One Platforms files DRHP for ₹3,054 crore issue
Groww: JSW One Platforms files DRHP with SEBI
Free Press Journal: JSW One Platforms eyes ₹3,054 crore IPO
Chittorgarh: JSW One Platform IPO details
Bar & Bench: Cyril Amarchand Mangaldas, Trilegal, Khaitan act on JSW One proposed IPO
DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing.