Advent International and Yatharth Hospitals: Equity and warrants at
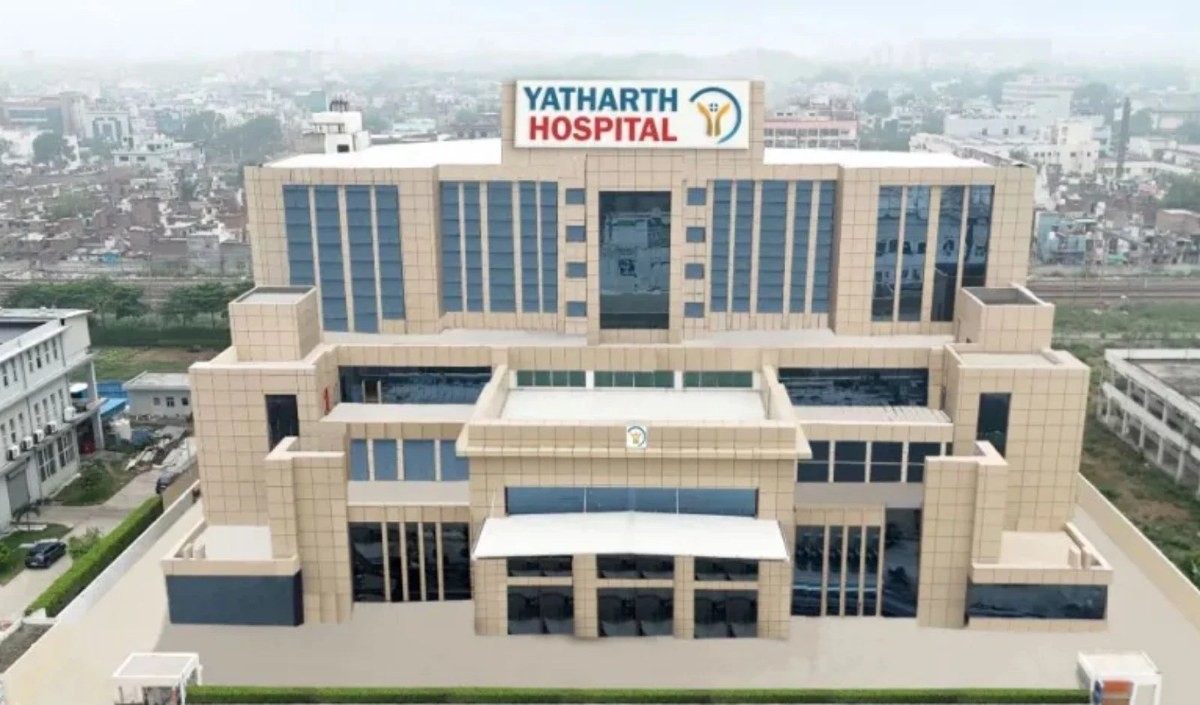
Yatharth Hospital · Image: Franchise India
Independent report content
| ISSUER | Yatharth Hospital & Trauma Care Services Limited (NSE: YATHARTH, BSE: 543950), Delhi NCR hospital chain · IPO July 2023 · promoters Ajay Kumar Tyagi and family and Kapil Kumar hold 55.80% (June 2026) |
|---|---|
| INVESTOR | Advent International through Rasmalai Limited (Cyprus) · Advent AUM above US$109bn (30 June 2026), 55+ healthcare investments |
| DEAL | ₹3,150 Cr (about US$328.5m) primary capital · 13,026,516 equity shares (₹1,283.33 Cr) plus 18,947,664 warrants (₹1,866.67 Cr), all at ₹985.17 |
| PAYMENT | Warrants: 25% upfront (₹246.29), 75% (₹738.88) on exercise · Rupeia: about ₹1,750 Cr at signing, about ₹1,400 Cr later |
| STAKE | 24.87% fully diluted (24.9% rounded) after all warrants convert · Tyagi family stays largest shareholder |
| IMPLIED MULTIPLES | Pre-money enterprise value about ₹9,400 Cr: about 26.7x LTM EBITDA, 6.3x LTM revenue, 52.6x LTM profit (Rupeia calculations) |
| STATUS AT 7 NOV 2026 | Announced; shareholder and regulatory approvals required; EGM reported for 15 October 2026; completion not confirmed in sources read |
| THE ACCESS POINT Yatharth Hospital is listed on NSE and BSE, so its shares trade openly. Advent is paying ₹985.17 a share through a preferential allotment, which individuals cannot join. The 3 November 2026 NSE close of ₹981.85 is within 0.3% of that price. |
|---|
Executive decision summary
| THE BOTTOM LINE | Advent has agreed to put ₹3,150 crore into Yatharth Hospitals for a 24.87% stake, a large outside investment in a listed Delhi NCR hospital chain that the Tyagi family still controls. The money is not all in the bank on day one: about ₹1,750 crore arrives through equity and the upfront quarter of the warrants, and about ₹1,400 crore only when Advent exercises the rest. The price of ₹985.17 values the company at roughly ₹9,400 crore of enterprise value before the money, or about 27 times trailing EBITDA, in the middle of listed hospital peers. The Tyagi family stays the largest shareholder and no control changes hands. The bet is that Yatharth can grow from about 2,555 beds to more than 5,000 in three years while holding EBITDA margins near 24–25%, and that the newer hospitals scale as Faridabad and Agra have. |
|---|---|
| WHICH INVESTOR | The deal fits you IF you want a listed, profitable, fast-growing hospital chain (Q2 FY27 revenue up 52%) whose largest outside investor is a global private-equity firm paying the market price, and you accept about 27x trailing EBITDA. Wait IF you need the shareholder vote, regulatory approvals and warrant exercise timetable confirmed first, or if you are concerned about the rise in depreciation (up 75%) and finance cost (₹8.3 crore against ₹0.3 crore a year ago). |
| COMFORT FIT | Equity plus warrants = a down payment and a layaway plan. Advent pays for part now and keeps the right, not the duty, to pay the balance at the same price later. A 24.87% stake = just under the line. Indian takeover rules trigger an open offer at 25%; Advent stays below it, which also explains why the Tyagi family keeps the wheel. The Aster talks in August = the other bidder at the door. Reports said Advent and Aster were both negotiating for control; the outcome was a minority deal at the market price. Yatharth = a franchise of new wings. Four newer hospitals now supply 28% of revenue, and the older ones are growing 24% a year as well. |
| THE RUPEIA NUMBER | ₹985.17. The price per share Advent will pay, about 3.3 times the ₹300 IPO price of July 2023 and within 0.3% of the 3 November 2026 close. |
1 CLAIM REGISTER: EVIDENCE GRADING
A = government, regulator, exchange or statutory filing. B = company or manager release or website. C = independent press. D = third-party database, blog or aggregator.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| ₹3,150 Cr primary investment for 24.9% (24.87% fully diluted), announced 17 Sep 2026 | Advent press release; exchange filing as reported by Sahi, Digital Health News, Multibagg | B | Established |
| 13,026,516 equity shares and 18,947,664 warrants at ₹985.17; warrants 25% upfront | Exchange filing as reported by Sahi and Multibagg | A | Established; one outlet gives 31,974,177 shares, three fewer than the sum |
| Investor vehicle Rasmalai Limited, Cyprus | Sahi; Multibagg | C | Reported; Advent release names only Advent |
| Tyagi family remains largest shareholder; promoters 55.80% (June 2026) | Advent release; Business Today; Kotak Neo | B | Established |
| Authorised capital ₹115 Cr to ₹150 Cr; EGM on 15 Oct 2026 | Sahi; Multibagg; Entrepreneur India (date) | C | Date from one outlet only |
| FY26 revenue ₹1,207.2 Cr, EBITDA ₹292.1 Cr, PAT ₹170.3 Cr | Company results as reported by Whalesbook and Quartr | B | Established |
| Q2 FY27 revenue ₹431.4 Cr, EBITDA ₹102 Cr, PAT ₹48.5 Cr, occupancy 72% | Investor presentation as reported by Multibagg, Angel One | B | Established |
| Aster DM and Advent in talks for control (28 Aug 2026); Yatharth denied being party | Kotak Neo; Angel One citing press reports | C | Reported; denial undated |
| Share price record ₹1,065–1,067 (17 Sep) and ₹1,183.15 (18 Sep) | Business Today; Reuters via DealStreetAsia | C | Sources differ on the 17 Sep high |
| Net debt or net cash of ₹116 Cr at 31 Mar 2026 | Whalesbook (net debt); Quartr and Sahi (net cash) | C | Conflict preserved |
2 THE DEAL IN ONE PAGE
| Term | Detail | Source |
|---|---|---|
| Issuer | Yatharth Hospital & Trauma Care Services Limited; NSE: YATHARTH, BSE: 543950 | Advent release |
| Investor | Advent International, via Rasmalai Limited (Cyprus-incorporated) | Sahi; Multibagg |
| Instrument | Preferential issue of equity shares and convertible share warrants | Exchange filing via Multibagg |
| Equity shares | Up to 13,026,516 at ₹985.17 = ₹1,283.33 Cr | Sahi; Multibagg |
| Warrants | Up to 18,947,664 at ₹985.17 = ₹1,866.67 Cr; 25% (₹246.29) upfront; ₹738.88 on exercise | Multibagg |
| Total | ₹3,150 Cr, about US$328.5m (Reuters); implied rate about ₹95.9 per US$ | Advent release; DealStreetAsia |
| Stake | 24.87% post-issue, fully diluted including granted ESOPs | Sahi; Multibagg |
| Authorised capital | To rise from ₹115 Cr to ₹150 Cr | Sahi; Multibagg |
| Governance | Non-executive board representation for Advent | Omnicuris |
| Approvals | Shareholders (EGM) and customary regulatory approvals | Sahi; Multibagg; Advent release |
| Use of funds | Network expansion; more than 5,000 beds in three years; Gurugram 250-bed hospital | Sahi |
Yatharth Tyagi, Whole-time Director, said in the Advent release that the investment "marks a pivotal milestone in our journey". Pankaj Patwari, Managing Director at Advent, said: "We are pleased to partner with the Yatharth family". Atin Jain, Director at Advent, also spoke of partnering with the management team. Sources read do not name banks or law firms, a lock-in period, the warrant exercise window, or the SEBI pricing basis for the preferential issue.
3 WHY A PREFERENTIAL ISSUE: PRIMARY CAPITAL VERSUS A CONTROL SALE
The Advent investment is a primary transaction: Yatharth issues new shares and warrants and receives the money. No promoter sells a share. That separates it from the transaction the August press reports described, in which Advent or Aster would have bought control from the Tyagi family. In a control sale the money goes to the sellers and the takeover code requires an open offer to public shareholders, which Kotak Neo and Angel One put at a further 26%.
| Feature | Preferential issue (this deal) | Control purchase (reported in August) |
|---|---|---|
| Who receives the money | The company, for expansion | The selling promoters |
| Effect on share count | Rises by about 33% once warrants convert | No change |
| Promoter holding | Falls from 55.80% to roughly 42% fully diluted (Rupeia estimate) | Falls sharply or ends |
| Open offer to public | Not described; stake kept below 25% | Further 26% reported as mandatory |
| Board | Non-executive seat for Advent (Omnicuris) | Control of the board |
| Company cash | Up by ₹1,750 Cr at allotment | Unchanged |
| RUPEIA READ For the Tyagi family the preferential route trades dilution for continuity: they keep operating control and the company gets the capital, instead of the family receiving cash and handing over the business. For public shareholders it adds a well-funded growth plan and a new top-tier holder, at the cost of a one-third larger share count. The August reports suggest control sale was at least discussed by third parties; Yatharth denied being party to such talks. |
|---|
4 WHEN THE MONEY ARRIVES: A CASH-FLOW SCHEDULE
The headline ₹3,150 crore is the sum of two instruments with different payment dates. Rupeia computed the split from the published per-share amounts.
| Component | Calculation | Amount (₹ crore) | When |
|---|---|---|---|
| Equity shares | 13,026,516 × ₹985.17 | 1,283.33 | On allotment after approvals |
| Warrants, upfront 25% | 18,947,664 × ₹246.29 | 466.67 | On allotment |
| Cash at signing, total | 1,283.33 + 466.67 | 1,750.00 | On allotment |
| Warrants, balance 75% | 18,947,664 × ₹738.88 | 1,400.00 | On exercise; window not stated |
| Total | 1,750.00 + 1,400.00 | 3,150.00 |
| RUPEIA CALCULATION Exactly 55.6% of the headline (1,750 / 3,150) arrives on allotment and 44.4% (1,400 / 3,150) later. Against Yatharth's Q2 FY27 cash and bank balance of about ₹429 crore, the upfront ₹1,750 crore is about 4.1 times existing cash. The deferred ₹1,400 crore is Advent's option: under the usual terms of Indian warrant issues, the upfront amount is lost if the warrants lapse, so Advent will exercise only if the shares merit the same ₹985.17. The company cannot treat the second half as certain capital. |
|---|
5 WHO ADVENT IS
Advent International had assets under management above US$109 billion at 30 June 2026 and says it has made more than 55 healthcare investments worldwide. In India it has been mainly active in pharmaceuticals, with holdings reported in Bharat Serums and Vaccines and Cohance Lifesciences. Digital Health News says Advent is led in India by Shweta Jalan. Its hospital history in India is thin: Kotak Neo describes CARE Hospitals in 2012 as its only previous hospital investment, and Digital Health News says it exited in 2016 by selling to the UAE-based Abraaj Group. In 2024 it made a ₹2,475 crore equity investment in Apollo 24|7, the digital health business of Apollo Hospitals.
| Advent India healthcare transaction | Year | Published detail | Source |
|---|---|---|---|
| CARE Hospitals | 2012 | Investment; exit in 2016 to Abraaj Group (Digital Health News); Blackstone later took control in 2023 (PipelineRoad) | Kotak Neo; Digital Health News; PipelineRoad |
| Apollo 24|7 | 2024 | ₹2,475 Cr equity investment | Digital Health News |
| Bharat Serums and Vaccines; Cohance Lifesciences | n/a | Other Indian holdings named | Omnicuris |
| Yatharth Hospitals | 2026 | ₹3,150 Cr for 24.87% | Advent release |
| RUPEIA READ Advent is not new to Indian healthcare but is new to running hospital capacity in India for the second time. Its first hospital deal ended with a sale in four years. The Yatharth structure, a minority stake with warrants and board representation but no control, is a different design from a majority buy-out, and suits an investor who wants growth exposure and a defined exit route through the stock market. |
|---|
6 COMPANY OVERVIEW: FROM NOIDA EXTENSION TO NINE HOSPITALS
Yatharth Hospital & Trauma Care Services was founded in 2008 according to PipelineRoad, citing Private Equity Wire, and now runs nine multi-speciality hospitals with about 2,800 operational beds and announced capacity of about 3,250 beds (Advent release and Reuters). Digital Health News lists the locations as Noida, Greater Noida, Noida Extension, Greater Faridabad, Model Town in New Delhi, Faridabad, Jhansi-Orchha in Madhya Pradesh and Agra, with a 250-bed Gurugram hospital planned. Multibagg's Q2 FY27 coverage gives total bed capacity of 2,555 and 1,820 operational census beds, so bed counts depend on definition (see below).
| Hospital or site | Published detail | Source |
|---|---|---|
| Noida Extension | 26% of Q2 FY27 revenue | Multibagg |
| Greater Noida | 23% of Q2 FY27 revenue | Multibagg |
| Noida | 16% of Q2 FY27 revenue | Multibagg |
| Faridabad Sector-20 | 400 beds; ₹40 Cr in Q2 FY27 (9%); ARPOB about ₹40,000; EBITDA-positive | Multibagg |
| Model Town, New Delhi | 300 beds; ₹26 Cr (6%); ARPOB about ₹50,000; EBITDA breakeven expected H2 FY27 | Multibagg |
| Agra | 250 beds; ₹20 Cr (5%); ARPOB about ₹33,000; EBITDA-positive | Multibagg |
| Jhansi-Orchha | 305 beds acquired by 2023; loss-making in FY23 per IPO coverage | 5paisa |
| Gurugram Sector 40 | 250 beds under construction; 100% stake bought for ₹100 Cr; opening April 2027 to H1 FY28 | Multibagg; Whalesbook; Sahi |
Promoters Ajay Kumar Tyagi and family, with Kapil Kumar, held 55.80% in June 2026. Yatharth Tyagi is Whole-time Director. Employees number about 7,500 (Multiples).
7 TIMELINE: 2008–2026
| Date | Milestone |
|---|---|
| 2008 | Company founded (PipelineRoad citing Private Equity Wire) |
| 26–28 Jul 2023 | IPO at ₹285–300; ₹686 Cr issue; subscribed 37.28 times |
| 7 Aug 2023 | Listing on NSE |
| FY24 | Revenue ₹670.5 Cr (+29%) on FY23 ₹520.3 Cr |
| 25 May 2026 | Shares fall 7.18% to ₹801 after Q4 FY26 results |
| 3 Jun 2026 | FY26 revenue ₹1,207.2 Cr (+36%) reported |
| Jun 2026 | Gurugram Sector 40 hospital acquired for ₹100 Cr |
| 10 Aug 2026 | Maiden interim dividend ₹0.50 a share (₹4.82 Cr); ESOP Scheme 2026 of 250,000 shares |
| 28 Aug 2026 | Reports that Advent and Aster DM are negotiating for control; Yatharth denies being party to sale talks |
| 14 Sep 2026 | Board meeting intimation on growth plans and fundraising |
| 17 Sep 2026 | Definitive agreement with Advent; shares hit record high |
| 18 Sep 2026 | Shares up 20.38% over two days to ₹1,183.15 intraday |
| 15 Oct 2026 | EGM reported for the preferential issue (Entrepreneur India) |
| 3–4 Nov 2026 | Q2 FY27 results: revenue ₹431.4 Cr (+52%), EBITDA ₹102 Cr, PAT ₹48.5 Cr; shares close ₹981.85 on 3 Nov |
8 THE IPO AND WHAT THE LISTING PRICE TELLS US
Yatharth listed on 7 August 2023 after a ₹686 crore IPO between 26 and 28 July at a price band of ₹285–300. The issue combined a fresh issue of up to ₹490 crore and an offer for sale of up to 65.51 lakh shares (up to ₹196.55 crore) by promoter-group entities. Anchor investors put in ₹206 crore (68.65 lakh shares at ₹300 to 18 funds), including Goldman Sachs (Singapore), SBI Life, Max Life, Kotak Mahindra Life, ICICI Prudential, HDFC, Nippon India and Aditya Birla Sun Life funds. Lead managers were Intensive Fiscal Services, Ambit and IIFL Securities. The objects included debt repayment, capital expenditure at Noida and Greater Noida, and acquisitions.
| Day | QIB | NII | Retail | Total |
|---|---|---|---|---|
| 26 Jul 2023 | 0.26x | 1.84x | 1.33x | 1.14x |
| 27 Jul 2023 | 0.29x | 6.08x | 3.53x | 3.15x |
| 28 Jul 2023 | 86.37x | 38.62x | 8.65x | 37.28x |
| RUPEIA CALCULATION Advent's ₹985.17 is 3.28 times the IPO price of ₹300 (985.17 / 300). Over about 3.1 years from listing to the agreement that is roughly 46% a year (3.28^(1/3.12)). On the 5paisa figures the company had 1,405 beds at the IPO and now has 2,555 total, so beds grew about 1.8 times while revenue grew from ₹520 crore (FY23) to ₹1,207 crore (FY26), about 2.3 times, and the price rose 3.3 times. The market has paid for faster-than-bed growth in revenue per bed and for expansion still to come. |
|---|
9 FINANCIAL FORENSICS: FY23 TO Q2 FY27
| ₹ crore | Revenue | EBITDA | EBITDA margin | PAT | Source |
|---|---|---|---|---|---|
| FY23 | 520.3 | n/s | n/s | n/s | Whalesbook |
| FY24 | 670.5 (+29%) | n/s | n/s | n/s | Whalesbook |
| FY25 | About 888 (implied) | n/s | n/s | About 131 (implied) | Rupeia: 1,207.2 / 1.36; 170.3 / 1.30 |
| FY26 | 1,207.2 (+36%) | 292.1 (+30%) | 24.2% | 170.3 (+30%) | Whalesbook; Quartr |
| Q1 FY26 | 259.2 | 66.0 | 25.4% | 42.0 | Sahi |
| Q2 FY26 | 283.0 | 68.1 | 24.1% | 41.3 | Multibagg |
| Q3 FY26 | 321.4 | n/s | n/s | 43.1 | Business Today |
| Q4 FY26 | 341.6 (+47%) | 79.9 (+37%) | 23.4% | 44.7 (+15%) | Business Today; Quartr |
| Q1 FY27 | 392.7 (+51%) | 91.7 (+39%) | 23.3% | 45.4 (+8%) | Sahi |
| Q2 FY27 | 431.4 (+52%) | 102.0 (+50%) | 23.6% | 48.5 (+17%) | Multibagg; Angel One |
| H1 FY27 | 824.1 (+52%) | 193.7 (Rupeia sum) | 23.5% | 93.9 (+12.7%) | Multibagg |
FY25 figures are not stated in any source read and are inferred from the reported FY26 growth rates (n/s means not stated). Angel One reports Q2 FY27 total income of ₹436.44 crore, about ₹5 crore above revenue from operations, which Multibagg attributes to other income. Quarterly numbers do not sum exactly to the annual figures (revenue ₹1,205.2 crore against ₹1,207.2 crore).
| Balance sheet and cash | Figure | Source |
|---|---|---|
| Gross debt, 31 Mar 2026 | ₹230 Cr | Whalesbook |
| Net debt or net cash, 31 Mar 2026 | ₹116 Cr net debt (Whalesbook) or ₹116 Cr net cash (Quartr, Sahi) | Conflict |
| Cash and bank balances, Q2 FY27 | ₹428.90 Cr | Angel One |
| FY26 operating cash flow | ₹286.6 Cr (98% cash conversion) | Business Today |
| Debtor days, FY26 | 112; target 90–95 by FY27 | Whalesbook; Quartr |
| Q2 FY27 depreciation / finance cost | ₹33.1 Cr (+75%) / ₹8.3 Cr (vs ₹0.3 Cr) | Multibagg |
| RUPEIA READ Revenue is doubling in two years but profit is growing far slower: Q2 FY27 revenue rose 52% and PAT only 17%, because depreciation rose 75% and finance cost went from almost nothing to ₹8.3 crore as new hospitals were built and funded. EBITDA margin has drifted from 25.4% (Q1 FY26) to 23.6% because newer hospitals carry ramp-up costs; the company says ex-ramp-up margin is about 28%. The Advent money pays for more of the same growth, so the tension between revenue and profit growth will continue for several quarters. |
|---|
10 OPERATING METRICS: BEDS, OCCUPANCY AND REVENUE PER BED
| Metric | Q2 FY26 | Q2 FY27 | Source |
|---|---|---|---|
| Total bed capacity | 2,305 | 2,555 | Multibagg |
| Operational census beds | 1,535 | 1,820 | Multibagg |
| Occupancy | 66% | 72% | Multibagg |
| ARPOB (₹ per occupied bed per day) | 32,426 | 35,948 (+11%) | Multibagg; Angel One |
| Average length of stay | 4.0 days | 3.3 days | Multibagg |
| In-patient volume | 22,000 | 36,000 | Multibagg |
| Out-patient volume | 108,000 | 158,000 | Multibagg |
| IPD revenue / OPD revenue | ₹251 Cr / ₹32 Cr | ₹373.9 Cr / ₹57.5 Cr | Multibagg |
| Revenue from newer hospitals | 11% | 28% (₹120.5 Cr) | Multibagg |
Bed counts conflict across sources: "over 3,200 beds" (Whalesbook), "over 2,800 beds across nine hospitals" with 3,255 planned (Angel One), and 2,555 total capacity (Multibagg). The differences reflect operational, licensed and announced beds. The payer mix shows government schemes at about 35% of revenue (Whalesbook, Sahi), with a target of under 30% (Sahi) or 25% (Sahi); Faridabad Sector-20 is "more than 90%" cash and TPA business.
| RUPEIA CALCULATION Revenue per total bed in Q2 FY27 is ₹431.4 crore / 2,555 = ₹16.9 lakh a quarter, or ₹67.5 lakh annualised. Against the company's capex of ₹75–80 lakh per bed for the next 1,800 beds, a new bed repays its capex in revenue terms in about 1.1–1.2 years at the group average, before operating costs and ramp-up. At a 24% EBITDA margin the payback on capex is about 4.6–4.9 years (78 / (67.5 × 0.24)) for a bed at the group average. |
|---|
11 WHAT THE FY27 GUIDANCE IMPLIES FOR THE SECOND HALF
Management guided to FY27 revenue growth above FY26's 36% and EBITDA margin of 24–25% (Quartr, Sahi). Rupeia compared that with the first half already reported.
| Item | Calculation | Result |
|---|---|---|
| FY27 revenue at 36% growth (floor of guidance) | 1,207.2 × 1.36 | About ₹1,642 Cr |
| H1 FY27 revenue | Reported | ₹824.1 Cr |
| H2 FY27 revenue needed | 1,642 − 824.1 | About ₹818 Cr |
| H2 revenue at the Q2 FY27 run-rate | 431.4 × 2 | About ₹863 Cr |
| FY27 EBITDA at 24–25% of ₹1,642 Cr | 1,642 × 0.24 / 0.25 | ₹394–411 Cr |
| H1 FY27 EBITDA | 91.7 + 102.0 | ₹193.7 Cr |
| H2 EBITDA needed | 394–411 − 193.7 | ₹200–217 Cr |
| H2 EBITDA at the Q2 FY27 run-rate | 102 × 2 | ₹204 Cr |
| RUPEIA READ The guidance floor is roughly what the company is already running at. Holding the Q2 FY27 quarterly revenue and EBITDA flat for two more quarters would deliver about ₹1,687 crore of revenue (824.1 + 863) and ₹398 crore of EBITDA (193.7 + 204), inside the guided range. Guidance therefore asks for no further growth in the second half. The share price, which has already returned to the deal price, suggests the market wants more than the floor. |
|---|
12 IMPLIED VALUATION: WHAT ₹985.17 MEANS
Rupeia reconstructed the implied capitalisation from the published numbers. Advent's 31,974,180 shares equal 24.87% of the fully diluted count, so the fully diluted count after the deal is about 128.56 million shares and the pre-deal fully diluted count about 96.59 million. The market capitalisation on 27 August 2026 was ₹9,462 crore at ₹973.05 (Kotak Neo), which implies about 97.2 million shares, in line with that count.
| Item | Calculation | Result |
|---|---|---|
| Fully diluted shares after deal | 31,974,180 / 0.2487 | About 128.56 million |
| Pre-deal shares | 128.56 − 31.97 | About 96.59 million |
| Pre-money equity value | 96.59 million × ₹985.17 | About ₹9,516 Cr |
| Post-money equity value | 128.56 million × ₹985.17 | About ₹12,665 Cr |
| Enterprise value before money (net cash ₹116 Cr) | 9,516 − 116 | About ₹9,400 Cr |
| LTM revenue at Q2 FY27 | 1,207.2 − 542.3 + 824.1 | ₹1,489 Cr |
| LTM EBITDA at Q2 FY27 | 292.1 − 134.1 + 193.7 | ₹351.7 Cr |
| LTM PAT at Q2 FY27 | 170.3 − 83.29 + 93.88 | ₹180.9 Cr |
| EV / LTM revenue | 9,400 / 1,489 | About 6.3x |
| EV / LTM EBITDA | 9,400 / 351.7 | About 26.7x |
| Price / LTM earnings | 9,516 / 180.9 | About 52.6x |
| EV / FY26 EBITDA | 9,400 / 292.1 | About 32.2x |
| EV per total bed (2,555) | 9,400 / 2,555 | About ₹3.7 Cr |
| EV per census bed (1,820) | 9,400 / 1,820 | About ₹5.2 Cr |
| RUPEIA READ At about 27 times trailing EBITDA Yatharth is priced between Narayana Health (about 23x) and the large generalists (about 39x on The Core's August 2026 data), and in line with Multiples' own 27.3x LTM. The enterprise value per bed of ₹3.7 crore is about 4.7 times the company's own replacement cost of ₹75–80 lakh a bed, which is the premium the market and Advent are paying for an operating, ramped-up, profitable network rather than a construction pipeline. Whether the premium holds depends on newer hospitals reaching the margin of the older ones. |
|---|
13 DILUTION AND CONTROL: WHAT HAPPENS TO THE TYAGI FAMILY
| Item | Calculation or fact | Result |
|---|---|---|
| Promoter holding, June 2026 | Reported | 55.80% |
| Promoter shares (assuming about 96.6m outstanding) | 55.80% × 96.6 million | About 53.9 million |
| Promoter share of fully diluted post-deal count | 53.9 / 128.56 | About 41.9% (Rupeia estimate) |
| Increase in share count from Advent shares | 31.97 / 96.59 | +33.1% |
| Advent stake | Fully diluted | 24.87% |
| Open-offer threshold in the takeover code | General rule: 25% | Advent is 0.13 points below |
The company says the Tyagi family "will remain the Company's largest shareholder" (Business Today, quoting Yatharth). Multibagg calls the deal a minority investment, not a change of control, with Rasmalai classified as a public shareholder. In the Aster story, Kotak Neo and Angel One reported that a control sale would trigger a mandatory open offer for a further 26%, potentially taking a buyer above 75%.
| RUPEIA READ The 24.87% number is chosen, not accidental: it keeps Advent just under the 25% threshold of the takeover code, and the promoter family keeps roughly 42% on Rupeia's estimate after all warrants convert. Yatharth Tyagi's phrase "pivotal milestone" and the board seat describe a partner, not a buyer. If Advent later wanted more than 25%, the code would require an open offer to public shareholders, which would be a separate event. |
|---|
14 WHAT THE DEAL MEANS FOR EARNINGS PER SHARE
New shares dilute earnings per share until the new capital earns a return. Rupeia estimated the effect from the trailing figures in the implied-valuation section.
| Item | Calculation | Result |
|---|---|---|
| LTM profit after tax | From the Q2 FY27 build-up | ₹180.9 Cr |
| LTM earnings per share, before deal | 180.9 Cr / 96.59 million | About ₹18.7 |
| LTM earnings per share, after all new shares, before new earnings | 180.9 Cr / 128.56 million | About ₹14.1 |
| Mechanical dilution | 14.1 / 18.7 − 1 | About −24.9% |
| Extra profit needed to restore EPS | 180.9 × (128.56 / 96.59 − 1) | About ₹59.9 Cr |
| Return on the ₹3,150 Cr needed to do so | 59.9 / 3,150 | About 1.9% after tax |
| Price to earnings at ₹985.17 on pre-deal EPS | 985.17 / 18.7 | About 52.6x |
| RUPEIA READ A 1.9% after-tax return on the new money is a low bar, and a hospital bed yielding the group-average EBITDA margin clears it easily once opened. The dilution is real only during the build-out: the new beds take two to three years to ramp, and warrant money is not invested until exercise. A reader should watch EPS growth, not only revenue growth, over FY27 and FY28. |
|---|
15 THE ASTER STORY: A CONTROL SALE THAT BECAME A MINORITY DEAL
On 28 August 2026 Kotak Neo, citing people familiar with the matter, reported that Advent International and Aster DM Quality Care (backed by Blackstone and TPG) were negotiating for a controlling stake in Yatharth. Kotak Neo wrote that Yatharth "has denied being party to any sale discussions" and that Blackstone said it was "neither evaluating a deal nor part of any sale process". Angel One, citing the Economic Times, said due diligence was "nearing completion" with "no certainty of a deal", and that Aster preferred a cash transaction to a stock-based merger. Digital Health News had earlier reported talks for Advent to raise up to ₹3,000 crore through primary issuance in two tranches, taking 20–24%. Aster DM was described as having about 40 facilities in 27 cities and about 10,800 beds, with a target of 15,000 by FY29.
| Date | Share price event | Source |
|---|---|---|
| 27 Aug 2026 | Close ₹973.05; market cap ₹9,462 Cr | Kotak Neo |
| 28 Aug 2026 | Up 4.65% to ₹1,010.20 at 10:22 am; close ₹969.50 (−0.36%) | Kotak Neo; Angel One |
| 17 Sep 2026 | Up as much as 8.4–8.6% to a record ₹1,065–1,067 | Business Today; Reuters |
| 18 Sep 2026 | Up as much as 10.53% to ₹1,183.15; +20.38% over two days | Business Today |
| 3 Nov 2026 | NSE close ₹981.85 (+4.63%) | Angel One |
| RUPEIA CALCULATION At ₹1,183.15 the stock traded 20.1% above Advent's price (1,183.15 / 985.17); at the 3 November close of ₹981.85 it was 0.3% below it. Advent's equity shares were therefore worth ₹1,279 crore against ₹1,283 crore cost on 3 November (13,026,516 × 981.85), roughly break-even. Investors who bought on the announcement spike are below their entry unless they bought below about ₹982. |
|---|
16 STRATEGIC RATIONALE AND USE OF FUNDS
Yatharth says it will expand to more than 5,000 beds within three years and may reach it sooner (Sahi). Management put capex at ₹75–80 lakh per bed for the next 1,800 beds and about ₹1 crore per bed in Gurugram, targeting EBITDA margins of 24–25% in FY27 and revenue growth above FY26's 36%. Angel One quotes a reference to Advent capital supporting 7,000–8,000 beds.
| Plan item | Calculation | Result |
|---|---|---|
| New beds to reach 5,000 from 2,555 | 5,000 − 2,555 | 2,445 beds |
| Capex for 1,800 beds at ₹75–80 lakh | 1,800 × 0.75–0.80 | ₹1,350–1,440 Cr |
| Capex for Gurugram 250 beds at about ₹1 Cr | 250 × 1 | About ₹250 Cr (company: ₹100 Cr purchase plus ₹100 Cr) |
| Capex for the remaining 645 beds at ₹78 lakh | 645 × 0.78 | About ₹503 Cr |
| Total capex to reach 5,000 beds | 1,395 + 200 + 503 (mid-point) | About ₹2,100 Cr |
| Cash at signing plus Q2 cash | 1,750 + 429 | About ₹2,180 Cr |
| RUPEIA READ The upfront ₹1,750 crore plus existing cash of ₹429 crore covers roughly the entire capex needed to reach 5,000 beds on the company's own per-bed numbers, before operating cash flow of ₹287 crore a year. That makes the deferred ₹1,400 crore of warrants look like capacity for faster growth, acquisitions or the 7,000–8,000 bed ambition rather than a necessity. It also means Yatharth could in principle fund its stated plan with little debt, which helps the margin after finance cost. |
|---|
17 APPROVALS AND REGULATORY PATH
| Step | What the sources say | Status in sources read |
|---|---|---|
| Board approval | Board met 17 Sep 2026 and approved the preferential issue | Done |
| Increase in authorised capital | ₹115 Cr to ₹150 Cr; memorandum change | Needs shareholder vote |
| Shareholder approval (special resolution) | EGM reported for 15 Oct 2026 | Outcome not found |
| Stock exchange in-principle approval | Not stated | Not stated |
| CCI or sector approvals | Not stated | Not stated |
| SEBI takeover code | Minority stake; Rasmalai a public shareholder | No open offer described |
| Allotment and payment | Equity and upfront warrants on allotment | Not confirmed by 7 Nov 2026 |
Entrepreneur India says the transaction "has been approved by shareholders" while also saying the EGM was scheduled for 15 October; Sahi and Multibagg describe approvals as pending. Because the EGM outcome and allotment are not stated in any source read, this report treats the deal as signed and approved by the board but not shown as completed.
18 COMPARABLE DEALS AND PEER VALUATIONS
| Company or deal | EV/EBITDA or value | Source and date |
|---|---|---|
| Six large generalists (Apollo, Max, Fortis, Aster, Medanta, KIMS) | About 39x average; Aster about 46x, KIMS about 43x, Max about 42x | The Core, 19 Aug 2026 (data 13 Aug) |
| Specialists (Dr Agarwal's, Rainbow, HCG) | About 24–25x | The Core |
| Narayana Hrudayalaya | About 23x | The Core |
| Small regional chains (Kovai, Shalby, Indraprastha) | About 14x, 13x and 11x | The Core |
| Yatharth at market | About 27.3x LTM EBITDA, 6.7x revenue, 49.5x earnings; EV about US$1.1bn | Multiples.vc, 7 Nov 2026 |
| Yatharth at Advent price (Rupeia) | About 26.7x LTM EBITDA; 6.3x revenue; 52.6x earnings | Rupeia calculation |
| Apollo 24|7 (Advent, 2024) | ₹2,475 Cr equity | Digital Health News |
| CARE Hospitals (Blackstone, 2023) | Controlling stake; terms not stated in sources read | PipelineRoad |
| Medicover India (KKR) | US$1.4bn; terms not stated in sources read | PipelineRoad |
| RUPEIA READ The Advent price sits at the lower end of the large-chain range and in the middle of the specialist and regional range: Yatharth is not priced like Max or Aster. That is consistent with a regional chain with a government-scheme share of about 35% of revenue. A PE investor can reasonably call that a growth multiple, and a public-market investor can call it full for a chain whose ex-ramp-up margin is 28% but reported margin is under 24%. |
|---|
19 COMPETITION AND MARKET CONTEXT
ICRA's July 2026 update rated the Indian hospital sector outlook positive, with revenue growth of 13–15% and ARPOB growth of 6–8% projected for FY2027 and occupancy around 62–64%. Yatharth's occupancy of 72% and ARPOB growth of 11% are above those sector figures. The Core reports that the industry is adding about 34,000 beds by FY29 at over ₹40,000 crore, Aster DM is adding about 4,080 beds in two years, Rainbow is adding 2,500 beds, and Max plans 10,000 beds by FY30.
| Peer | Capacity or plan | Source |
|---|---|---|
| Aster DM Quality Care | About 40 facilities, about 10,800 beds; target 15,000 by FY29 | Kotak Neo; Angel One |
| Max Healthcare | 10,000 beds by FY30; ₹6,000 Cr planned capex | The Core citing Business Today |
| Rainbow Children's | Add 2,500 beds to reach 5,000 for about ₹2,200 Cr | The Core |
| Manipal Hospitals | 49 hospitals, 12,600+ beds (2026) | Aggregator |
| Yatharth | 2,555 beds now; 5,000+ in three years | Multibagg; Sahi |
20 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Red flag | Evidence | Severity | Kill condition | What would resolve it |
|---|---|---|---|---|
| Completion risk | EGM and regulatory approvals; no allotment confirmed | MEDIUM | Shareholders reject or SEBI objects | Allotment announcement |
| Warrant optionality | ₹1,400 Cr (44%) payable only on exercise | MEDIUM | Share price below ₹985.17 when exercise is due | Exercise notices |
| Margin dilution from ramp-up | EBITDA margin 25.4% to 23.6%; depreciation +75% | MEDIUM | Margin below 22% for two quarters | Faridabad and Model Town reach breakeven |
| Government-scheme dependence | About 35% of revenue | MEDIUM | Rate cuts or payment delays | Mix target under 30% |
| Working capital | Debtor days 112 | MEDIUM | Days rise above 120 | Target 90–95 by FY27 |
| Valuation | About 27x LTM EBITDA; 52.6x earnings | MEDIUM | Growth slows below 30% | Revenue growth above FY26's 36% |
| Bed-count ambiguity | 2,555, 2,800 and 3,200+ across sources | LOW | Investor presentation redefines beds | Uniform bed disclosure |
| Execution of 2,400+ beds | Gurugram timing April 2027 to H1 FY28 | MEDIUM | Openings slip beyond FY28 | Opening on schedule |
21 SCENARIO ANALYSIS: FY27 TO FY29
| Scenario | What happens | Implication |
|---|---|---|
| Bull | Revenue growth stays above 40%; newer hospitals reach ex-ramp-up margins near 28%; Advent exercises all warrants early | Multiple holds near 27x on a larger EBITDA base; 5,000 beds reached ahead of plan |
| Base | Revenue grows 30–36%; margin stays 23–25%; warrants exercised on schedule | Share price tracks earnings growth; Advent exits through stock-market sales later |
| Bear | Ramp-up drags margin below 22%; payment delays raise debtor days; share price falls below ₹985.17 | Advent does not exercise warrants; upfront ₹467 Cr is lost; growth capital shrinks |
Scenarios are for discussion. They are not forecasts, use no unpublished company data and do not predict a share price.
22 INVESTOR CLASS ANALYSIS
For HNIs
Yatharth is a listed stock and can be held through a demat account. The Advent price of ₹985.17 is a useful reference, but the preferential allotment cannot be joined. Positions in a stock that moved 20% in two days should be sized for volatility.
For family offices
Family offices can follow the same logic as Advent through placements and block deals. The staged warrant structure is a template for a staged entry, which limits the capital committed before the company shows ramp-up results.
For institutions
Long-only and healthcare funds will compare the 27x multiple with sector peers and with Advent's buy-in price. The new capital also lowers the risk of a dilutive equity raise later.
For NRIs
NRIs can buy listed Indian shares through the portfolio investment scheme subject to RBI and FEMA limits for non-resident holdings.
23 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| A profitable, growing listed hospital chain with a global PE partner | YATHARTH | Revenue +52%, PAT positive, new hospitals reaching breakeven | About 27x EBITDA; deal completion pending |
| A private hospital model at an early stage | EVEN HEALTHCARE (Report 20) | Salaried-doctor model; Khosla-backed | Loss-making; unlisted |
| A larger, higher-multiple hospital exposure | Large listed chains | Scale and liquidity | About 39x EBITDA |
24 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| Q4 2026 | Allotment of shares and upfront warrants | Confirms the ₹1,750 Cr arrives |
| Q3 FY27 results (early 2027) | Margin and depreciation trend | Shows whether ramp-up costs are peaking |
| H2 FY27 | Model Town EBITDA breakeven | Test of the newer-hospital model |
| By April 2027 to H1 FY28 | Gurugram 250-bed opening | Highest ARPOB site |
| 2027–28 | Warrant exercise | Whether Advent pays the remaining ₹1,400 Cr |
25 RUPEIA FINAL INDEPENDENT VIEW
Advent's ₹3,150 crore commitment is a significant endorsement of a regional hospital chain whose deal price is more than three times its IPO price and whose revenue nearly doubled between FY24 and FY26. The structure is careful: a minority stake just under the open-offer line, half the cash on day one and the rest at Advent's option, a price within a fraction of the market, and a Tyagi family that stays in charge. For Yatharth the deal means the funding for its plan to reach 5,000 beds is largely in hand.
What remains open is delivery. Margins have slipped as newer hospitals ramp, depreciation and finance cost are rising quickly, and the market price after the announcement spike has returned to the deal price. The case rests on the newer hospitals following Faridabad and Agra to profitability, and on revenue growth staying above the 36% of FY26.
| THE RUPEIA NUMBER ₹1,750 crore: the cash Advent pays at allotment (equity ₹1,283 crore plus 25% of the warrants, ₹467 crore), 55.6% of the headline ₹3,150 crore. |
|---|
| RUPEIA VERDICT A well-structured minority investment at roughly the market price. The headline overstates the cash on day one, and the next signals are allotment, the margin trend and warrant exercise. This note offers no buy, sell or price view. |
|---|
Frequently asked questions
How much is Advent investing in Yatharth Hospitals?
₹3,150 crore (about US$328.5 million) of primary capital, announced on 17 September 2026, for 24.9% (24.87% fully diluted) through Rasmalai Limited, a Cyprus-incorporated Advent vehicle.
At what price is Advent buying?
₹985.17 per equity share and per warrant. That is about 0.3% above the implied prior close of about ₹982 on 17 September (Rupeia derivation from Angel One) and 3.3 times the IPO price of ₹300.
Is the full ₹3,150 crore paid at once?
No. Equity of ₹1,283.33 crore is paid on allotment together with 25% of the warrant price (about ₹467 crore, Rupeia calculation). The remaining ₹1,400 crore is payable when Advent exercises its warrants.
Does Advent take control of Yatharth?
No. Advent gets a 24.87% fully diluted stake and non-executive board representation. The Tyagi family, which held 55.80% in June 2026, remains the largest shareholder.
What were the Aster DM reports?
On 28 August 2026 press reports said Advent and Aster DM Quality Care were negotiating for control. Yatharth denied being party to sale talks and Blackstone said it was not evaluating a deal.
What are Yatharth's latest results?
Q2 FY27 revenue was ₹431.4 crore (+52%), EBITDA ₹102 crore (+50%), PAT ₹48.5 crore (+17%) and occupancy 72%. FY26 revenue was ₹1,207.2 crore, EBITDA ₹292.1 crore and PAT ₹170.3 crore.
What valuation does the deal imply?
Rupeia estimates pre-money enterprise value of about ₹9,400 crore, or about 26.7 times trailing EBITDA, 6.3 times revenue and 52.6 times earnings. The company has not published such multiples.
What will the money be used for?
Expansion to more than 5,000 beds in three years, including a 250-bed Gurugram hospital. Management cites capex of ₹75–80 lakh per bed.
Has the deal closed?
Not confirmed in the sources read. It needs shareholder approval (EGM reported for 15 October 2026) and customary regulatory approvals.
Source log
Advent International: to invest ₹3,150 crore in Yatharth Hospitals for 24.9% stake
Sahi: Yatharth Hospitals secures ₹3,150-crore Advent investment
Digital Health News: Advent to invest ₹3,150 Cr in Yatharth Hospitals
Digital Health News: Yatharth Hospitals in talks with Advent
Entrepreneur India: Advent to invest US$328.5 Mn in Yatharth Hospital
Angel One: Yatharth Hospitals share price surges as Advent invests
DealStreetAsia: Advent to buy 25% in Yatharth Hospital for US$328.5 million
Multibagg: Yatharth Hospital okays ₹3,150 crore issue
InvestyWise: Yatharth Hospitals private equity investment secured
Omnicuris: Advent Yatharth Hospitals private equity investment
Business Today: Yatharth Hospital shares jump over 8% to record high
Business Today: Yatharth Hospital shares jump 20% in two days
Kotak Neo: Advent, Aster eye controlling stake in Yatharth Hospitals
Angel One: Aster DM, Advent in reported talks for controlling stake
PipelineRoad: Advent to invest US$328.5m for 24.9% stake in Yatharth
Whalesbook: Yatharth Hospital FY26 revenue surges 36% to ₹1,207 Cr
Business Today: Yatharth Hospital shares slip 7% after Q4 FY26 results
Quartr: Yatharth Hospital Q4 25/26 earnings summary
Multibagg: Yatharth Q2 revenue rises 52% as PAT growth slows to 17%
Multibagg: Yatharth new hospitals reach 28% of Q2 FY27 group revenue
Angel One: Yatharth Hospital share price gains after Q2 FY27 results
Sahi: Yatharth Hospital targets upwards of 24% EBITDA margin and ₹75-80 lakh capex per bed
Sahi: Yatharth Hospital expects to reach 5,000-bed capacity sooner
Multiples.vc: Yatharth Hospital valuation multiples
5paisa: Yatharth Hospital IPO
DT Next: Yatharth Hospital mops up ₹206 Cr from anchor investors
Outlook Business: Yatharth Hospital IPO price band ₹285-300
The Core: India's listed hospital chains valuation analysis
ICRA: Hospital sector, strong demand and ARPOB rise support FY2027 growth
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|