Even Healthcare: US$50 million Series B
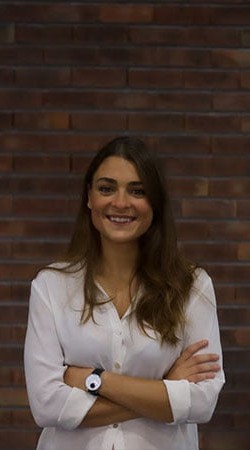
Matilde Giglio, co-founder of Even, in a 2022 company-issued photograph · Image: Even, via ThePrint (April 2022)
Independent report content
| COMPANY | Even Healthcare, Bengaluru · founded 2020 (Wikipedia, ThePrint) or 2021 (Entrackr, TechCrunch) by Mayank Banerjee, Matilde Giglio and Alessandro Ialongo · about 650 staff, about 300 full-time doctors (TechCrunch) |
|---|---|
| ROUND | Series B, US$50m (about ₹475 Cr), announced 19 October 2026 · all-equity, primary · led by existing investor Khosla Ventures with Alpha Wave |
| VALUATION | About US$300m, "according to Even" (TechCrunch) · company says valuation tripled in 18 months · about ₹2,895 Cr at ₹96.5 per US$ |
| FUNDING TO DATE | Over US$120m (Entrackr, TechCrunch) · US$72.5m across five rounds before this one (Medical Dialogues, August 2026) |
| LATEST FINANCIALS | FY25: revenue ₹25.43 Cr (Entrackr Oct) or ₹27.2 Cr (TechCrunch, Entrackr Aug); net loss ₹90.15 Cr, up 24.5% from ₹72.40 Cr · FY26 not yet filed |
| OPERATIONS | Two Bengaluru hospitals (Race Course Road, HBR Layout) · five more planned · over 250,000 members in 10 cities (company) |
| RESTRUCTURING | About 350 employees (30–35% of workforce) let go in August 2026 as the insurance business was scaled back (Entrackr) |
| THE ACCESS POINT Even Healthcare is a private company. The Series B was subscribed by existing institutional investors. Individuals can reach it only through private secondary sales or funds that hold it. The latest price reference is the October 2026 round at about US$300 million (about ₹2,900 crore), a figure Even supplied to TechCrunch. |
|---|
Executive decision summary
| THE BOTTOM LINE | Even is trying to rebuild an Indian hospital around one idea: pay doctors a salary, not per procedure, so the hospital earns by keeping people well. In October 2026 it raised US$50 million (Khosla Ventures leading, Alpha Wave participating) at about US$300 million, three times the valuation of 18 months earlier. It says both its Bengaluru hospitals reached operating profit, excluding depreciation, within a year, and that unplanned readmissions are below 1%. Its accounts tell a harder story: FY25 revenue of about ₹25–27 crore against a net loss of ₹90 crore, a restructuring in August 2026 that removed about 350 jobs, and a plan to build five more hospitals on 20-year leases. The model may work; the published numbers cannot yet show it. |
|---|---|
| WHICH INVESTOR | Even fits you IF you want exposure to a clinical-quality-led hospital model, can hold a private position through a capital-hungry build-out, and accept a valuation of roughly 114 times FY25 revenue. Wait IF you need audited FY26 accounts and hospital-level numbers first. Neither is published, and the readmission and profitability claims come from the company. |
| COMFORT FIT | Even = a hospital that is paid like a family doctor. Salaried doctors, outcome bonuses and a monthly membership instead of a bill for every test. Facility profit "excluding depreciation" = a restaurant that covers its chefs and ingredients but not yet the cost of the kitchen. It shows the room works; it does not show the chain pays back. A 20-year lease with Even paying for the fit-out = renting a shell and building the house yourself. You own the interior and the obligation. Report 19 (Scapia) = another venture-funded consumer business with a loss several times revenue. Scapia's costs are people and rewards; Even's are people, rent and equipment. |
| THE RUPEIA NUMBER | ₹90.15 crore. Even's FY25 net loss, on revenue of about ₹25.43 crore (Entrackr). That is 3.5 rupees lost for every rupee of revenue, and FY26 filings are still awaited. |
1 CLAIM REGISTER: EVIDENCE GRADING
A = government, regulator or statutory filing. B = company or manager release or website. C = independent press. D = third-party database, blog or aggregator.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| US$50m Series B, led by Khosla Ventures with Alpha Wave, all-equity primary round, 19 Oct 2026 | Inc42, Indian Retailer, Digital Health News, Entrepreneur India, Entrackr, TechCrunch | C | Established |
| ₹208.24 crore tranche: 191,228 CCPS at ₹10,889.91; Khosla ₹145 Cr | Registrar filings as reported by Medical Dialogues (29 Aug 2026) | A | Established (filing-based) |
| Valuation about US$300m | TechCrunch, "according to Even" | C | Company-supplied figure |
| FY25 revenue ₹25.43 Cr and loss ₹90.15 Cr | Entrackr, 19 Oct 2026 (RoC data) | A | Established; revenue differs by source |
| FY25 revenue ₹27.2 Cr | Entrackr (Aug 2026); TechCrunch | A | Conflicts with ₹25.43 Cr |
| About 350 employees laid off in August 2026 | Entrackr, 27 Aug 2026, four sources | C | Company acknowledged restructuring to TechCrunch |
| Unplanned readmissions below 1% vs 8–15% benchmark; stays 40% shorter | Company statements via Inc42, Digital Health News, TechCrunch | B | Company-reported |
| Both hospitals operationally profitable excluding depreciation within a year | Founder to TechCrunch | B | Company-reported, not audited |
| Over 250,000 members in 10 cities | Company via Inc42, Entrackr, TechCrunch | B | Company-reported, definition not given |
| NABH 6th edition accreditation for the Race Course Road hospital | Entrepreneur India (company release) | B | Company-reported |
2 COMPANY OVERVIEW & FOUNDERS
Even Healthcare began as a subscription primary-care business in Bengaluru and has become a hospital operator. Sources disagree on its founding year: Wikipedia and a 2022 ThePrint release say January 2020, Entrackr and TechCrunch say 2021. The founders are Mayank Banerjee, Matilde Giglio and Alessandro Ialongo. Banerjee is quoted as co-founder in the Series B coverage; Wikipedia lists Banerjee as CEO. Giglio was described as co-founder and CEO in 2022 and as co-founder and COO by Digital Health News and Wikipedia. Wikipedia says Banerjee and Giglio had earlier worked together on media technology in the United Kingdom and the United States, including the journalism start-up Compass News. Digital Health News says the leadership team includes former executives of Columbia Asia and Narayana Health, without naming them.
| Item | Published detail | Source |
|---|---|---|
| Founders | Mayank Banerjee, Matilde Giglio, Alessandro Ialongo | Inc42; Digital Health News; Entrepreneur India |
| Headquarters | Bengaluru; corporate office in Indiranagar (Balloon Healthcare Private Limited named on the hospital site) | Even hospital website |
| Staff | About 650 including about 300 full-time doctors (Oct 2026); about 300 staff in Oct 2024 | TechCrunch; Entrackr |
| Doctor pay | Fixed salaries with bonuses tied to patient-reported clinical outcomes; every employee, including doctors, receives equity | TechCrunch; Inc42 |
| Backers | Khosla Ventures, Alpha Wave Global, Founders Fund, 8VC, Lachy Groom and others | Entrackr; TheBioStartups |
3 TIMELINE: 2020–2026
| Date | Milestone |
|---|---|
| 2020–21 | Company founded in Bengaluru; digital-first preventive and primary-care model |
| Jul 2021 | US$5m seed led by Khosla Ventures (Entrackr first reported) |
| Apr 2022 | Plans "Even Plus" and "Even Lite" marketed with unlimited outpatient care from ₹525 a month and an optional ₹50 lakh hospitalisation cover |
| Nov 2022 | US$15m from new investors Alpha Wave Global and Aspada (Lightrock); total about US$20m |
| Aug 2024 | US$20m (₹169 Cr) Series A tranche led by Khosla (₹83.4 Cr); preference shares at ₹7,762 |
| 23 Oct 2024 | US$30m Series A tranche led by Khosla; total about US$50m (Entrackr); funds for hospitals |
| Mar 2025 | US$0.5m secondary transaction for an employee-option buyback (Wikipedia citing Inc42) |
| May–Jul 2025 | First hospital opens at Race Course Road, Bengaluru; Wikipedia gives both May and July 2025; 70 beds |
| Jan 2026 | US$20m extension of Series A led by Lachy Groom and Alpha Wave |
| 26–29 Aug 2026 | Filings show ₹208.24 Cr (about US$22m) Series B tranche led by Khosla; Entrackr reports about 350 layoffs |
| 19 Oct 2026 | US$50m Series B announced; valuation about US$300m; total funding over US$120m |
4 THE MODEL: SALARIED DOCTORS, MEMBERSHIP AND OWN HOSPITALS
Even's thesis, as the founder put it to TechCrunch, is that "patients are getting not only a bad experience, but insurers are getting a bad economic deal". Its answer has four parts. Members pay a monthly fee for unlimited doctor consultations and diagnostics; the 2022 launch plans started at ₹525 a month, with an optional hospitalisation cover of ₹50 lakh and cashless care at partner hospitals. Doctors are salaried, with bonuses tied to patient-reported outcomes rather than procedures. Hospitals are owned and run by Even, so the same organisation that sells the membership treats the admission. Insurers, which Even does not name, are offered programmes under which Even is compensated for hospitalisations it helps prevent.
| Layer | What Even does | Who pays | Published evidence |
|---|---|---|---|
| Membership | Unlimited consultations and tests, plans from ₹525 a month (2022) | Individuals and employers | About 250,000 members in 10 cities (company) |
| Clinics | Six clinics in Bengaluru (2025–early 2026 reports) | Members | Wikipedia; Digital Health News |
| Hospitals | Own multispeciality hospitals on leased buildings | Patients, insurers | Two open; five more planned |
| Insurer programmes | Reduces avoidable admissions for insurer partners | Insurers | Partners not named; savings claims differ |
| Partner hospitals | About 100 third-party hospitals (early 2026) | Members | Wikipedia |
| RUPEIA READ This is a payer-and-provider structure, and each half is risky on its own. The provider half (hospitals) needs heavy capital and high occupancy. The payer half (membership and insurer programmes) needs enough healthy members to pay for the sick ones. Combining them earns more only if the hospital stops treating avoidable cases and the saved money reaches Even. The October 2026 coverage says Even is still "working with insurer partners on a model that could compensate it", which means that half is not yet proven. |
|---|
5 MEMBERSHIP ECONOMICS: WHAT 250,000 MEMBERS CAN AND CANNOT MEAN
Even says it has more than 250,000 members in ten cities, roughly three times a year earlier. Medical Dialogues, citing Inc42, reported about 50,000–60,000 members in Bengaluru and 200,000–300,000 patients across India. The company has not said how many members pay, how many are covered through an employer, or how many are simply registered. The only published price is from the April 2022 launch: "Even Plus" and "Even Lite" plans starting at ₹525 a month.
| Calculation | Formula | Result |
|---|---|---|
| Annual entry price per member (2022) | ₹525 × 12 | ₹6,300 |
| Revenue if all 250,000 members paid that price | 250,000 × ₹6,300 | ₹157.5 Cr a year |
| That figure against FY25 revenue of ₹25.43 Cr | 157.5 / 25.43 | 6.2x |
| Same, in Bengaluru only (50,000–60,000 members) | 55,000 × ₹6,300 | About ₹34.7 Cr a year |
| RUPEIA CALCULATION If every one of the 250,000 members paid the 2022 entry price, annual membership revenue would be ₹157.5 crore, more than six times FY25 revenue. Since FY25 revenue was ₹25–27 crore, most members are either not paying that price, were added late in the year, or are counted under employer and partner arrangements that bring in far less per head. The reading is a limit on how to use the headline: "250,000 members" describes reach, not revenue. |
|---|
This matters for the valuation per member. At US$300 million the valuation is about US$1,200 (₹1.16 lakh) per member, or about 18 years of the entry fee, so the value case rests on members becoming hospital patients and insurer-programme participants, not on subscriptions. That is consistent with the company's decision to scale back the insurance business and concentrate on hospitals in August 2026.
6 THE HOSPITALS: RACE COURSE ROAD, HBR LAYOUT AND THE NEXT FIVE
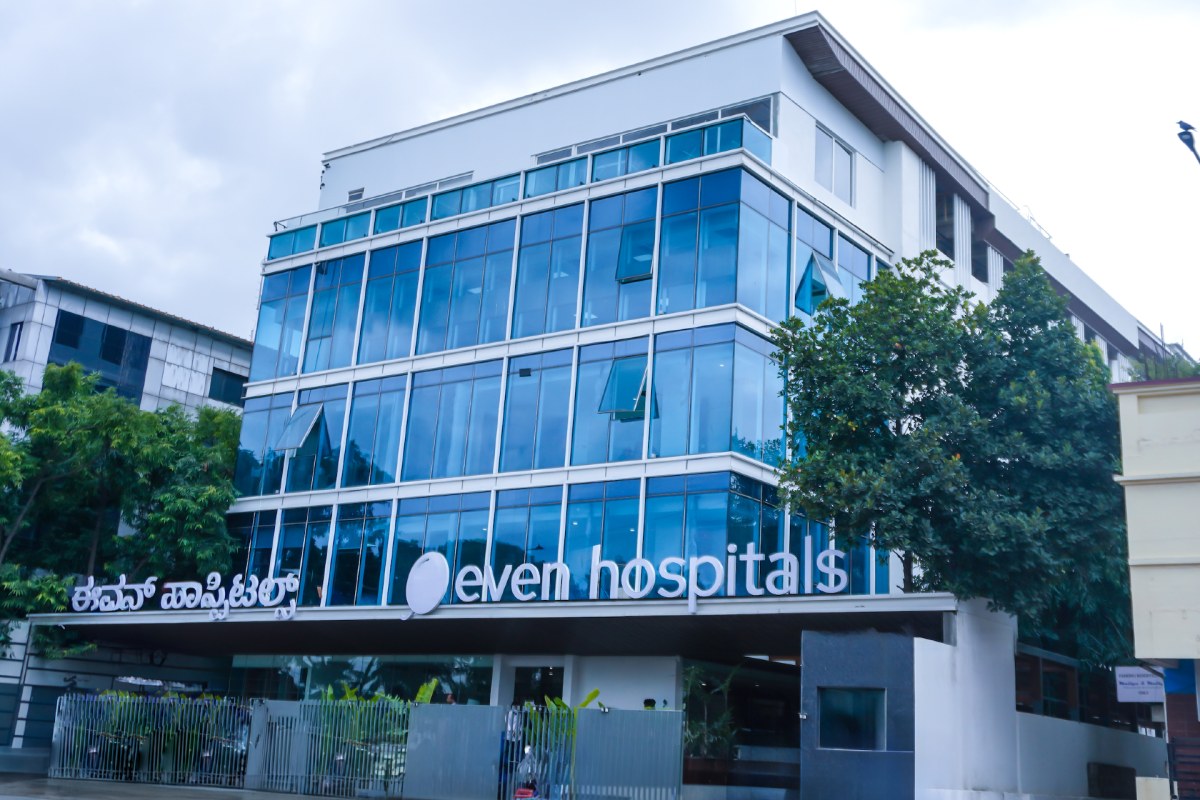
Even Hospital at 29/2 Race Course Road, Bengaluru, is the flagship. Wikipedia gives it 70 beds, and Digital Health News quoted 60–65 beds before it opened with the inauguration planned for 15 July 2025. The hospital site lists specialities including cardiology (non-interventional), general and plastic surgery, neurosurgery, dermatology, gastroenterology and pulmonology, and claims "500,000+ clinical events handled", "97% patient satisfaction" and "50% reduced readmissions". The second hospital is at HBR Layout. A third, in Indiranagar, is named as the next opening.
Even doctors with a patient at an Even hospital · Image: Even hospital website (hospitals.even.in)
| Item | Published detail | Source |
|---|---|---|
| Open hospitals | Race Course Road and HBR Layout, both multispeciality | Inc42; Indian Retailer; TechCrunch |
| Next opening | Indiranagar | Digital Health News; Entrepreneur India |
| Expansion timeline A | Five new hospitals in six months | Digital Health News; Entrepreneur India |
| Expansion timeline B | One more by end-2026, three more by end of FY27 | Inc42; Indian Retailer |
| Longer plan | 25 facilities in 18 months (2025 statement) or over 36 months (Wikipedia) | Digital Health News; Wikipedia |
| Capex per hospital | Average investment about US$3.5m (2025) | Digital Health News |
| Accreditation | NABH 6th edition for Race Course Road within its first year | Entrepreneur India (company) |
| Lease structure | About 20-year leases; Even pays fit-out and medical equipment | TechCrunch |
| RUPEIA CALCULATION US$3.5m per hospital is about ₹33.8 crore at ₹96.5 per US$. Five hospitals would need about US$17.5m (₹169 crore) and 25 hospitals about US$87.5m (₹844 crore), against a US$50m round. The October round therefore funds roughly the first 14 hospitals at that cost (50 / 3.5), before operating losses. The two sources give two different rollout speeds, and the company has not reconciled them. |
|---|
7 HOSPITAL ECONOMICS: ILLUSTRATING WHAT A 70-BED SITE COULD EARN
Even has not published revenue per bed, occupancy or hospital-level profit. To size the question, Rupeia combined the 70-bed figure for Race Course Road with the occupancy ICRA reported for listed Indian hospital chains (63.3% in H1 FY26) and three assumed revenues per occupied bed per day (ARPOB). The ARPOB values are hypothetical, not Even data.
| Assumed ARPOB (₹ per day) | Occupied bed-days (70 × 63.3% × 365) | Annual revenue (₹ crore) |
|---|---|---|
| 30,000 | 16,173 | 48.5 |
| 45,000 | 16,173 | 72.8 |
| 60,000 | 16,173 | 97.0 |
| RUPEIA READ One mature 70-bed hospital at these assumptions could earn ₹48–97 crore a year, which is two to four times Even's entire FY25 revenue. That shows why the company is pivoting from membership and insurance towards hospitals: a hospital is where revenue per member rises sharply. It also shows the risk: a hospital with a fixed cost base and a 20-year lease earns that revenue only at high occupancy, and a ramp-up year at 30% occupancy would earn under half of the first row. |
|---|
ICRA's July 2026 update rated the Indian hospital sector outlook positive, with revenue growth of 13–15% and ARPOB growth of 6–8% expected in FY2027, after 16% revenue growth in H1 FY26. Occupancy has held at about 62–64%. A new entrant with no brand history in a catchment therefore starts below the sector average and must climb to it.
8 FINANCIAL FORENSICS: FY24 AND FY25
| ₹ crore | FY24 | FY25 | Source |
|---|---|---|---|
| Revenue | 6.24 (Entrackr Oct) or 8.3 (Entrackr Aug) | 25.43 (Entrackr Oct) or 27.2 (Entrackr Aug; TechCrunch ₹272m) | RoC data via Entrackr and TechCrunch |
| Net loss | 72.40 | 90.15 (Entrackr Oct) or 90.2 (Entrackr Aug) | Entrackr; TechCrunch |
| Loss growth | - | +24.5% | Entrackr |
| Loss per ₹1 of revenue | ₹8.7 to ₹11.6 | ₹3.3 to ₹3.5 | Rupeia calculation |
| FY26 | - | Not yet filed (Entrackr, Oct 2026) | Entrackr |
The two Entrackr articles disagree on revenue in both years, and neither explains why. A plausible but unconfirmed reason is a difference between "revenue from operations" and a narrower total. FY25 revenue was 4 times FY24 on the October figures (25.43 / 6.24) and 3.3 times on the August ones (27.2 / 8.3). Either way, revenue grew far faster than the loss, so the loss per rupee of revenue fell by about two-thirds. Entrackr put the Oct 2024 revenue run-rate at US$28m "18 months after commercial launch" and Digital Health News quoted FY24 revenue of US$30m in 2025; both are far above the RoC figures, and the sources do not say whether they refer to gross billings, member collections or a different entity.
| RUPEIA CALCULATION ₹90.15 Cr / ₹25.43 Cr = 3.5x. If revenue keeps rising about fourfold a year and the loss stays flat, FY26 revenue would be about ₹100 crore and the loss about ₹90 crore, or 0.9 times revenue. That is arithmetic, not a forecast, and it ignores the August 2026 job cuts, which would reduce costs and also remove insurance revenue. |
|---|
| RUPEIA READ Even's losses are large for its revenue, but they have not exploded: up 24.5% in a year when revenue rose three- to fourfold. That is the pattern investors fund. The weakness is the gap between the published figures and the claimed scale (US$28–30m run-rates). Until FY26 accounts reconcile them, headline scale numbers should be treated as company statements. |
|---|
9 FUNDING HISTORY: EVERY ROUND
| Round | Date | Amount | Lead and participants (published) | Total after |
|---|---|---|---|---|
| Seed | 2021 | US$5m | Khosla Ventures | US$5m |
| Additional round | Nov 2022 | US$15m | Alpha Wave Global and Aspada (new); Khosla, Founders Fund, Lachy Groom, Nikesh Arora, Kunal Shah, Tom Stafford (existing) | About US$20m |
| Series A, tranche 1 | Aug 2024 | US$20m (₹169 Cr) | Khosla ₹83.4 Cr; Mercury Fund ₹26.9 Cr; Pathfinder ₹21.3 Cr; Simon Fiduciaria, DLB Ventures, Lex Italia, 8VC, Rainmatter and others | About US$40m (Entrackr) |
| Series A, tranche 2 | 23 Oct 2024 | US$30m | Khosla (lead); Founders Fund, 8VC, Lachy Groom | About US$50m (Entrackr) |
| Series A extension | Jan 2026 | US$20m | Lachy Groom and Alpha Wave (lead); Sharrp Ventures also named | About US$80m (Wikipedia) |
| Series B (filed tranche) | Aug 2026 | ₹208.24 Cr (about US$22m) | Khosla ₹145 Cr; DLB ₹38.88 Cr; Simon Fiduciaria ₹22.67 Cr; ADBEEV ₹1 Cr; Better Capital ₹1 Cr | About US$72.5m before (Medical Dialogues) |
| Series B | 19 Oct 2026 | US$50m (about ₹475 Cr) | Khosla Ventures (lead); Alpha Wave | Over US$120m |
| RUPEIA CALCULATION Adding the headline rounds gives US$5m + 15m + 20m + 30m + 20m = US$90m before the Series B, and US$140m with it, which is above the company's "over US$120m". Medical Dialogues' US$72.5m before the Series B plus US$50m gives US$122.5m, which matches. The sources do not say whether the August filing tranche is part of the US$50m, or whether the January 2026 extension was counted in the Series A total. Rupeia uses "over US$120m" as the company figure. Khosla supplied 69.6% of the August tranche (145 / 208.24). |
|---|
The August 2026 tranche is the only one with a documented share price: 191,228 compulsorily convertible preference shares at ₹10,889.91, which multiplies to about ₹208.2 crore. In August 2024 the preference shares were issued at ₹7,762, so the price per share rose 40% in two years (10,889.91 / 7,762 = 1.40). Entrackr, citing TheKredible, estimated the August 2024 valuation at about ₹753 crore (US$91m), and the October 2026 valuation of about US$300m is 3.3 times that. A 3.3-fold valuation rise alongside a 1.4-fold price rise implies the share count grew by a large factor, which public filings read for this report do not explain.
10 INVESTOR FORENSICS: WHO BACKS EVEN
| Investor | Role | Published detail |
|---|---|---|
| Khosla Ventures | Seed and every later lead | Vinod Khosla: "Even is attempting something much more ambitious" |
| Alpha Wave Global | Entered Nov 2022; Series B participant | Co-led Jan 2026 extension |
| Founders Fund | Early and Series A investor | Participated Oct 2024 |
| 8VC | Series A investor | Participated Aug and Oct 2024 |
| Lachy Groom | Angel and Series A | Co-led Jan 2026 |
| Aspada (Lightrock) | Nov 2022 | New investor in the US$15m round |
| Pathfinder, Mercury Fund | Aug 2024 | ₹21.3 Cr and ₹26.9 Cr |
| DLB Ventures, Simon Fiduciaria | Aug 2024 and Aug 2026 | ₹38.88 Cr and ₹22.67 Cr in the Series B tranche |
| Angels | Early rounds | Nikesh Arora, Kunal Shah, Tom Stafford, named in 2022 |
| RUPEIA READ Khosla has led every priced round and supplied about 70% of the August 2026 tranche. Few venture investors double down this heavily in a single Indian company. The upside for Even is steady support through a slower-than-planned hospital ramp. The risk is concentration: if Khosla's view changes, there is no obvious second lead. The cap table, option pool and preference terms are not public. |
|---|
11 EMPLOYEE EQUITY AND THE OPTION POOL
Banerjee told TechCrunch that every employee, including doctors, receives equity in Even. Entrackr reported in August 2024 that the option pool had been raised to 135,000 options and estimated its value at about US$12 million at that time. In the August 2024 tranche the company issued 217,589 preference shares, so the pool equals about 62% of that single tranche's share count (135,000 / 217,589). The comparison is of share counts only and is not an ownership percentage, because the full share capital is not public.
| Item | Figure | Source or calculation |
|---|---|---|
| Option pool (Aug 2024) | 135,000 options | Entrackr |
| Series B tranche price (Aug 2026) | ₹10,889.91 per CCPS | Registrar filing via Medical Dialogues |
| Gross value of the full pool at that price | ₹147.0 Cr (about US$15.2m) | Rupeia: 135,000 × ₹10,889.91, before exercise cost |
| Accelerated vesting for those laid off (Aug 2026) | Offered; size not disclosed | TechCrunch |
| RUPEIA READ Broad equity ownership is part of the model: doctors on fixed salaries are meant to share in the hospital's long-term success rather than in each procedure. It also means a meaningful share of future value is already committed to staff, which dilutes investors. The accelerated vesting offered to departing employees adds a one-off dilution that the company has not quantified. |
|---|
12 VALUATION ANALYSIS
| Multiple | Calculation | Result |
|---|---|---|
| Valuation in ₹ crore | 300 × 96.5 / 10 | About ₹2,895 Cr |
| Valuation to FY25 revenue (₹25.43 Cr) | 2,895 / 25.43 | About 114x |
| Valuation to FY25 revenue (₹27.2 Cr) | 2,895 / 27.2 | About 106x |
| Valuation per member (250,000) | US$300m / 250,000 | About US$1,200 (₹1.16 lakh) |
| Step-up over Aug 2024 estimate | 300 / 91 | 3.3x |
| Series B as share of valuation | 50 / 300 | 16.7% |
| Valuation to one mature hospital at ₹72.8 Cr | 2,895 / 72.8 | About 40 hospital-years |
| RUPEIA READ The 114x multiple on FY25 revenue measures how much future is priced in, not current value. The better test is the right-hand row: at the middle illustration of ₹72.8 crore a hospital, the valuation equals about 40 hospital-years of revenue. If Even reaches 25 hospitals each earning that much, revenue would be about ₹1,820 crore and the valuation about 1.6 times that revenue, a level comparable with hospital businesses. The path from two hospitals to 25 is the whole valuation case. |
|---|
13 THE AUGUST 2026 RESTRUCTURING
Entrackr reported on 27 August 2026, citing four sources, that Even had let go about 350 employees, nearly 30–35% of its workforce, across multiple teams, "as Even looks to reduce its cost base", and that it was phasing down its insurance business in favour of a hospital-led model. Queries to the company went unanswered at that time. On 19 October the founder acknowledged the restructuring to TechCrunch and called it a difficult decision and said affected staff received severance, extended health insurance and accelerated equity vesting. Headcount in October was about 650 including about 300 full-time doctors, which implies roughly 1,000 before the cuts (650 + 350), consistent with a 35% reduction.
| RUPEIA READ A layoff in the same quarter as an equity raise is a strategic reset, not necessarily distress. The sequence is consistent with a company deciding that insurance administration was a weaker business than hospitals, shrinking it, and raising money for the stronger one. What it does show is that the earlier model, a membership-and-insurance company with clinics, was not the one the October round is funding. Readers should treat 2025 membership and revenue claims as describing a different business mix from today's. |
|---|
14 CLINICAL CLAIMS AND WHAT THEY MEAN
| Claim | Figure | Source | Context |
|---|---|---|---|
| Unplanned readmissions, insurer-partner programmes | Below 1% vs 8–15% industry | Inc42; Digital Health News; Entrepreneur India | First full year; population and definition not given |
| Average hospital stay | 40% shorter | Same | Case mix not given |
| Members kept out of hospital | Over 200 | Inc42; Indian Retailer | Counterfactual not given |
| Estimated insurer savings | ₹15–16 Cr (Digital Health News, Entrepreneur India) or over ₹50 Cr (TechCrunch, ₹500m) | As stated | Sources conflict by more than threefold |
| Patient satisfaction | 97% | Even hospital site | Survey method not given |
| RUPEIA READ Low readmissions are meaningful only if the patients treated resemble the ones used for the 8–15% benchmark. A hospital that treats fewer high-risk cases will show lower readmission without being better. The savings claim varies from ₹15–16 crore to over ₹50 crore across outlets; the company has not explained the gap. These numbers describe the intention of the model, not its audited effect. |
|---|
15 MARKET CONTEXT: INDIAN HOSPITALS AND CASHLESS INSURANCE
ICRA's sector updates (2026) show listed hospital chains growing revenue about 16% in H1 FY26 with occupancy of 63.3% and ARPOB up 7.8%, and project 13–15% revenue growth in FY2027. Private insurance now accounts for roughly 30–43% of revenue at chains such as Apollo and Max, up from about 20–25% a few years ago (sector commentary). Nearly 70% of private hospital beds sit in urban areas. Manipal reportedly runs 49 hospitals with more than 12,600 beds.
| Date | Event | Why it matters for Even |
|---|---|---|
| Jan 2024 | IRDAI "cashless anywhere" initiative | Raises expectation of cashless treatment at any hospital |
| 17 Feb 2025 | CARE Health halts cashless claims at all 12 Max hospitals in Delhi-NCR | Insurer-hospital price disputes are a live risk |
| 1 Sep 2025 | AHPI tells members to suspend cashless treatment for Bajaj Allianz; later restored | A hospital owner depends on insurer relationships |
| 2024 circular | Pre-authorisation within one hour; discharge within three hours | Speed rules raise insurer-facing workload |
| RUPEIA READ Insurer-hospital disputes show why an owner-operator that also designs the insurance programme could be valuable and why it is hard. If insurers resist paying for prevention that is hard to measure, Even's insurer half may remain small, and its hospitals will be priced like any other private hospital. Even says most of its revenue already comes from patients paying for treatment (TechCrunch). |
|---|
16 COMPETITIVE LANDSCAPE
| Peer | Model | Published scale | Contrast with Even |
|---|---|---|---|
| Manipal Hospitals | Large chain | 49 hospitals, 12,600+ beds (2026) | Scale and brand; fee-for-service |
| Max Healthcare | Premium chain | Occupancy typically 65–70% (aggregator) | Insurance-heavy, high ARPOB |
| Narayana Health, Aster | Cost-efficient chains | Bengaluru presence; no city-level figures read | Volume, not membership |
| Portea | Home healthcare | FY25 revenue ₹160 Cr; loss narrowed (Entrackr) | Home-based; no hospitals |
| MediBuddy | Digital health and insurance services | FY25 revenue ₹725 Cr; loss down 37% (Medial summary of Entrackr) | Platform; no hospitals |
No source read gives market-share or per-hospital competitor data for Bengaluru. Even's declared target, a hospital within five kilometres of every member, is a bet on density in one city before competing elsewhere. Banerjee said about 85–90% of members who live near an Even hospital choose it.
17 WHAT EVEN HAS NOT DISCLOSED
| Item | Status in published material |
|---|---|
| FY26 revenue, loss and balance sheet | Not yet filed (Entrackr, October 2026) |
| Bed count of the HBR Layout hospital | Not stated in any source read |
| Opening dates and sites for planned hospitals beyond Indiranagar | Not stated |
| Names of insurer partners | Not named in any report |
| Number of paying versus covered members | Not stated |
| Number of B2B clients | Not stated in sources read; a 2025 aggregator mention of about 200 clients is not company-confirmed |
| Hospital-level revenue, occupancy and profit | Not stated; profit claim is "excluding depreciation" and without figures |
| Series B pre-money price, cap table and preference terms | Not stated; only the August 2026 tranche price (₹10,889.91) is public |
| Entity-level reconciliation of US$28–30m revenue run-rates with RoC revenue | Not stated |
Each gap is stated plainly because the same facts are commonly misquoted. The most consequential for pricing a secondary share is the last two: the Series B terms and the difference between "run-rate" and filed revenue.
18 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Red flag | Evidence | Severity | Kill condition | What would resolve it |
|---|---|---|---|---|
| Loss vs revenue | FY25 loss ₹90.15 Cr on ₹25.43 Cr revenue | HIGH | FY26 loss exceeds revenue growth | Audited FY26 with loss ratio falling |
| Capital intensity | 20-year leases; US$3.5m fit-out per hospital | HIGH | A new hospital stays below break-even occupancy past year two | Hospital-level cash payback disclosed |
| Unreconciled rollout plan | Five hospitals in six months vs one plus three by FY27 | MEDIUM | Openings slip beyond FY27 | Named sites, bed counts and dates |
| Claims from the company only | Readmissions, profit, members, savings | MEDIUM | Independent audit contradicts them | Clinical audit; definitions published |
| Restructuring execution | 350 roles cut in August 2026 | MEDIUM | Clinical attrition or service lapses | Stable staffing at the new hospitals |
| Insurer half unproven | No insurer named; model "could compensate" | MEDIUM | No insurer pays for prevented admissions | Named insurer contract |
| Investor concentration | Khosla supplied 69.6% of the August tranche | LOW-MED | Lead investor steps back | Broader syndicate in the next round |
19 SCENARIO ANALYSIS: FY27 AND BEYOND
| Scenario | What happens | Implication |
|---|---|---|
| Bull | Four to five new hospitals open on schedule, reach break-even in a year; FY26 filings show revenue several times FY25 | Series C at a higher valuation; model replicated in a second city |
| Base | Two to three hospitals open by end-FY27; losses stay near ₹90 Cr as revenue climbs | Flat-to-modest step-up; capital raised again within 18 months |
| Bear | New hospitals ramp slowly under heavy lease costs; insurer deals do not materialise | Down round or sale to a hospital chain |
Scenarios are for discussion. They are not forecasts and use no unpublished Even data.
20 INVESTOR CLASS ANALYSIS
For HNIs
Even is unlisted and shares trade only in rare private secondaries, such as the US$0.5m employee-option buyback reported in March 2025. The October 2026 round at about US$300 million is the reference price, and it came with no audited FY26 numbers.
For family offices
Family offices interested in healthcare infrastructure may prefer a co-investment in the hospital build-out. Lease terms and unit-level returns matter more than the headline valuation.
For institutions
Growth and healthcare funds are the natural next investors. A pre-IPO round is unlikely before a clear path to hospital-level profit is audited.
For NRIs
NRIs can buy unlisted Indian shares subject to FEMA pricing and reporting rules.
21 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| An outcomes-focused private hospital operator | EVEN | Salaried-doctor model; Khosla-backed; two profitable-before-depreciation sites (company) | Loss-making group; no FY26 numbers |
| Listed hospital exposure | Listed hospital chains | Audited results and liquidity | Different model, higher valuations |
| A consumer-fintech growth story | SCAPIA (Report 19) | Rewards-led travel cards | Also loss-making |
22 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| Late 2026 | FY26 financial statements filed with the Registrar of Companies | First view after the pivot and layoffs |
| Dec 2026–FY27 | Indiranagar and other hospital openings | Tests the six-month versus FY27 timelines |
| 2027 | Named insurer agreement | Evidence that the payer half can be monetised |
| 2027 | Hospital-level occupancy and profit | Moves the profit claim from company statement to evidence |
23 HOW EVEN COMPARES WITH OTHER REPORTS IN THIS SERIES
| Measure | Even (Report 20) | Scapia (Report 19) | DailyObjects (Report 10) |
|---|---|---|---|
| Sector | Hospitals and managed care | Travel fintech | Design-led accessories |
| Latest round | US$50m, Oct 2026 | US$63m, May 2026 | ₹332 Cr, Oct 2026 |
| Valuation | About US$300m (₹2,895 Cr) | Over US$500m (about ₹4,825 Cr) | About ₹1,050 Cr |
| Latest published revenue | ₹25.43 Cr (FY25) | ₹29 Cr (FY25) | About ₹110 Cr (FY25) |
| Latest published loss | ₹90.15 Cr (FY25) | ₹83 Cr (FY25) | ₹15.9 Cr (FY25) |
| Valuation to FY25 revenue | About 114x | About 166x | About 9.5x |
| Capital need | Leases and equipment for each hospital | Rewards and people | Stores and inventory |
| RUPEIA READ Even and Scapia are priced on a future that is more than 100 times last year's published revenue, and both lose three to four rupees for every rupee earned. DailyObjects is priced at under ten times. The difference is not only sector. It reflects how much of the investment thesis rests on a step-change in unit economics. In Even's case that step-change is concrete (a hospital that fills its beds) and measurable within a year per site; in Scapia's it depends on partner banks and rewards cost, which are harder to see. |
|---|
24 RUPEIA FINAL INDEPENDENT VIEW
Even has the ingredients of a serious attempt at a better Indian hospital: salaried doctors, an owner-operator structure, a lead investor that has backed it in every priced round since 2021, and a stated discipline of measuring readmissions and stays. Its October 2026 round of US$50 million, at a reported US$300 million valuation, funds the build-out of a hospital network in the city where it already has members.
What the published record does not yet show is that the business pays for itself. FY25 revenue was about ₹25–27 crore against a loss of ₹90 crore; the company cut about 350 jobs two months before announcing the round; and the clinical and profitability claims come from the company. The model deserves attention. It does not yet deserve a conclusion.
| THE RUPEIA NUMBER ₹90.15 crore: Even's FY25 net loss, 3.5 times its revenue. |
|---|
| RUPEIA VERDICT A well-backed, capital-intensive pivot to hospitals. For secondary buyers, the October 2026 round is a ceiling reference until FY26 accounts and hospital-level numbers appear. For long-term investors, the key tests are occupancy and break-even at the new sites and a named insurer contract. |
|---|
Frequently asked questions
How much did Even Healthcare raise in its Series B?
US$50 million (about ₹475 crore), announced on 19 October 2026, led by existing investor Khosla Ventures with Alpha Wave. It was an all-equity primary round. A filing-based tranche of ₹208.24 crore (about US$22 million) was reported in August 2026.
What is Even Healthcare's valuation?
About US$300 million according to Even, as reported by TechCrunch. The company said its valuation tripled in 18 months. Entrackr, citing TheKredible, estimated about ₹753 crore (US$91 million) in August 2024.
What is Even Healthcare's revenue?
FY25 revenue was ₹25.43 crore (Entrackr, October 2026) or ₹27.2 crore (Entrackr August 2026; TechCrunch). FY24 was ₹6.24 crore or ₹8.3 crore depending on the article. FY26 has not been filed.
Is Even Healthcare profitable?
The group is not. FY25 net loss was ₹90.15 crore, up 24.5% from ₹72.40 crore. The founder told TechCrunch both hospitals reached operating profitability, excluding depreciation, within a year of opening.
Who founded Even Healthcare?
Mayank Banerjee, Matilde Giglio and Alessandro Ialongo, in Bengaluru, in 2020 or 2021 depending on the source.
How many hospitals does Even have?
Two, at Race Course Road and HBR Layout in Bengaluru, with five more planned. Indiranagar is named as the next. Sources differ on whether five open within six months or one by end-2026 and three more by end of FY27.
Why did Even lay off employees in 2026?
Entrackr reported about 350 layoffs (30–35% of staff) in August 2026 as the company reduced costs and scaled back its insurance business. The founder acknowledged the restructuring and said staff received severance, extended health insurance and accelerated vesting.
How much has Even raised in total?
Over US$120 million per the company coverage. Medical Dialogues put it at about US$72.5 million across five rounds before the Series B. The headline rounds add to more than that and the sources do not reconcile them.
Can individuals buy Even shares?
Even is unlisted. Shares change hands only in private secondary transactions. NRIs can buy subject to FEMA rules.
Source log
Inc42: Even Healthcare raises $50 Mn to expand hospital network across Bengaluru
TechCrunch: Khosla Ventures doubles down on Even Healthcare
Entrackr: Even Healthcare raises $50 Mn in Series B led by Khosla Ventures
Entrackr: Even Healthcare lays off 350 employees
Medical Dialogues: Even Healthcare to raise ₹208 Cr in Series B
Indian Retailer: Even Healthcare raises $50 Mn Series B
Digital Health News: Even Healthcare raises $50 Mn from Khosla Ventures
Entrepreneur India: Even Healthcare raises USD 50 Mn Series B
YourStory: Even Healthcare raises $50M in Series B
DealStreetAsia: Khosla Ventures leads $50m funding in Even Healthcare
ARR Club: Even Healthcare US$50M Series B
Wikipedia: Even Healthcare
Entrackr: Even Healthcare scoops up $30 Mn in Series A
Entrackr: Even Healthcare raises $20 Mn led by Khosla Venture
TheBioStartups: Even Healthcare secures additional funding of $15M
Digital Health News: Even Healthcare steps into hospital business
DealStreetAsia: Khosla Ventures leads $30m funding in Even Healthcare
Moneycontrol: Even Healthcare raises $20 million from existing investors
ThePrint: Even Healthcare makes preventive care affordable (2022 release)
Even Hospital: hospitals.even.in
Entrackr: Portea posts ₹160 Cr revenue in FY25
ICRA: Hospital sector, strong demand and ARPOB rise support FY2027 revenue growth
IANS: India's hospital sector revenue to grow up to 20 pc in FY2027
India Med Today: Bajaj Allianz pledges direct payments amid cashless dispute
Digital Health News: No cashless claims for CARE Health policyholders at Max Hospitals
Startup Talky: Daily Indian funding roundup, 19 October 2026
Multiples: Even revenue, valuation, funding and investors
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|