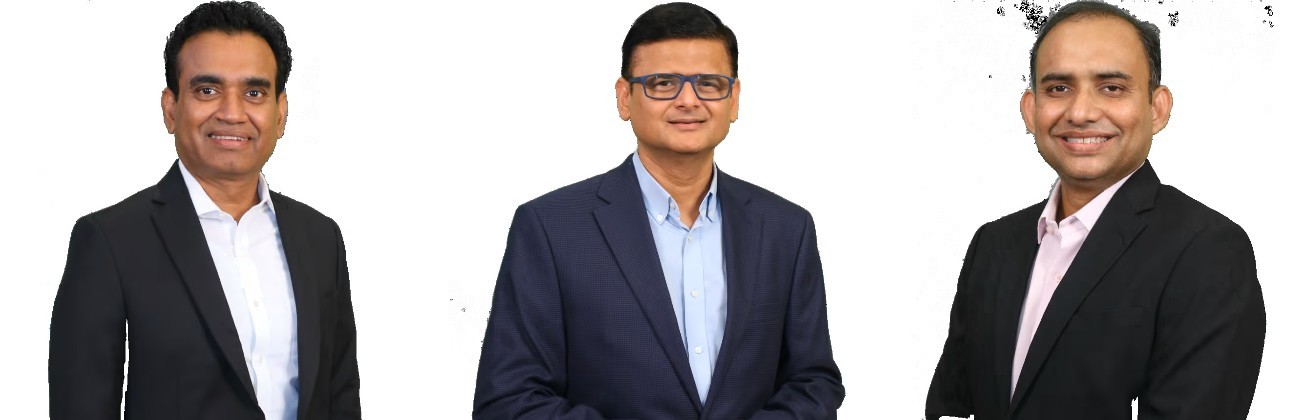
| MANAGER | Inflexor Ventures (Inflexor Capital Advisors LLP), set up in India in 2015 · over US$120m under management · 27 portfolio companies (Inc42; Venture Intelligence says over 25) across its funds |
|---|
| FUND | Inflexor Technology Discovery Fund (Fund III) · first close ₹400 Cr (~US$41.8m) on 28 Jul 2026 · target ₹1,250 Cr (~US$135m) |
| ANCHORS NAMED | Self-Reliant India (SRI) Fund, HDFC Asset Management Company, HDFC AMC Select AIF FoF · Asian Infrastructure Investment Bank (AIIB) approved up to the lower of US$7m and 10% of the fund (5 Aug 2026) |
| STRATEGY | Pre-Series A and Series A, Series A prioritised · initial cheques ₹15–45 Cr · 22–25 companies · IP-led deep tech |
| EARLIER FUNDS | Fund I ₹75 Cr (2015) · Fund II Inflexor Technology Fund over ₹600 Cr (2021) · Opportunities Fund I ₹280 Cr first close (Nov 2024) bought Fund I's portfolio |
| TEAM | Venkat Vallabhaneni and Jatin Desai (founder and managing directors), Pratip Mazumdar (co-founder and partner), partners Murali Krishna Gunturu and Harsha Mundhada |
| GAP TO TARGET | ₹850 Cr (68%) still to raise |
| THE ACCESS POINT
Fund III is in its fundraising phase after a first close, so subscriptions are still being accepted from institutions, family offices and HNIs at the AIF minimum of ₹1 crore. Earlier funds are closed. Inflexor has said it began deploying from the first close. |
|---|
Executive decision summary
| THE BOTTOM LINE | Inflexor is one of India's longest-running deep-tech venture managers, with three funds, a ₹600 crore-plus second fund and a 2024 Opportunities Fund that bought out its first fund's LPs. Fund III reached a ₹400 crore first close in July 2026, against a ₹1,250 crore target, with unusually strong institutional anchors: the government-backed SRI Fund, HDFC AMC and, through an approval dated 5 August 2026, the Asian Infrastructure Investment Bank. The manager focuses on pre-Series A and Series A companies with proprietary technology and writes ₹15–45 crore initial cheques. What stands out is the quality of the LP list and the breadth of the portfolio of about 27 companies. What is thin is published return data: Inflexor has not released fund-level IRR, DPI or TVPI for Funds I or II, and press counts of exits range from one to more than fourteen. The 2024 portfolio sale of Fund I is the clearest published sign of liquidity. |
|---|
| WHICH INVESTOR | Fund III fits you IF you want a specialist deep-tech Series A manager with institutional anchors, and you can accept that earlier funds' returns are not published.
Wait IF you need audited DPI or TVPI first. Fund II is a 2020–21 vintage still being held, and Fund I's result was realised through a portfolio sale whose price is not disclosed. |
| COMFORT FIT | Inflexor = a specialist workshop, not a department store. Science, engineering and technology companies with their own IP, rather than a spread of consumer apps.
The LP list = three stamps on one passport. SRI Fund (government-backed), HDFC AMC (India's largest fund house by assets) and AIIB (a multilateral development bank) each ran their own diligence.
Fund I's portfolio sale = selling a house to a related buyer. It gave early investors cash, but the price was set inside the Inflexor family, so outsiders cannot judge it.
Physis (Report 11) = the generalist cousin. Wider funnel, smaller cheques, no earlier fund. Inflexor writes bigger cheques into fewer, more technical companies. |
| THE RUPEIA NUMBER | 30 companies, 12 at seed. Inflexor's own portfolio page lists 30 companies across Funds I–III: 12 entered at seed, 3 at pre-Series A, 14 at Series A and 1 at Series A+. Fund III has so far listed three: Ayati Devices, Butterfly Learnings and Revspot. |
1 CLAIM REGISTER: EVIDENCE GRADING
A = government, regulator or multilateral-institution record. B = manager release or website. C = independent press. D = third-party database or blog.
| Claim | Source | Grade | Rupeia assessment |
|---|
| Fund III first close ₹400 Cr (28 Jul 2026), target ₹1,250 Cr | Inc42; DealStreetAsia; Venture Intelligence; YourStory | C | Established |
| Anchors: SRI Fund, HDFC AMC, HDFC AMC Select AIF FoF | YourStory; Venture Intelligence | C | Established |
| AIIB: lower of US$7m and 10% of total commitments; approved 5 Aug 2026; first disbursement Q3 2026 | AIIB project summary E0623I (6 Aug 2026) | A | Established |
| Manager: set up 2015; over US$120m AUM; 25+ portfolio companies | AIIB project summary | A | Established |
| Fund II final close over ₹600 Cr (2021) | DQ India; YourStory | C | Established |
| Opportunities Fund I first close ₹280 Cr; buys Fund I portfolio | Inc42 (6 Nov 2024) | C | Established |
| Portfolio: 30 companies by fund, stage and theme | Inflexor website | B | Established |
| Exit count (1, 3 or 14+) | CB Insights; Business Standard via Venture Intelligence; VCSheet | D | Conflicting; no manager figure published |
2 FUND SNAPSHOT: INFLEXOR FUND III VS THREE PEERS
| Measure | Inflexor Fund III | Physis Fund I (Report 11) | IITM Unicorn Frontier I (Report 01) | A91 Partners Fund III |
|---|
| Size | ₹1,250 Cr target; ₹400 Cr first close | ₹400 Cr final | ₹600 Cr base + ₹400 Cr greenshoe | US$665m final (Apr 2025) |
| Stage | Pre-Series A, Series A | Pre-Series A to Series B | Early deep tech | Growth |
| Cheque | ₹15–45 Cr | US$1–3m | Early | Larger growth cheques |
| Anchors | SRI Fund, HDFC AMC, AIIB | Insurer, family offices | IIT network, institutions | Global and domestic institutions |
| Prior funds | Three earlier vehicles since 2015 | None | Manager with three funds | Funds I (US$351m) and II (US$550m) |
| RUPEIA READ
Fund III is the second-largest early-stage target in this group after IITM's, and the only one with a multilateral bank as an LP. Its ₹15–45 crore cheque is about three to five times Physis's typical ticket, which signals that Inflexor wants to own meaningful stakes at Series A rather than spread small bets. |
|---|
3 TIMELINE: 2015–2026
| Date | Event |
|---|
| 2015 | First fund launched (₹75 Cr, reported as "Parampara"); Venkat Vallabhaneni and Jatin Desai among founders |
| Early 2020 | Inflexor Technology Fund (Fund II) launched |
| Aug 2020 | Fund II first close ₹230 Cr |
| Jul 2021 | Fund II final close, over ₹600 Cr against a ₹500 Cr domestic target; LPs include SBICap Ventures, SIDBI Fund of Funds for Startups and the Sumankant Munjal family office |
| Aug 2022 | Steradian Semiconductors sold to a Tokyo-listed Japanese company (CB Insights) |
| Oct 2024 | Plan reported for a third fund of ₹1,200–1,700 Cr; Inflexor typically invests US$1–2m at seed and US$3–4m at Series A |
| 6 Nov 2024 | Inflexor Opportunities Fund I first close ₹280 Cr (80% of ₹350 Cr target), led by HDFC AMC; buys Fund I's entire portfolio |
| Mar 2026 | Inflexor describes its deep-tech investing signals in a YourStory interview; two funds hold 27 companies |
| 11 May 2026 | AIIB final decision on the fund (initial working-group decision 25 Jul 2025) |
| 28 Jul 2026 | Fund III first close ₹400 Cr; target now ₹1,250 Cr |
| 5 Aug 2026 | AIIB financing approval; first disbursement expected Q3 2026 |
Sources disagree on when the firm began. AIIB says Inflexor was established in India in 2015; Inc42 says 2019. Rupeia uses the AIIB date, which is also the date DQ India gives for the first fund.
4 THE MANAGER AND ITS PHILOSOPHY
Inflexor Ventures describes its vision as "venture capital reimagined": backing founders who change industries through technology. Its investment philosophy is anchored in Science, Engineering and Technology (S.E.T.), meaning IP-led innovation that creates durable value. It screens each company on three questions: team (the founders' drive and insight into the problem), TAM (the size and scalability of the market) and technology (how defensible and unique the foundation is).
| Name | Title (Inflexor website) |
|---|
| Venkat Vallabhaneni | Founder and Managing Director |
| Jatin Desai | Founder and Managing Director |
| Pratip Mazumdar | Co-founder and Partner |
| Murali Krishna Gunturu | Partner |
| Harsha Mundhada | Partner |
| Anush Prem; Parmi Doshi | Principals |
| Aishwarya Kulkarni; Pratik Ahuja | Associates |
| Sachin Tripathi; Sandeep Naidu Kandipalli | Portfolio team: associate and head, strategic development |
| Minal Sequeira | Head, Finance and Compliance |
| Nirpam Agarwal | Compliance Officer, GIFT City IFSC operations |
| Simran Sarabjit Singh; Indresh Batra; Srikanth Tirumala | Senior ESG advisor; venture advisors |
| RUPEIA READ
The team page shows an investment team of nine, a separate portfolio-support team and a compliance function with a GIFT City officer. AIIB records that 53% of the team are women. For a fund of this size that is a full institutional set-up, and it is what multilateral LPs look for in diligence. |
|---|
5 GP QUALITY & TEAM ANALYSIS
| Dimension | Evidence | Rupeia view |
|---|
| Longevity | Active since 2015; three funds and an opportunities vehicle | Strong for Indian deep-tech VC |
| Thesis consistency | S.E.T. and IP-led companies across all funds | Consistent |
| Team depth | Five partners and principals plus portfolio and ESG support | Good |
| Disclosure of returns | No fund-level IRR, DPI or TVPI published | Weak |
| LP validation | SBICap, SIDBI FFS, HDFC AMC, SRI Fund, AIIB | Strong |
| Headquarters | Reported as Hyderabad (2024) and Bengaluru (2026) | Presence in both tech hubs |
Partner Pratip Mazumdar said of the opportunities fund that the first close within six months was "bolstered by a sizeable investment from HDFC AMC". Founder Venkat Vallabhaneni said of Fund III that it "reflects our conviction in this opportunity and our commitment to being long-term partners to exceptional founders".
6 FUND I (2015): THE FIRST ₹75 CRORE
DQ India reported in 2021 that the firm's first fund was launched in 2015 and invested in 12 startups. Venture Intelligence described it as a ₹75 crore fund. The two published lists of its companies differ: DQ India names PlayShifu, Atomberg, Entropik, Bellatrix and CloudSEK, while the Inflexor website tags Atomberg, Bellatrix and PlayShifu as Fund I and II companies and lists Chakr Innovation, CloudSEK, Data Resolve, Entropik, Practically, S-Cube, SecureTime, Singularity and Verloop as Fund I.
| Fund I company (website) | Theme | Entry stage |
|---|
| Atomberg Technologies | Consumer tech (energy-efficient appliances) | Seed (Funds I and II) |
| Bellatrix Aerospace | Energy (satellite propulsion) | Seed (Funds I and II) |
| PlayShifu | Consumer tech (AR educational toys) | Seed (Funds I and II) |
| Chakr Innovation | Sustainability | Seed |
| CloudSEK | Digital infrastructure (cybersecurity) | Seed |
| Entropik | Digital infrastructure (AI emotion recognition) | Seed |
| Practically | Digital infrastructure | Seed |
| Singularity | Digital infrastructure | Seed |
| Data Resolve | Digital infrastructure | Series A |
| S-Cube | Digital infrastructure | Series A |
| SecureTime | Digital infrastructure | Series A |
| Verloop | Digital infrastructure | Series A |
| RUPEIA READ
The Fund I list includes Atomberg, which has since filed for an IPO (Report 41), and Bellatrix, a satellite-propulsion company. Those are the kind of IP-led outcomes the thesis targets. The fund returned capital through the 2024 portfolio sale to the Opportunities Fund, not through trade sales or listings, so the market has not yet priced the Fund I portfolio independently. |
|---|
7 FUND II (2020–21): THE ₹600 CRORE-PLUS VINTAGE
| Fund II fact | Published detail (DQ India, July 2021) |
|---|
| Name | Inflexor Technology Fund |
| Launch | Early 2020 |
| First close | ₹230 Cr, August 2020 |
| Final close | Over ₹600 Cr, against an initial domestic target of ₹500 Cr |
| LPs named | SBICap Ventures; SIDBI (Fund of Funds for Startups); Survam (Sumankant Munjal family office); other family offices and founders of technology companies |
| Cheques | ₹5–20 Cr initial, pre-Series A to Series B, with follow-ons |
| Plan | About 25 startups over three to four years |
| Companies at July 2021 | Steradian Semiconductors, PlayShifu, Vitra.ai, Kale Logistics |
Fund II companies on the Inflexor website include A5G Networks, Awiros, Ayna, ClickPost, CredFlow, GramCover, Kale Logistics, Morphle, NoPo, SecureThings, Steradian Semiconductors, Terra, Vitra AI and Ykrita, plus the three shared with Fund I. Fund II closed in the second wave of COVID-19 and was oversubscribed against its domestic target.
| RUPEIA READ
Fund II raised twice Fund I's scale in one step, and it is the vintage that tests Inflexor. Its marks and distributions will decide how Fund III is received by institutions beyond the three anchors. Steradian's 2022 sale to a Japanese listed company is the one exit named in press. |
|---|
8 THE OPPORTUNITIES FUND: HOW FUND I WAS SOLD
On 6 November 2024 Inflexor announced the first close of Inflexor Opportunities Fund I at ₹280 crore ($33.73 million), 80% of its ₹350 crore target, led by HDFC AMC with HNIs, family offices, corporates and institutions. The fund buys the entire investment portfolio of Fund I from its investors, giving them liquidity, and keeps part of its capital to maintain or increase stakes over three to five years. Fund I investors that exited included IDFC Limited and the Sumankant Munjal family office.
| Feature | Detail |
|---|
| Target / first close | ₹350 Cr / ₹280 Cr |
| Lead | HDFC AMC |
| Seller | Fund I investors |
| Buyer | New investors in the Opportunities Fund, managed by Inflexor |
| Follow-on use | Three to five years of reserves for Fund I companies |
| Time to first close | About six months (Mazumdar) |
| RUPEIA CALCULATION
Portfolio sales between funds managed by one team are common in Indian venture when a fund reaches the end of its life. They give sellers cash and buyers a mature portfolio. The price is the issue: the buyer and the seller share a manager, so independent valuation matters. HDFC AMC leading the buying side is itself an independent check, since an institution with its own credit and valuation teams priced the entry. The published ₹280 crore buying commitment, against Fund I's ₹75 crore size, implies that the Fund I portfolio was valued at a large multiple of cost, though no price has been disclosed. |
|---|
9 WHY A PORTFOLIO SALE: THE END-OF-LIFE PROBLEM IN INDIAN VENTURE
Indian venture funds from 2015 reach the end of their ten-year terms in 2025–26 with many companies still private. Managers have three options: extend the fund, sell stakes company by company, or sell the whole portfolio to a new vehicle. Inflexor chose the third for Fund I, a ₹75 crore fund with 12 companies, and attracted HDFC AMC as the lead buyer.
| Option for an ageing fund | Advantage | Drawback |
|---|
| Extend the term | No forced sale | Investors wait longer; fees may continue |
| Sell company by company | Market-tested prices | Slow; hard for minority stakes in private companies |
| Sell the portfolio to a continuation fund | Clean cash exit for existing LPs; follow-on capital for the winners | Price set with a related buyer; needs independent institutional buyers |
| RUPEIA READ
Continuation-style deals are becoming a standard Indian tool as the 2014–2016 vintages mature. Inflexor's version is notable for the buyer: HDFC AMC led it, and 80% of the target was raised within about six months. That gives the transaction more credibility than a purely internal transfer, though the sale price has not been published. |
|---|
10 FUND III: STRUCTURE AND STRATEGY
| Parameter | Published detail |
|---|
| Name | Inflexor Technology Discovery Fund |
| First close | ₹400 Cr (~US$41.8m), 28 Jul 2026 |
| Target | ₹1,250 Cr (~US$135m); earlier plan (Oct 2024) was ₹1,200–1,700 Cr |
| Anchors | SRI Fund; HDFC AMC; HDFC AMC Select AIF FoF; AIIB (approved 5 Aug 2026) |
| Stage | Pre-Series A and Series A; Series A prioritised |
| Initial cheque | ₹15–45 Cr |
| Companies | 22–25 |
| Focus | Science, engineering and technology; IP-led companies; sector-agnostic with high entry barriers |
| Deployment | Started after the first close in selected opportunities |
| Portfolio so far | Ayati Devices (Series A), Butterfly Learnings (Series A+), Revspot (Series A) |
| RUPEIA READ
The cheque size has grown with the fund. Fund II wrote ₹5–20 crore; Fund III writes ₹15–45 crore. With 22–25 companies at an average of about ₹40–45 crore each including follow-ons, a full ₹1,250 crore fund would be mostly invested in the companies already at Series A. At the ₹400 crore first close, the fund can fund roughly eight to ten initial cheques. |
|---|
11 FUND II VS FUND III: WHAT HAS CHANGED
| Measure | Fund II (2020–21) | Fund III (2026) | Change (Rupeia calculation) |
|---|
| Final or target size | Over ₹600 Cr final | ₹1,250 Cr target | ~2.1x |
| First close | ₹230 Cr | ₹400 Cr | ~1.7x |
| Initial cheque | ₹5–20 Cr | ₹15–45 Cr | ~3x at both ends |
| Stage | Pre-Series A to Series B | Pre-Series A and Series A, Series A prioritised | Narrower and later |
| Companies planned | About 25 | 22–25 | Same count, larger tickets |
| Named institutional LPs | SBICap Ventures, SIDBI FFS | SRI Fund, HDFC AMC (two routes), AIIB | Broader and larger |
| Pre-close fundraising | Closed during the second COVID wave | First close after a 2025 plan of ₹1,200–1,700 Cr | Target trimmed |
| RUPEIA READ
Fund III is a bigger bet on fewer, later and more mature companies. Larger Series A cheques reduce the number of companies that must succeed, but they raise the price paid per company. That makes entry valuations and ownership percentages the main drivers of Fund III's outcome. |
|---|
12 THE ANCHORS IN DETAIL: SRI FUND, HDFC AMC AND AIIB
| Anchor | What it is | Why it matters |
|---|
| Self-Reliant India (SRI) Fund | Government-backed fund of funds for MSMEs, managed by NSIC Venture Capital Fund Ltd (SIDBI-linked) | State validation; also named as an anchor in other 2026 Indian venture funds |
| HDFC Asset Management Company | One of India's largest asset managers; also led the Opportunities Fund | Repeat institutional backer across two Inflexor vehicles |
| HDFC AMC Select AIF FoF | HDFC AMC's fund of funds for alternative funds | Second HDFC route into the fund |
| AIIB | Multilateral development bank; project E0623I under its Venture Capital Program for Green and Technology-Enabled Infrastructure | Lower of US$7m or 10% of fund commitments; first disbursement expected Q3 2026 |
AIIB's project summary states that the fund seeks to support innovation-driven, technology-enabled infrastructure in India by catalysing early-stage deep-tech investment and mobilising private capital. It classes the project as Category FI (a financial intermediary), excludes all Category A investments and any that trigger its standards on land acquisition and Indigenous Peoples, and requires an environmental and social management system to be in place before the first capital call. Intermediate indicators include the share of invested capital in climate mitigation or adaptation, the number of portfolio companies with women in senior roles and the number listed on AIIB's InfraTech Portal.
| RUPEIA CALCULATION
At 10% of ₹1,250 crore (about US$129 million at ₹96.5 per US$), the cap would be about US$12.9 million, so the US$7 million limit is the binding one. AIIB's maximum is therefore about 5.4% of a fully raised fund, or about 17% of the ₹400 crore first close (US$41.8m). Its approval dates run from a working-group decision on 25 July 2025 to financing approval on 5 August 2026, which is more than a year of diligence. |
|---|
13 AIIB'S CONDITIONS: WHAT THE BANK REQUIRES OF THE FUND
| AIIB requirement (project summary) | Practical meaning for Inflexor |
|---|
| Excludes all Category A sub-projects and any trigger of land-acquisition or Indigenous Peoples standards | Heavy-footprint infrastructure and mining-type investments are out; fits a software and hardware portfolio |
| Environmental and social management system updated before the first capital call | Inflexor must have its ESG framework in place first |
| Publication of the summarised system and of investment names, locations and sectors within 12 months of financial close | Portfolio disclosure becomes a contractual duty |
| Grievance mechanism for the fund and portfolio companies | Companies must set up a disclosed grievance channel |
| Right to excuse itself from any investment that fails its policies | AIIB can opt out company by company |
| Indicators: private capital mobilised per Inflexor dollar; share of capital in climate-related activity; women in senior roles; listing on the InfraTech Portal | Impact reporting adds a layer beyond financial returns |
| RUPEIA READ
Multilateral LPs bring discipline as well as capital. The 12-month disclosure duty means Fund III LPs and the public will eventually see a full company list with sectors, which will answer part of today's transparency gap. The climate and infrastructure indicators also steer the portfolio towards companies with measurable technology impact, consistent with Inflexor's existing mix of energy, transport and sustainability names. |
|---|
14 PORTFOLIO MAP: 30 COMPANIES BY THEME, FUND AND STAGE
| Theme (Inflexor website) | Companies | Count |
|---|
| Digital infrastructure | A5G Networks, Awiros, Ayati Devices, Ayna, Butterfly Learnings, CloudSEK, Data Resolve, Entropik, Morphle, Practically, Revspot, S-Cube, SecureThings, SecureTime, Singularity, Verloop, Vitra AI, Ykrita | 18 |
| Transportation | ClickPost, Kale Logistics, Steradian Semiconductors | 3 |
| Consumer tech | Atomberg Technologies, PlayShifu, Terra | 3 |
| Energy | Bellatrix Aerospace, NoPo | 2 |
| FinTech | CredFlow, GramCover | 2 |
| Sustainability | BioPrime, Chakr Innovation | 2 |
| Entry stage | Companies | Count |
|---|
| Seed | Atomberg, Ayna, Bellatrix, Chakr, CloudSEK, Entropik, NoPo, PlayShifu, Practically, Singularity, Terra, Vitra AI | 12 |
| Pre-Series A | A5G Networks, BioPrime, Steradian | 3 |
| Series A | Awiros, Ayati Devices, ClickPost, CredFlow, Data Resolve, GramCover, Kale, Morphle, Revspot, S-Cube, SecureThings, SecureTime, Verloop, Ykrita | 14 |
| Series A+ | Butterfly Learnings | 1 |
| Fund tag | Count |
|---|
| Fund I only | 9 |
| Fund I and II | 3 |
| Fund II only | 14 |
| Fund III | 3 |
| No fund tag shown (BioPrime) | 1 |
| RUPEIA CALCULATION
Three in five companies (18 of 30) are digital infrastructure: cybersecurity, AI, telecom, data and enterprise software. Fund III's three disclosed holdings follow the same pattern, but at Series A or later, where Inflexor's average entry has been moving. The portfolio is also moving away from seed: 12 of the 27 Fund I and II companies entered at seed, while all three Fund III companies shown are Series A or later. |
|---|
15 SELECTED PORTFOLIO COMPANIES: WHAT THEY DO
| Company | What it does (published description) | Fund(s) |
|---|
| Atomberg Technologies | Energy-efficient smart appliances maker; IPO filed (Report 41) | I and II |
| Bellatrix Aerospace | Satellite propulsion systems | I and II |
| PlayShifu | Augmented-reality educational toys | I and II |
| CloudSEK | Cybersecurity | I |
| Entropik | AI-based emotion-recognition platform | I |
| Steradian Semiconductors | AI-based sensing for autonomous vehicles; sold to a Tokyo-listed company | II |
| Vitra AI | AI and machine-learning content translation platform | II |
| Kale Logistics | AI and blockchain-enabled logistics technology | II |
| ClickPost; CredFlow; GramCover | Logistics software; business-to-business credit technology; rural insurance distribution (theme tags: transportation, FinTech) | II |
| RUPEIA READ
These are IP-heavy, product-first companies. Several (Atomberg, CloudSEK, Bellatrix, Steradian) now have visible scale or exits, which is the evidence behind Inflexor's claim of backing S.E.T. companies early. The weaker part of the picture is that press counts of Inflexor exits range from one (CB Insights) to three (Business Standard) to more than fourteen (VCSheet), and the manager has not published its own count. |
|---|
16 WHAT IT TAKES TO RETURN 3X: FUND MATHS
Inflexor has not published fees or terms. The table uses illustrative assumptions, labelled as such.
| Step (Rupeia calculation, full ₹1,250 Cr fund) | Illustrative figure |
|---|
| Fund size | ₹1,250 Cr |
| Fees and expenses over life (assumed ~15%) | ~₹190 Cr |
| Investable capital | ~₹1,060 Cr |
| Net 3x to LPs | ₹3,750 Cr |
| Gross proceeds needed (allowing ~20% carry on gains) | ~₹4,400 Cr |
| Required gross multiple on invested capital | ~4.2x |
| Per company, 22–25 companies | Average ~₹44 Cr invested; ~₹180–200 Cr proceeds each |
| Route to ~₹4,400 Cr | What it requires |
|---|
| Two fund-returners | Two stakes worth ~₹1,000 Cr each; at 8% ownership, companies valued at ~₹12,500 Cr (~US$1.3bn) at exit |
| Plus four strong exits | Four stakes worth ~₹400 Cr each; at 8% ownership, companies at ~₹5,000 Cr |
| Plus the rest | ~₹800 Cr from the remaining 16–19 companies |
| RUPEIA CALCULATION
A 3x net result on a ₹1,250 crore fund needs two unicorn-scale exits and several mid-sized ones from 22–25 companies. That is a high bar for Indian deep tech, where Atomberg's listing and a handful of acquisitions are the main precedents. If the fund closes at only ₹800 crore, the number of required big exits falls to about one and a half, so a smaller final close is not necessarily a weaker outcome per rupee. |
|---|
17 GROSS TO NET TO POST-TAX: WHAT AN LP KEEPS
| Step (₹1 Cr commitment, illustrative) | Amount |
|---|
| Gross multiple on invested capital | 4.2x |
| Distributions after ~15% fees and ~20% carry | ~₹3.0 Cr (3.0x) |
| Gain | ~₹2.0 Cr |
| Tax at 12.5% on long-term capital gains on unlisted shares (before surcharge and cess) | ~₹0.25 Cr |
| Post-tax proceeds | ~₹2.75 Cr |
Tax treatment depends on the vehicle. Inflexor's fund operations include a GIFT City compliance officer, which suggests an IFSC vehicle for some investors; tax outcomes for a GIFT City feeder differ and are not published.
18 FUNDRAISING PATH: A FIRST CLOSE AT 32% OF TARGET
| Measure | Figure (Rupeia calculation) |
|---|
| First close ÷ target | ₹400 Cr ÷ ₹1,250 Cr = 32% |
| Remaining | ₹850 Cr (68%) |
| Fund II, first close ÷ final | ₹230 Cr ÷ over ₹600 Cr = about 38% |
| Opportunities Fund, first close ÷ target | ₹280 Cr ÷ ₹350 Cr = 80% |
| Change in target since Oct 2024 | From ₹1,200–1,700 Cr to ₹1,250 Cr |
| RUPEIA READ
A 32% first close is in line with Fund II's history (about 38% at first close, ending above target). The target has settled at the lower end of the 2024 range, which is realistic in a year when many Indian VC funds have raised below their targets. The first-close mix is high quality (government, HDFC, AIIB), so remaining closes will test whether private institutions and family offices join. |
|---|
19 MARKET CONTEXT: DEEP-TECH AND EARLY-STAGE FUNDING
| Indicator (Tracxn, India tech, 2025) | Figure |
|---|
| Seed funding | US$1.1bn, down 30% |
| Early-stage funding | US$3.9bn, up 7% |
| Late-stage funding | US$5.5bn, down 26% |
| Total funding | US$10.5bn, down 17%; India third globally |
Series A is Inflexor's main stage, and early-stage funding was the only stage that grew in 2025. Policy support for deep tech has risen too: the SRI Fund and AIIB's venture programme both name technology-enabled infrastructure, and a record 18 startup IPOs in 2025 raised about ₹41,248 crore, which supports the exit case for IP-led companies such as Atomberg.
20 DEPLOYMENT AND OWNERSHIP MATHS AT THE FIRST CLOSE
| Step (Rupeia calculation) | At ₹400 Cr | At ₹1,250 Cr |
|---|
| Capital after ~15% fees and expenses | ~₹340 Cr | ~₹1,060 Cr |
| Reserve for follow-ons (assumed 40%) | ~₹136 Cr | ~₹424 Cr |
| Available for initial cheques | ~₹204 Cr | ~₹636 Cr |
| Initial cheques at ₹15–45 Cr (mid-point ₹30 Cr) | ~7 companies | ~21 companies |
| Ownership if a ₹30 Cr cheque buys 12% at a ₹250 Cr post-money Series A | 12% | 12% |
| Value of a 12% stake if the company exits at ₹3,000 Cr (diluted to ~8%) | ~₹240 Cr | ~₹240 Cr |
| RUPEIA CALCULATION
The 22–25 company plan needs the full ₹1,250 crore. At the first-close level, Fund III can make about seven initial investments, which is why the three disclosed holdings so far are consistent with early deployment. An exit at ₹3,000 crore returns about eight times the initial cheque after dilution in this illustration, so a handful of such outcomes can carry the fund. The calculation uses assumed valuations and fees, not published Inflexor terms. |
|---|
21 QUESTIONS A FIRST-TIME READER ASKS
| Question | Answer from the published record |
|---|
| Is Inflexor new? | No. It dates from 2015 on AIIB's record and runs its third fund plus an opportunities vehicle. |
| Who are the anchors? | SRI Fund, HDFC AMC, HDFC AMC Select AIF FoF and, by approval, AIIB. |
| What stage? | Pre-Series A and Series A, with Series A prioritised. |
| How big is each cheque? | ₹15–45 Cr initial. |
| How many companies? | 22–25 planned; 30 listed across all funds on the website. |
| Does it publish returns? | No fund-level IRR, DPI or TVPI. |
| Has any fund returned money? | Fund I investors were bought out through the Opportunities Fund in 2024; the price is not disclosed. |
| Where is it based? | Reported as Hyderabad in 2024 and Bengaluru in 2026; compliance operations in GIFT City. |
22 CAPABILITY MATRIX: YES / NO / PARTIAL
| Capability | Status | Evidence |
|---|
| Multi-fund track record | YES | Funds I and II plus Opportunities Fund |
| Institutional LP validation | YES | SRI Fund, HDFC AMC, AIIB, SIDBI FFS |
| Published fund-level returns | NO | No IRR, DPI or TVPI released |
| Realised liquidity | PARTIAL | Fund I portfolio sale; one named trade exit |
| Clear thesis | YES | S.E.T., IP-led |
| Full target raised | NO (yet) | 32% at first close |
| Environmental and social framework | YES | Required by AIIB before first capital call |
| Deal-by-deal portfolio disclosure | YES | 30 companies listed by fund, stage and theme |
23 RISK ANALYSIS: RED FLAGS & KILL CONDITIONS
| Risk | Evidence | Severity | Kill condition |
|---|
| Opaque track record | No fund returns published; exit counts 1 to 14+ | HIGH | Fund II marks flat or down by 2028 |
| Scale-up risk | Fund III is about 2x Fund II; cheques triple | MEDIUM | Series A entry valuations above sector norms |
| Fundraising gap | ₹850 Cr still to raise | MEDIUM | Final close below ₹800 Cr |
| Deep-tech timelines | IP-led companies take longer to reach revenue | MEDIUM | Two or more portfolio companies fail to raise follow-ons |
| Related-party pricing | Fund I sold to a fund with the same manager | MEDIUM | Further inter-fund sales without independent valuation |
| Concentration in digital infrastructure | 18 of 30 companies | LOW | Sector downturn hits several companies at once |
24 SCENARIO ANALYSIS
| Scenario | What happens | Fund III outcome (indicative) |
|---|
| Bull | Final close ₹1,250 Cr; two portfolio companies list; AIIB co-investment flows | 3x+ net |
| Base | Final close ₹800–1,000 Cr; a few strong exits; several stalls | 1.8–2.5x net |
| Bear | Final close near ₹600 Cr; deep-tech exits slow | Around 1x |
25 LP SIGNAL & RE-UP ANALYSIS
HDFC AMC has now backed Inflexor twice (Opportunities Fund and Fund III through two routes), and SIDBI's Fund of Funds is a Fund II investor. Repeat institutional LPs are the strongest public re-up signal Inflexor has.
| RUPEIA READ
Watch whether SIDBI FFS and the Munjal family office return in Fund III, and whether new LPs beyond the three anchors appear at the second close. |
|---|
26 INVESTOR CLASS ANALYSIS
| Investor | Fit | Why |
|---|
| HNI | PARTIAL | Deep-tech access via a known manager; accept long hold and limited return disclosure |
| Family office | YES | Co-investment and thematic alignment; strong anchor group |
| Institution | YES | Multilateral and government anchors reduce diligence risk |
| NRI | PARTIAL | AIF or IFSC route; paperwork |
27 COMFORT FIT: THE DECISION PAGE
| COMMIT TO FUND III IF | You want deep-tech Series A exposure from a manager with 11 years of history and institutional anchors, and can hold for 8–10 years. |
|---|
| WAIT IF | You need Fund II returns before committing, or want to see the second close. |
| AVOID IF | You need liquidity within five years or are uncomfortable with limited return disclosure. |
28 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|
| Q3–Q4 2026 | AIIB first disbursement; second close | Shows institutional demand |
| 2027 | Atomberg IPO outcome (Report 41) | Public-market read on an Inflexor company |
| 2027–2028 | Fund II marks and exits | Core evidence for Fund III LPs |
| By Dec 2027 | Final close | Whether the ₹1,250 Cr target is reached |
29 RUPEIA FINAL INDEPENDENT VIEW
Inflexor combines a clear thesis, an eleven-year history and an LP list that most Indian early-stage funds would envy: a government fund of funds, India's largest fund house and a multilateral bank. Fund III is sized for the opportunity and, at 32% raised, still has most of its fundraise ahead. The gap in the file is performance. Without published IRR or DPI, Fund III LPs rely on anchors' diligence, the Fund I portfolio sale and the visible success of companies such as Atomberg.
Rupeia's view: Fund III suits institutions and family offices that value deep-tech specialism and strong co-LPs. Less-experienced investors should wait for the second close and for Fund II marks.
Frequently asked questions
What is Inflexor Ventures Fund III?
Fund III, the Inflexor Technology Discovery Fund, is Inflexor's third fund. It reached a first close of ₹400 crore on 28 July 2026 against a ₹1,250 crore target and invests in pre-Series A and Series A deep-tech companies.
Who invested in Inflexor Fund III?
Named anchors are the Self-Reliant India (SRI) Fund, HDFC AMC and HDFC AMC Select AIF FoF. The Asian Infrastructure Investment Bank approved a commitment of the lower of US$7 million and 10% of total fund commitments on 5 August 2026.
How much will Inflexor invest per company?
Initial cheques of ₹15–45 crore into 22–25 companies, with follow-ons reserved.
What did Inflexor's earlier funds raise?
Fund I was about ₹75 crore (2015). Fund II, the Inflexor Technology Fund, closed above ₹600 crore in 2021. Inflexor Opportunities Fund I raised ₹280 crore at first close in November 2024.
Which companies has Inflexor backed?
Inflexor lists 30, including Atomberg, Bellatrix Aerospace, PlayShifu, CloudSEK, Entropik, Verloop, ClickPost, Kale Logistics and Steradian Semiconductors. Fund III names Ayati Devices, Butterfly Learnings and Revspot.
Has Inflexor published returns?
No fund-level IRR, DPI or TVPI is published. Fund I was sold to the Opportunities Fund in 2024, and press reports of exits range from one to more than fourteen.
Who runs Inflexor?
Venkat Vallabhaneni and Jatin Desai are founders and managing directors; Pratip Mazumdar is co-founder and partner; Murali Krishna Gunturu and Harsha Mundhada are partners.
Can individuals invest in Inflexor Fund III?
Through the AIF route with a minimum commitment of ₹1 crore, while the fund is still raising.
Source log
YourStory: Inflexor Ventures raises ₹400 Cr as first close of Fund III (Jul 2026)
Inc42: Inflexor Ventures marks first close of Fund III at ₹400 Cr
DealStreetAsia: Inflexor Ventures makes first close of US$135m Fund III
Venture Intelligence: Inflexor raises ₹400 Cr in first close of ₹1,250 Cr third fund
Venture Intelligence: Inflexor looks to raise ₹1,700 Cr for third fund (Oct 2024)
AIIB: Project summary, Inflexor Technology Discovery Fund III (E0623I)
DQ India: Inflexor Ventures closes second fund at over ₹600 crore
YourStory: Inflexor Ventures closes second fund at over ₹600 Cr (Jul 2021)
Inc42: Inflexor Ventures marks first close of Opportunities Fund at ₹280 Cr (Nov 2024)
DealStreetAsia: Inflexor hits first close of Opportunities Fund, raises 80% of target
YourStory: The key signals Inflexor looks for in deep-tech startups (Mar 2026)
Inflexor Ventures: About us and team
Inflexor Ventures: Portfolio
Newskart: Inflexor Ventures Fund III gets ₹400 crore first close
Indian Startup Times: Inflexor announces first close of ₹1,250 crore Fund III
Entrackr: A91 Partners closes US$665m Fund III
The Week (PTI): Tech startups raise US$10.5bn in 2025, says Tracxn
Entrackr: 18 startup IPOs in 2025
Inc42: Physis Capital closes maiden fund at ₹400 Cr
Inflexor Ventures: Home
AIIB: Venture Capital Investment Program for Green and Technology-Enabled Infrastructure
| DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|