NIIF Infrastructure Fund II: ₹19,000 Cr (~US$2bn) First Close
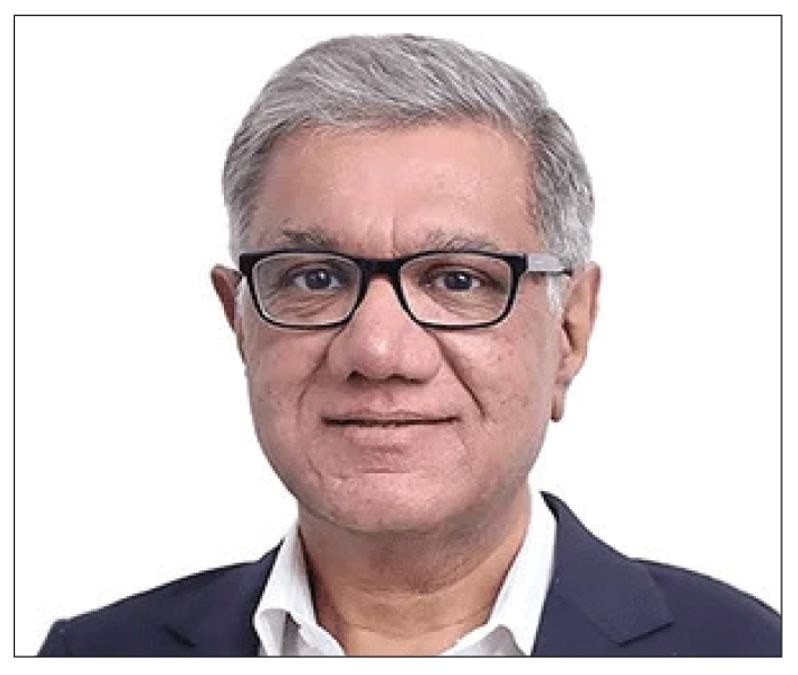
Sanjiv Aggarwal, Managing Director and CEO, NIIF Limited · Image: Indian Infrastructure
Independent report content
| FUND | NIIF Infrastructure Fund II · successor to the ₹16,000 Cr (~US$2.34bn) NIIF Master Fund |
|---|---|
| SIZE | First close ₹19,000 Cr (~US$2bn) on 31 Aug 2026 · Target ₹30,000 Cr (~US$3.2bn) · Expected co-investment ₹9,000 Cr (~US$950m) |
| STRATEGY | Control and platform investing · Core: energy, transport, digital · Emerging: urban infrastructure, electric mobility |
| MANAGER | National Investment and Infrastructure Fund Ltd (NIIF) · Government of India holds 49% · US$7bn+ across four strategies |
| TRACK RECORD | Master Fund: 5 closes (2017–2020), ~9 platforms · Platform-wide exits and announced sales of US$1.9bn+ · Ayana, IntelliSmart, Athaang roads, Aseem, Manipal, Ather |
| LPS | Government of India · ADIA (subsidiary) · AustralianSuper · CPP Investments · Ontario Teachers' · Temasek · ICICI Bank · HDFC Bank · Axis Bank · Kotak Life · HDFC Life |
| COMPARED WITH | NIIF Master Fund (Fund I) · NIIF Private Markets Fund II · NIIF India-Japan Fund · Q3 2026 India fundraising market |
| THE ACCESS PROBLEM Fund II is an institutional vehicle. Its first close came from the Government of India, sovereign wealth funds, pension funds, banks and insurers. No retail, HNI or family-office route has been announced. Indian individuals reach the same assets indirectly: through listed companies that NIIF built or exited (such as Ather Energy), listed infrastructure InvITs, or the private funds that NIIF's own fund-of-funds programme backs. |
|---|
Executive decision summary
| THE BOTTOM LINE | NIIF Infrastructure Fund II was the biggest single fund close in India in Q3 2026. Its first close of ₹19,000 crore is already larger than the whole of its ₹16,000 crore predecessor. The reason is simple. Fund I has started returning cash. Ayana Renewable was sold at a ₹19,500 crore enterprise value, road assets were sold in four months, and IntelliSmart is being sold to Adani Energy Solutions at a ₹3,050 crore equity value. Every global investor named in Fund II was also an investor in Fund I. The catch for most Indian investors is access: this is a sovereign-anchored, institution-only fund. |
|---|---|
| WHICH INVESTOR | Allocate to Fund II IF you are an institution (pension fund, insurer, bank, sovereign or large corporate treasury) that wants core Indian infrastructure equity with a government anchor and a manager that has already returned cash. Use the indirect routes instead IF you are an HNI, family office or NRI: listed infrastructure InvITs, NIIF-built companies after listing, or the mid-market private equity funds that NIIF's Private Markets Fund anchors. |
| COMFORT FIT | NIIF Infrastructure Fund II = Indian Railways' Vande Bharat. State-anchored, built for national infrastructure, now running on a proven route with private-sector engineering. NIIF Master Fund (Fund I) = Rajdhani Express. The original flagship. It proved the route, delivered the passengers and is now unloading at the station (exits). NIIF Private Markets Fund II = a metro network. It does not run the trains itself but funds the operators (other PE funds) across the city. NIIF India-Japan Fund = the Mumbai–Ahmedabad bullet train. A bilateral India–Japan project with a narrow, electric-mobility focus. |
| THE RUPEIA NUMBER | Of the 11 non-government institutions named as Master Fund investors, 9 are named again in Fund II: ADIA, AustralianSuper, CPP Investments, Ontario Teachers', Temasek, ICICI Bank, Axis Bank, the HDFC group and Kotak's life insurer. A re-up rate of about 82% among named LPs is the clearest vote of confidence a sovereign-backed manager can get. These are institutions with their own India infrastructure teams. They saw Fund I's exits from the inside and came back for more. |
1 FUND SNAPSHOT: FUND II VS THE NIIF PLATFORM
NIIF runs four strategies: Infrastructure, Private Markets, Growth Equity and Climate Investments. To judge Fund II, compare it first with its own predecessor and its sister funds. Together they are the closest thing India has to a sovereign infrastructure investor.
| Dimension | Infrastructure Fund II | Master Fund (Fund I) | Private Markets Fund II | India-Japan Fund |
|---|---|---|---|---|
| Size | ₹19,000 Cr first close; ₹30,000 Cr target | ₹16,000 Cr (~US$2.34bn) final close | US$750m first close; aiming above US$1bn | ~US$600m |
| Key dates | First close 31 Aug 2026 | First close Oct 2017; final close Dec 2020 | First close Mar 2026 | Launched Apr 2023 |
| What it does | Control and platform equity in core infrastructure | Built platforms in ports, renewables, roads, smart meters, airports, data centres | Fund of funds: anchors India PE and VC managers | Climate and e-mobility equity |
| Anchor | Government of India | Government of India | Government of India | Government of India and JBIC |
| Global LPs | ADIA (sub.), AustralianSuper, CPP, OTPP, Temasek | ADIA, AustralianSuper, CPP, OTPP, Temasek, PSP, DFC | — | JBIC |
| Indian LPs | ICICI Bank, HDFC Bank, Axis Bank, Kotak Life, HDFC Life | HDFC group, ICICI Bank, Kotak Mahindra Life, Axis Bank | — | — |
| Co-investment | ~₹9,000 Cr expected | Rights to ~US$3bn alongside the fund | — | — |
| Exits to date | None (new fund) | Ayana, Athaang roads (select), IntelliSmart (agreed) | Predecessor PMF fully committed | Ather stake retained |
| RUPEIA READ Fund II's first close equals 1.19 times Fund I's entire corpus. Counting expected co-investment, NIIF already controls about ₹28,000 crore of fresh infrastructure equity. If Fund II reaches target and the co-invest ratio holds, that rises to about ₹44,000 crore. |
|---|
2 HOW NIIF WAS BUILT: 2015–2026 TIMELINE
| Date | Milestone |
|---|---|
| Feb 2015 | Union Budget 2015-16 announces the National Investment and Infrastructure Fund |
| Oct 2016 | Sujoy Bose appointed first CEO |
| Oct 2017 | Master Fund first close; ADIA becomes the first global backer |
| Feb 2018 | Ports and logistics joint venture with DP World (Hindustan Infralog) |
| Apr 2018 | Green Growth Equity Fund set up with the UK's FCDO, India's first decarbonisation fund |
| Oct 2018 | Master Fund invests in Ayana Renewable Power; Temasek commits |
| May 2019 | NIIF acquires IDFC Infrastructure Finance (renamed NIIF IFL) and incorporates Aseem Infrastructure Finance |
| Dec 2019 | Master Fund reaches its US$2.1bn target at the fourth close; smart-meter platform (IntelliSmart) set up with EESL |
| Mar 2020 | Master Fund creates roads company Athaang Infrastructure |
| Aug 2020 | First road assets: Devanahalli and Dichpally tollways |
| Nov 2020 | Government commits ₹6,000 Cr to NIIF IFL and Aseem |
| Dec 2020 | Master Fund final close at US$2.34bn, above target; PSP Investments and DFC join |
| Feb–Mar 2021 | Strategic Opportunities Fund invests in Manipal Hospitals; SOF first close |
| May 2022 | SOF leads Ather Energy's Series E; Master Fund invests in Hindustan Ports with DP World |
| Jun–Jul 2022 | Navayuga Quazigund Expressway and Jammu–Udhampur Highway acquired |
| Nov–Dec 2022 | GMR airports partnership (incl. Goa's Manohar International Airport); Digital Edge data-centre partnership |
| Jan 2023 | Master Fund wins NHAI's TOT-9 road bundle |
| Mar–Apr 2023 | SOF exits Manipal Hospitals to Temasek; India-Japan Fund launched (~US$600m) |
| May 2023 | Sujoy Bose demits office; Rajiv Dhar interim CEO |
| Feb 2024 | Sanjiv Aggarwal (ex-Actis) takes over as MD & CEO; Master Fund invests US$200m in iBUS |
| Feb–Mar 2025 | Ayana sale to ONGC NTPC Green signed (Feb) and completed (Mar) |
| Jun 2025 | Exit from select Athaang road assets, completed in four months |
| Feb 2026 | SOF completes phased exit from Ather Energy |
| Mar 2026 | Private Markets Fund II first close at US$750m; AnantGrid transmission platform's pre-bid partnership with Bajel Projects |
| Jun 2026 | Agreement to sell IntelliSmart to Adani Energy Solutions; Cabinet approves additional ₹30,000 Cr for NIIF |
| Jul 2026 | Agreement to sell stake in Aseem Infrastructure Finance to a TPG-led consortium |
| 31 Aug 2026 | Infrastructure Fund II first close at ₹19,000 Cr |
| 7 Sep 2026 | Gauravjit Singh appointed Managing Partner, Global Head of Capital Formation |
The timeline shows a deliberate sequence. Between 2017 and 2020, NIIF raised money and bought or built platforms. Between 2021 and 2023 it diversified into private equity, fund-of-funds and climate. From 2025 it has been selling. Fund II is being raised at the moment the first cycle turned into cash.
3 GP QUALITY & TEAM ANALYSIS
Ownership: who owns the manager
NIIF Ltd, the investment manager, is 49% owned by the Government of India. The rest is held by institutional investors. Several Master Fund LPs also became shareholders of the manager; DFC and PSP Investments joined as shareholders at the 2020 final close. This structure is unusual. NIIF's biggest LPs are also part-owners of the GP, which aligns them with the platform's long-term success rather than any single fund's fees.
Leadership
| Person | Role | Background and tenure (published) |
|---|---|---|
| Sanjiv Aggarwal | Managing Director & CEO | Joined Feb 2024 from Actis, the emerging-markets infrastructure and energy investor, where the appointee became a partner in 2010 |
| Vinod Giri | Managing Partner, Infrastructure | Led the Master Fund; spokesman for the Ayana exit and the Fund II close |
| Padmanabh Sinha | Private equity (Strategic Opportunities Fund) | NIIF's spokesman on the Manipal Hospitals exit |
| Gauravjit Singh | Managing Partner, Global Head of Capital Formation | Appointed 7 Sep 2026, a week after Fund II's first close |
| Sujoy Bose | First MD & CEO (Oct 2016 – May 2023) | Built the Master Fund, SOF and Private Markets franchises |
| Rajiv Dhar | Interim MD & CEO (May 2023 – Feb 2024) | Bridged the leadership transition |
Team stability and attribution
NIIF had a leadership change in 2023. Its founding CEO left after nearly seven years, followed by nine months with an interim chief. Attribution therefore needs a careful look. The Master Fund's platforms were built under Sujoy Bose; its exits were executed under Sanjiv Aggarwal. The infrastructure team's continuity is the stronger signal. Vinod Giri spoke for the Master Fund on the 2025 Ayana exit and for Infrastructure Fund II at its 2026 close. The person who led Fund I's platform-building is now leading Fund II.
| RUPEIA READ The 2023 transition did not interrupt delivery. Four of the platform's biggest exits (Ayana, Athaang roads, IntelliSmart and Aseem) were all signed after Aggarwal arrived. The Actis background is specifically in building and selling emerging-market infrastructure and energy platforms. That matches NIIF's second cycle. Appointing a dedicated capital-formation head a week after first close shows the remaining ₹11,000 crore is being treated as a priority. |
|---|
| RUPEIA SCORE: GP QUALITY 9/10 Deep, institutional team with continuity at the infrastructure-fund level and a CEO whose background fits the exit phase. The point withheld reflects the 2023 leadership gap, now closed. |
|---|
4 MASTER FUND TRACK RECORD: THE PLATFORMS
The Master Fund raised money in five closes between October 2017 and December 2020. It ended at US$2.34 billion (₹16,000 crore) against a US$2.1 billion target. International investors also received rights to co-invest about US$3 billion alongside the fund. NIIF says the fund invested in renewables, transmission, distribution, battery storage, roads, ports and logistics, airports, data centres and smart metering.
| Platform | Sector | Entry | What NIIF built | Status (Nov 2026) |
|---|---|---|---|---|
| Hindustan Infralog / Hindustan Ports (with DP World) | Ports and logistics | Feb 2018; broadened May 2022 | Number two player by volume market share; presence in 7 states | Held |
| Ayana Renewable Power (with BII, Eversource) | Renewable energy | Oct 2018 (NIIF 51%) | 4.1 GW operational and under construction | Exited Mar 2025 |
| IntelliSmart Infrastructure (with EESL) | Smart metering | Dec 2019 | 22m+ smart meters across 5 states; among India's top 3 | Sale to Adani Energy Solutions agreed Jun 2026 |
| Athaang Infrastructure | Roads | Mar 2020; assets from Aug 2020 | 1,000+ lane-km; ~150,000 passenger car units a day; Devanahalli, Dichpally, Navayuga Quazigund, Jammu–Udhampur, NHAI TOT-9 | Select assets exited Jun 2025 |
| GMR airports partnership | Airports | Nov 2022; ₹675 Cr in Visakhapatnam Aug 2023 | Two airport investments: Goa (Manohar International) and Bhogapuram (Andhra Pradesh, greenfield) | Held |
| Digital Edge (with AGP) | Data centres | Dec 2022 | 350 MW AI-ready hyperscale campus in Navi Mumbai; ~18 MW operational | Held |
| iBUS | Digital infrastructure | Feb 2024, US$200m | Digital infrastructure solutions across 21 states and 5 UTs (platform-wide figure) | Held |
| AnantGrid | Power transmission | 2026 | Wholly owned transmission platform; pre-bid partnership with Bajel Projects | Held; ninth infrastructure investment |
| RUPEIA CALCULATION About nine platforms on a ₹16,000 crore corpus works out to roughly ₹1,800 crore of equity per platform, before co-investment. At ₹30,000 crore, Fund II has room for 15–16 platforms of the same size, or fewer, larger ones. NIIF's pattern is to start with a partner or a seed asset, buy assets around it, and sell the scaled platform. Fund II's sector list suggests the next platforms will be in transmission, data centres, urban infrastructure and electric mobility. |
|---|
5 PLATFORMS STILL HELD: FUND I'S REMAINING VALUE
Several large Fund I platforms have not yet been sold. Their eventual exits will decide Fund I's final multiple. Until then, they are the operating record Fund II is sold on.
Hindustan Infralog and Hindustan Ports (with DP World)
Formed in February 2018 as a joint venture between DP World and NIIF's Master Fund, with plans to invest up to US$3 billion in Indian ports, logistics and related sectors. Its first deal was 90% of Continental Warehousing Corporation in 2018, a Mumbai-based logistics company with over 660,000 TEU of capacity in its network. In 2019 it bought 76% of KRIBHCO Infrastructure through Continental Warehousing. KRIBHCO Infrastructure runs inland container depots and private freight terminals at Pali (Haryana), Modinagar (Uttar Pradesh) and Hazira (Gujarat), plus container train operations. In 2022 the partnership extended into Hindustan Ports. NIIF describes the platform as India's number two ports and logistics player by volume market share, present in seven states.
GMR airports
In November 2022 the Master Fund partnered with GMR Airports on three airport projects, including GMR Goa International Airport, which runs Manohar International Airport. In 2023 NIIF agreed to invest up to ₹675 crore (about US$80 million) in GMR Visakhapatnam International Airport, the company building the greenfield Bhogapuram International Airport in Andhra Pradesh. Its first phase is designed for about 6 million passengers a year, rising to 40 million at full build-out.
Digital Edge data centres
NIIF, Digital Edge and AGP formed a pan-India data-centre platform in late 2022 and early 2023. Its anchor project is a 350 MW AI-ready hyperscale campus in Navi Mumbai, which NIIF describes as India's largest hyperscale facility under construction. The first phase has begun operations, with about 18 MW live as of NIIF's September 2026 update.
iBUS Network
In April 2024 the Master Fund invested about US$200 million for a majority stake in iBUS. iBUS builds and runs neutral-host cellular and Wi-Fi networks inside large buildings: IT parks, airports and hospitals. The capital funds organic growth and acquisitions.
AnantGrid
A wholly owned power-transmission platform, and the Master Fund's fourth energy investment. In March 2026 it entered a pre-bid partnership with Bajel Projects, a transmission EPC company, to bid for transmission projects.
| RUPEIA READ The held portfolio is weighted towards the assets with the longest growth runway: data centres (18 of 350 MW built), a greenfield airport, ports and logistics, and transmission. These are not stranded assets. They are the parts of Fund I still being built. Their exits are likely to come late in Fund I's life, which is one reason NIIF can show both realised exits and unrealised growth at the same time. |
|---|
6 EXIT DEEP DIVE: SIX TRANSACTIONS THAT BUILT THE CASE
Fund II's pitch rests on cash returned. NIIF reported in June 2026 that it had returned close to ₹12,000 crore to investors. By September 2026, CEO Sanjiv Aggarwal put completed exits and announced sales at over US$1.9 billion in distributions and expected realisations across roads, renewables and EV manufacturing.
1. Ayana Renewable Power: the flagship exit
In February 2025, NIIF, British International Investment and Eversource Capital agreed to sell 100% of Ayana to ONGC NTPC Green Private Limited, a 50:50 joint venture of ONGC Green and NTPC Green Energy. The enterprise value was ₹19,500 crore (US$2.3 billion). Ayana had 4.1 GW of operational and under-construction capacity, contracted with highly rated offtakers. It was the joint venture's first acquisition since its formation in November 2024. The deal closed in March 2025. BII said the shareholders had mobilised "well over US$1bn" for Ayana over eight years.
2. Athaang roads: speed of execution
NIIF exited select road assets held under Athaang Infrastructure in June 2025, completing the transaction in four months. Athaang had been assembled from 2020 through acquisitions of operating toll roads and the NHAI TOT-9 bundle.
3. IntelliSmart: smart metering to Adani Energy Solutions
In June 2026, NIIF signed a definitive agreement to sell IntelliSmart Infrastructure to Adani Energy Solutions at an equity value of ₹3,050 crore (US$320 million). IntelliSmart was set up in December 2019 with Energy Efficiency Services Ltd (EESL). It grew into one of India's top three smart-metering players, with over 22 million smart meters across five states.
4. Aseem Infrastructure Finance: to a TPG-led consortium
In July 2026, NIIF agreed to sell its stake in Aseem Infrastructure Finance, the infrastructure-debt NBFC it set up in 2019, to TPG, with GIC and ICICI Bank as co-investors. The Government of India and SMBC of Japan remain minority shareholders. Rupeia covers this deal in Report 27.
5. Manipal Hospitals: the top Indian PE exit of 2023
NIIF's Strategic Opportunities Fund invested about ₹2,100 crore for roughly 8% of Manipal Hospitals in 2021. In 2023, it exited fully as part of Temasek's purchase of a controlling stake. NIIF describes it as the top private equity exit in India in 2023.
6. Ather Energy: NIIF's first listed exit
The SOF led Ather Energy's US$128 million Series E in 2022 alongside Hero MotoCorp. It invested ₹374.5 crore. NIIF then exited in phases, through Ather's 2025 IPO and later block trades. It sold a 2.28% stake for about ₹541 crore in November 2025 and the remaining 1.92% for ₹520.7 crore at ₹710 a share in February 2026. Entrackr put total proceeds at ₹1,167.5 crore, about 3.1x in three years. Ather became the first listed company across NIIF platforms. NIIF stays invested through its India-Japan Fund.
| Exit | Fund | Year | Buyer type | Published value |
|---|---|---|---|---|
| Ayana Renewable | Master Fund | 2025 | State-owned strategic (ONGC–NTPC JV) | EV ₹19,500 Cr |
| Athaang (select roads) | Master Fund | 2025 | Not named | Part of US$1.9bn+ |
| IntelliSmart | Master Fund | 2026 (agreed) | Listed private strategic (Adani Energy Solutions) | Equity value ₹3,050 Cr |
| Aseem Infrastructure Finance | Growth Equity platform | 2026 (agreed) | Global PE consortium (TPG, GIC, ICICI Bank) | Not published |
| Manipal Hospitals | Strategic Opportunities Fund | 2023 | Sovereign investor (Temasek) | Invested ~₹2,100 Cr |
| Ather Energy | Strategic Opportunities Fund | 2025–26 | Public market (IPO and block trades) | ₹1,167.5 Cr from ₹374.5 Cr (~3.1x) |
| RUPEIA DPI VERDICT High confidence. The exits are named, priced and closed or contracted, and they are spread across four buyer types: a state-owned strategic, a listed private strategic, a global PE consortium and the public market. That diversity is the best evidence that NIIF can exit in different market conditions. Against the Master Fund's ₹16,000 crore, the ~₹12,000 crore returned by June 2026 is about 0.75x of corpus in cash. That is before the IntelliSmart and Aseem proceeds are received and with large platforms (ports, airports, data centres) still held. The ₹12,000 crore is a platform-wide figure, and Rupeia does not attribute it to the Master Fund alone. |
|---|
7 VALUATION MARKERS: WHAT BUYERS PAID FOR NIIF'S PLATFORMS
NIIF's exits give the market a rare set of published prices for Indian infrastructure platforms. Rupeia converts them into the unit measures investors use to compare deals.
| Asset | Published price | Unit measure | Rupeia calculation |
|---|---|---|---|
| Ayana Renewable Power | Enterprise value ₹19,500 Cr | 4.1 GW operational and under construction | ~₹4.8 Cr of EV per MW |
| IntelliSmart Infrastructure | Equity value ₹3,050 Cr | 22m+ smart meters (contracted, 5 states); 5m+ operational (NIIF) | ~₹1,400 of equity value per contracted meter; ~₹6,100 per operational meter |
| Ather Energy (SOF) | ₹1,167.5 Cr proceeds on ₹374.5 Cr invested | Held ~3.5 years (May 2022 to Nov 2025–Feb 2026) | ~3.1x money multiple; roughly 35–40% a year |
| GMR Visakhapatnam (Bhogapuram) | Up to ₹675 Cr (~US$80m) invested | Phase I ~6m passengers a year; ultimate 40m | Entry price, not an exit |
| RUPEIA READ These markers matter beyond NIIF. The Ayana price of about ₹4.8 crore of enterprise value per MW, including capacity under construction, is now a public benchmark for any Indian renewables platform sale. The IntelliSmart price sets a reference for India's smart-metering roll-out, which is moving from state contracts to private platforms. For Fund II's LPs, the markers show that Fund I sold at prices strategic buyers were willing to pay for scale. That is the exit premium the platform model is designed to capture. |
|---|
8 THE REST OF THE NIIF PLATFORM
Private Markets Fund: the fund of funds
NIIF's Private Markets Fund anchors other Indian fund managers. Its first fund had fully committed its capital by January 2024. Private Markets Fund II reached a US$750 million first close in March 2026, and NIIF aims to scale it above US$1 billion. Published commitments from the first fund include:
| Fund backed | Strategy | Year |
|---|---|---|
| Green Growth Equity Fund (with UK FCDO; managed by Eversource Capital) | Climate / decarbonisation | 2018 |
| HDFC Capital Affordable Real Estate Fund 2 | Affordable housing | 2018 |
| Multiples PE Fund III | Mid-market private equity | 2019 |
| Somerset Indus Healthcare India Fund II | Healthcare | 2020 |
| Arpwood Partners Fund I | Mid-market buyout | 2021 |
| YourNest Innovative Products VC Fund III | Deep-tech venture capital | 2021–22 |
| Lighthouse India Fund IV (₹400 Cr anchor) | Mid-market consumer PE | 2023 |
| Amicus Capital Partners India Fund II (₹207 Cr) | Mid-market PE | 2024 |
Strategic Opportunities Fund
Fundraising for the SOF began at the Master Fund's final close in December 2020 with a US$2.1 billion target. Its first close followed in March 2021. It backs market leaders in sectors short of capital. Its two published exits, Manipal and Ather, are its proof points.
India-Japan Fund (Climate Investments)
Launched in April 2023 at about US$600 million, with the Government of India and Japan Bank for International Cooperation (JBIC) as anchors. Its investments are Mahindra Last Mile Mobility (₹400 crore, its first), Ather Energy, and Eka Mobility (₹500 crore, about US$57 million, e-buses). Across NIIF platforms, more than 300,000 EVs are on the road in 15+ states.
Growth Equity: infrastructure debt
NIIF acquired IDFC Infrastructure Finance in 2019, renamed it NIIF IFL, and set up Aseem Infrastructure Finance. In November 2020 the government committed ₹6,000 crore to these two lenders. NIIF says more than half the loan book, across 250+ projects, is green project finance.
Advisory mandates
NIIF also advises the government on the ₹1 lakh crore Research, Development and Innovation Fund housed in the Anusandhan National Research Foundation. It also advises on a proposed ₹25,000 crore Maritime Development Fund, of which ₹20,000 crore would be an investment fund with 49% government and 51% private or institutional money. NIIF has signed MoUs with the Government of Bihar and Indian Oil Corporation, and is a signatory to the UN-supported Principles for Responsible Investment.
9 STRATEGY TRUTH VS PORTFOLIO REALITY
| Promise | What actually happened | Verdict |
|---|---|---|
| Master Fund (2020): "primarily transportation and energy" | Ports, roads, airports (transport); renewables, smart meters, transmission (energy); then data centres and digital infrastructure | Delivered, then broadened into digital |
| Platform model: build scale, then sell | Ayana grew to 4.1 GW and sold at ₹19,500 Cr EV; IntelliSmart reached 22m+ meters and was sold; Athaang assembled from 5+ road assets | Delivered |
| Crowd in global capital | ADIA, AustralianSuper, CPP, OTPP, Temasek, PSP, DFC in Fund I; US$3bn co-invest rights | Delivered |
| Fund II: energy, transport, digital core | First Fund II-era platform (AnantGrid, transmission) fits the core | On track |
| Fund II: urban infrastructure and e-mobility | E-mobility experience exists in the India-Japan Fund (Ather, Mahindra LMM, Eka); urban infrastructure is new | New ground |
| RUPEIA SCORE: STRATEGY 8.5/10 No drift: Fund I did what it promised and sold what it built. The 1.5 points withheld reflect Fund II's move into urban infrastructure and e-mobility. These are newer areas for the infrastructure team, with less predictable cash flows than toll roads or contracted renewables. |
|---|
10 FUND II: WHAT IS NEW
Size: ₹19,000 crore first close, more than 60% of the ₹30,000 crore target. Press reports on the close said NIIF plans to raise the remaining ~US$1.2 billion within 18 months.
Where the rest comes from: Bloomberg reported that NIIF is targeting Japanese and European capital for the remainder. JBIC is already a partner through the India-Japan Fund.
Sector split: core sectors are energy, transport and digital infrastructure. Emerging themes are urban infrastructure and electric mobility.
Co-investment: about ₹9,000 crore expected, roughly 47% of the first-close corpus. Large LPs can put extra money into individual platforms without paying fund-level fees on it.
Anchor: the Government of India again, backed by the June 2026 Cabinet decision to commit a further ₹30,000 crore to NIIF's funds.
Vinod Giri said Fund II builds on the strong performance and operating capabilities of the first fund. CEO Sanjiv Aggarwal described NIIF as entering its next phase of growth. That phase includes successor funds, new areas such as credit, and scaling existing platforms.
11 WHERE FUND II WILL INVEST: THE SECTOR PIPELINE
Fund II will deploy over roughly 2026–2031. In each of its target sectors, a published government programme sets the demand for that period. NIIF already has a platform or portfolio company in each one.
| Sector | Published national pipeline | NIIF's existing position |
|---|---|---|
| Power transmission | National Electricity Plan (Transmission), launched 14 Oct 2024: over ₹9.15 lakh crore of investment by 2032; 1.91 lakh circuit-km of lines and 1,270 GVA of transformation capacity, to integrate 600 GW+ of non-fossil capacity | AnantGrid (wholly owned), with a Bajel Projects pre-bid partnership |
| Smart metering | RDSS: 20.33 crore smart meters sanctioned (19.79 crore consumer meters); 7.24 crore installed nationwide as of 30 Jun 2026; scheme runs to Mar 2028 | IntelliSmart (22m+ meters), now being sold to Adani Energy Solutions |
| Electric buses | PM-eBus Sewa: 10,000 AC e-buses in 116 cities across 26 states and UTs by end-2027; 23,800 scheme buses across PM-eBus Sewa and PM E-DRIVE; payment-security mechanism for 38,000+ e-buses by 2029 | Eka Mobility (India-Japan Fund), which with Chartered Speed is deploying 1,750 e-buses in Bengaluru |
| Data centres | AI-driven hyperscale demand | Digital Edge 350 MW Navi Mumbai campus (~18 MW live) |
| Renewables | Transmission plan built around 600 GW+ non-fossil capacity by 2032 | Ayana built and exited; 5+ GW renewables experience across 5 states |
| RUPEIA READ Smart metering shows NIIF's timing. IntelliSmart is being sold when about 7 crore of the 20 crore sanctioned meters are installed, with most of the roll-out still ahead. The buyer is paying for the remaining growth. Fund II's sectors are at the same early point: transmission's ₹9.15 lakh crore build-out runs to 2032, and e-bus tenders are still converting into awards (6,228 tendered and 4,720 letters of award as of February 2026). Fund II is entering each theme before the peak of its national roll-out, the same position Fund I held in smart meters in 2019. |
|---|
12 FUND MATHS: SIZE, CO-INVESTMENT AND FIREPOWER
| Scenario | Fund II corpus | Co-investment (at ~47%) | Total equity firepower | Platforms at ~₹1,800 Cr each |
|---|---|---|---|---|
| First close | ₹19,000 Cr | ₹9,000 Cr | ₹28,000 Cr | ~10 |
| Target (if the ratio holds) | ₹30,000 Cr | ~₹14,200 Cr | ~₹44,200 Cr | ~16 |
| Fund I for comparison | ₹16,000 Cr | Rights to ~US$3bn | Fund plus co-invest rights | ~9 actual |
| RUPEIA CALCULATION The co-investment ratio is what makes NIIF different from a normal fund. In Fund I, global LPs held co-invest rights worth more than the fund itself. That let NIIF buy large assets without concentrating the fund. Ayana (₹19,500 crore EV) and the GMR airports are examples. Fund II starts with a lower stated co-invest ratio (~47%) but a larger base. Expect bigger single platforms, especially in transmission and data centres, where projects run to thousands of crores. |
|---|
13 VALUE CREATION BRIDGE: WHAT DRIVES NIIF'S RETURNS
| Value driver | Published evidence | Rupeia assessment |
|---|---|---|
| Platform scaling (build, then sell) | Ayana: launched 2018, sold at 4.1 GW; IntelliSmart: set up 2019, sold with 22m+ meters | The main engine. Returns come from turning a seed asset into a sellable platform. |
| Acquisition and aggregation | Athaang: five-plus road assets bought from 2020 and sold in parts from 2025 | Repeatable in roads and transmission. |
| Partnering with operators | DP World (ports), EESL (meters), GMR (airports), Digital Edge (data centres), BII and Eversource (renewables) | Reduces execution risk; NIIF supplies capital and governance. |
| Strategic exit premium | State-owned and private strategics paid for scale (ONGC–NTPC, Adani) | Strategics pay for platforms they cannot quickly build themselves. |
| Public-market re-rating | Ather: 3.1x via IPO and block trades | Supplementary; mainly in SOF, not the infrastructure fund. |
| Leverage | Infrastructure platforms use project debt; NIIF IFL and Aseem are in-house lenders | Supports equity returns; adds refinancing risk. |
14 HOW INFRASTRUCTURE EQUITY RETURNS ARRIVE: FUND I'S CLOCK
Infrastructure equity funds return money in two ways: yield (dividends and interest from operating assets) and exits (selling platforms). NIIF's model leans heavily on exits. It builds platforms to a size a strategic buyer will pay for, then sells them. That shapes when an LP gets cash back.
| Milestone | Date | Years from Master Fund first close (Oct 2017) |
|---|---|---|
| First platform (DP World ports JV) | Feb 2018 | 0.3 |
| Final close | Dec 2020 | 3.2 |
| First NIIF-platform exit (Manipal, SOF) | Mar–Apr 2023 | 5.5 |
| First large Master Fund exit (Ayana, completed) | Mar 2025 | 7.4 |
| Road assets exit | Jun 2025 | 7.7 |
| IntelliSmart sale agreed | Jun 2026 | 8.7 |
| Platform-wide exits and announced sales pass US$1.9bn | Sep 2026 | 8.9 |
| RUPEIA CALCULATION The Master Fund took about 7.4 years from first close to its first large completed exit, and about 9 years to pass US$1.9 billion in realisations across the platform. A Fund II LP committing in 2026 should therefore expect the bulk of distributions from about 2032–2035. Co-investment changes the maths for large LPs. Co-invest capital usually carries lower fees than the main fund, so LPs who take co-invest alongside their commitment lower their blended cost and raise their net return. |
|---|
Fund II has one structural advantage over Fund I. It starts with an operating team, a pipeline of platform ideas (transmission, data centres, e-mobility) and buyer relationships already in place. Fund I needed three years and five closes to finish raising before it could deploy at full pace. Fund II began investing-ready, with ₹19,000 crore at first close.
15 LP SIGNAL & RE-UP ANALYSIS
Infrastructure Investor's headline on the close was that strong re-ups drove the US$2bn first close. The named investor lists show it directly.
| Investor | Master Fund (Fund I) | Infrastructure Fund II | Signal |
|---|---|---|---|
| Government of India | Anchor | Anchor | Re-up |
| Abu Dhabi Investment Authority | Yes (first global backer, 2017) | Yes (wholly owned subsidiary) | Re-up |
| AustralianSuper | Yes | Yes | Re-up |
| CPP Investments | Yes | Yes | Re-up |
| Ontario Teachers' Pension Plan | Yes | Yes | Re-up |
| Temasek | Yes (2018) | Yes | Re-up |
| ICICI Bank | Yes | Yes | Re-up |
| Axis Bank | Yes | Yes | Re-up |
| HDFC group | Yes | HDFC Bank and HDFC Life | Re-up |
| Kotak Mahindra Life Insurance | Yes | Kotak Life Insurance | Re-up |
| PSP Investments | Yes (2020) | Not named | — |
| DFC (US) | Yes (2020) | Not named | — |
| RUPEIA LP VERDICT Strongest possible. Nine of the eleven named non-government Fund I LPs are named again. They include three of the world's largest pension systems (Canada's CPP and OTPP, Australia's AustralianSuper) and two of Asia's largest sovereign investors (ADIA, Temasek). These institutions saw Ayana, IntelliSmart and the roads exits before they committed. The two not yet named, PSP and DFC, are the natural candidates for the remaining ₹11,000 crore, along with the Japanese and European money NIIF is targeting. |
|---|
16 MARKET & POLICY CONTEXT
Biggest fund of the quarter: India-focused funds raised US$6.4 billion across 32 funds in Q3 2026. NIIF Infrastructure Fund II, at about US$2 billion, was the largest single close.
PE and VC activity: PE and VC investment in India reached US$17.1 billion in Q3 2026, up 46%.
Government backing: after the Budget 2015 announcement and the ₹6,000 crore committed to NIIF's lenders in 2020, the Cabinet approved a further ₹30,000 crore for NIIF in June 2026. That takes the government's total commitment to ₹60,000 crore.
Strategic buyers are active: the ONGC–NTPC joint venture, Adani Energy Solutions and TPG all bought NIIF assets in 2025–26. Fund II's eventual exits depend on that buyer universe staying active.
17 CAPABILITY MATRIX: YES / NO / PARTIAL
| Capability | Infra Fund II | Master Fund | PMF II | India-Japan Fund |
|---|---|---|---|---|
| Government of India anchor | YES | YES | YES | YES |
| Sovereign and pension LPs | YES | YES | ? | PARTIAL |
| Control / platform-building strategy | YES | YES | NO | PARTIAL |
| Named exits with published values | NO (new) | YES | NO | NO |
| Co-investment for LPs | YES | YES | ? | ? |
| Energy transition exposure | YES | YES | PARTIAL | YES |
| Digital infrastructure / data centres | YES | YES | NO | NO |
| Electric mobility | YES | NO | PARTIAL | YES |
| Open to individual investors | NO | NO | NO | NO |
| Bilateral foreign-government partner | NO | NO | NO | YES |
18 RISK ANALYSIS: RED FLAGS & KILL CONDITIONS
| Red flag | Evidence | Severity | Kill condition | What would resolve it |
|---|---|---|---|---|
| Fundraise tail | ₹11,000 Cr (~US$1.2bn) still to raise within 18 months | MEDIUM | Final close well below ₹30,000 Cr | Japanese and European LPs commit; PSP/DFC re-up |
| Exit-buyer concentration | Largest exits went to state-linked or single large strategics | MEDIUM | Strategic buyers pull back | More exits to global PE, InvITs or IPOs |
| New sectors | Urban infrastructure and e-mobility less proven for the infrastructure team | MEDIUM | Early Fund II deals in new themes underperform | Core-sector deals dominate early deployment |
| Currency | US$-based LPs, rupee assets | LOW-MED | Sharp rupee depreciation erodes US$ returns | Rupee-denominated Indian LPs grow their share |
| Policy and tariff exposure | Toll roads, power and meters run on regulated or government contracts | LOW-MED | Contract or tariff changes | Diversified platforms; contracted revenues |
| Leadership continuity | CEO change in 2023 with 9-month interim | LOW | Senior infrastructure-team departures | Stable team through Fund II deployment |
| Size step-up | Target 1.9x Fund I | LOW-MED | Pressure to deploy into weaker platforms | Co-investment absorbs large deals |
19 INVESTOR CLASS ANALYSIS: WHO CAN USE THIS
For individual investors and HNIs
Fund II is not open to individuals. The practical routes to the same theme are: listed InvITs holding operating roads, transmission lines and renewables; listed companies NIIF backed (Ather Energy is listed); and listed buyers of NIIF assets, such as Adani Energy Solutions (IntelliSmart) and NTPC Green Energy (Ayana, through its joint venture). None of these replicates Fund II's returns. Each gives exposure to the same infrastructure build-out.
For family offices
The most useful thing a family office can take from NIIF is its fund-of-funds manager selection. NIIF's Private Markets Fund has anchored Multiples, Lighthouse, Amicus, Arpwood, Somerset Indus, YourNest and HDFC Capital. A sovereign-backed LP has already run full institutional due diligence on these managers. A family office with ₹10–50 crore to allocate can invest alongside NIIF in these funds' successor vehicles at a fraction of Fund II's ticket size.
For institutions
Fund II is designed for institutions, and the window is open. NIIF has a new capital-formation head and ₹11,000 crore still to raise. The co-investment pool (~₹9,000 crore) is the most attractive feature for a large LP. It offers direct exposure to individual platforms on top of the fund commitment. Indian insurers and banks are already in the first close.
For NRIs
There is no NRI route into Fund II. NRIs can buy listed InvITs and listed NIIF-linked companies through their portfolio investment accounts, subject to FEMA rules.
20 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| Core Indian infrastructure equity with a sovereign anchor | INFRA FUND II | Government anchor; 9 of 11 named Fund I LPs back; proven exits | Institution-only; long hold |
| Exposure to India's best mid-market PE managers | PMF II (or its underlying funds) | NIIF anchors managers after institutional diligence | Fund-of-funds layer adds fees |
| Electric-mobility theme | INDIA-JAPAN FUND | Ather, Mahindra LMM, Eka; JBIC partner | Narrow sector; institution-only |
| Retail access to the same assets | Listed InvITs and listed NIIF-linked companies | Daily liquidity; small tickets | Market volatility; not the same return profile |
| Liquidity within 5 years | Not Fund II | Infrastructure funds run 10+ years | Use listed instruments |
21 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| By early 2028 | Fund II final close (~US$1.2bn more) | Confirms the US$3.2bn target |
| 2026–27 | Completion of the IntelliSmart and Aseem sales | Turns announced sales into cash and lifts the ~₹12,000 Cr returned |
| 2026–27 | First Fund II platform investment | Shows whether Fund II leads with core (energy, transport, digital) or new themes |
| 2026–27 | Japanese or European LP announcement | Broadens the LP base beyond Fund I re-ups |
| Ongoing | Digital Edge Navi Mumbai campus build-out from ~18 MW towards 350 MW | Largest growth asset still held from Fund I |
22 RUPEIA FINAL INDEPENDENT VIEW
NIIF Infrastructure Fund II is among the most institutionally validated private funds raised in India in 2026. Its predecessor did what infrastructure funds promise and rarely deliver on time. It built platforms, scaled them and sold them to a range of buyers, within seven to nine years of first close. The proof is in priced, named transactions: Ayana at ₹19,500 crore EV, IntelliSmart at ₹3,050 crore equity value, roads in four months, Ather at 3.1x. Nine of eleven named Fund I LPs came back.
Its limits are structural. It is closed to individuals, still ₹11,000 crore short of target, and moving into newer themes. Its exit record also leans heavily on strategic buyers, some of them state-linked.
| THE RUPEIA NUMBER 9 of 11. Nine of the eleven non-government institutions named in NIIF's first infrastructure fund are named again in Fund II. In infrastructure fund analysis, that re-up rate, among sovereigns and pension funds that have seen the exits, is the most reliable signal there is. |
|---|
| RUPEIA VERDICT Tier-1 institutional infrastructure fund. For institutions: allocate, and negotiate for co-investment. For HNIs, family offices and NRIs: Fund II is closed to you, but its playbook is not. Follow NIIF's fund-of-funds manager choices and the listed companies on both sides of its exits. |
|---|
Frequently asked questions
What is NIIF Infrastructure Fund II?
The second infrastructure fund of the National Investment and Infrastructure Fund (NIIF), India's government-anchored investment manager. It invests in energy, transport and digital infrastructure, plus urban infrastructure and electric mobility.
How much has NIIF Infrastructure Fund II raised?
A first close of ₹19,000 crore (about US$2 billion) on 31 August 2026, more than 60% of its ₹30,000 crore (about US$3.2 billion) target. NIIF also expects about ₹9,000 crore of co-investment.
Who has invested in NIIF Fund II?
The Government of India (anchor), a subsidiary of ADIA, AustralianSuper, CPP Investments, Ontario Teachers' Pension Plan, Temasek, ICICI Bank, HDFC Bank, Axis Bank, Kotak Life Insurance and HDFC Life.
How big was NIIF's first infrastructure fund?
The NIIF Master Fund closed at US$2.34 billion (₹16,000 crore) in December 2020, above its US$2.1 billion target.
What exits has NIIF made?
Ayana Renewable (to ONGC NTPC Green, ₹19,500 crore EV), select Athaang road assets, IntelliSmart (agreed sale to Adani Energy Solutions, ₹3,050 crore equity value), Aseem Infrastructure Finance (agreed sale to a TPG-led consortium), Manipal Hospitals (to Temasek) and Ather Energy (about 3.1x).
Who runs NIIF?
Sanjiv Aggarwal has been MD & CEO since February 2024. Vinod Giri is Managing Partner, Infrastructure.
Who owns NIIF?
The Government of India owns 49% of NIIF Ltd, the investment manager. Institutional investors own the rest.
Can individuals invest in NIIF?
No. NIIF funds are raised from the government and institutions. Individuals can get related exposure through listed InvITs and listed NIIF-backed or NIIF-linked companies.
Source log
NIIF: Infrastructure Fund II achieves ₹19,000 crore first close (31 Aug 2026)
NIIF: Final close of NIIF Master Fund at US$2.34 billion (21 Dec 2020)
NIIF: Our journey (timeline)
NIIF: Our investments
Indian Infrastructure: Views of Sanjiv Aggarwal, "NIIF is now entering its next phase of growth"
Infrastructure Investor: Strong re-ups drive $2bn first close for NIIF's second infra fund
Bloomberg: India's NIIF eyes Japan, Europe capital for $3.2 billion fund
ANI: NIIF Infrastructure Fund II reaches ₹19,000 crore first close
IPE Real Assets: NIIF, BII and Eversource sell Ayana to ONGC NTPC for $2.3bn
NSE filing: ONGPL share purchase agreement for 100% of Ayana
Entrackr: Ather exit lets NIIF turn ₹375 Cr into ₹1,167 Cr in three years
Inc42: State-backed NIIF exits Ather with ₹521 Cr stake sale
Autocar Pro: NIIFL, Hero MotoCorp key investors in Ather's $128m Series E
Yahoo Finance: Temasek to acquire 41% stake in Manipal Health Enterprises
Business Standard: Sanjiv Aggarwal appointed NIIF CEO and MD
Business Standard: NIIF appoints Rajiv Dhar as interim MD & CEO; Sujoy Bose demits office
pv magazine India: NIIF appoints Actis' Sanjiv Aggarwal as CEO and MD
WebIndia123: Centre doubles commitment to NIIF to ₹60,000 crore
NewsBytes: India PE and VC reach $17.1B in Q3 2026
Wikipedia: National Investment and Infrastructure Fund
Gulf News: DP World JV (Hindustan Infralog) acquires Continental Warehousing
Business Standard: DP World acquires 76% stake in KRIL
YourStory: NIIF picks majority stake in iBUS Network for $200M
NIIF: Digital newsletter, 2nd edition (June 2024)
Asianet Newsable: India PE and VC investments reach $17.1bn in Q3 2026
Business Today: Centre targets ₹9.15 lakh crore investment in transmission by 2032
T&D India: India's smart meter population at 7.24 crore (Parliament)
T&D India: Over 20 crore smart meters okayed under RDSS
Swarajya: PM e-Bus Sewa, 10,000 e-buses for 116 cities by 2027
Ministry of Heavy Industries: Lok Sabha answer on e-bus schemes (Mar 2026)
Autocar Pro: Eka Mobility, Chartered Speed to deploy 1,750 e-buses in Bengaluru
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|