Renfra Energy India: ₹430 crore fresh issue + 47.94 lakh-share OFS
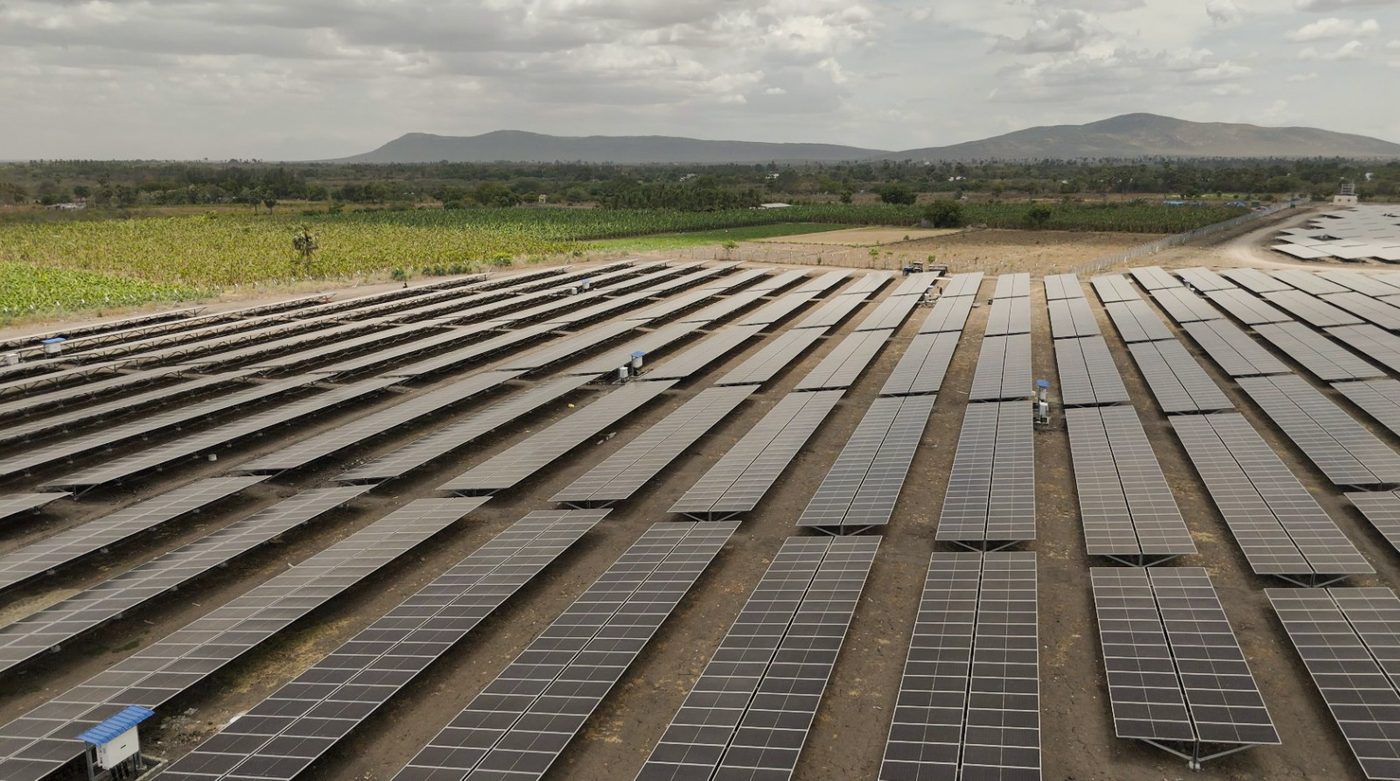
A solar project executed by Renfra Energy, as shown on the company website Source: Renfra Energy website
Independent report content
| OFFER | Book-built: fresh issue ₹430 crore + OFS of 47,94,800 shares by 26 non-promoter holders; optional pre-IPO placement up to ₹50 crore reduces the fresh issue; face value ₹10 |
|---|---|
| STATUS | DRHP filed 30 Jun / 1 Jul 2026; no SEBI observation, price band or dates found (Chittorgarh page updated 27 Oct 2026) |
| LEAD MANAGER | Unistone Capital (sole); registrar Bigshare Services |
| FY26 (RESTATED CONSOLIDATED) | Total income ₹1,018.22 crore (+99.1%) · EBITDA ₹245.94 crore · profit ₹156.82 crore (+65.9%) · net worth ₹466.30 crore · borrowings ₹268.07 crore |
| OBJECTS (₹ CRORE) | Redeem non-convertible debentures 160 · working capital 70 (Mercom says 175) · general corporate purposes (balance) |
| BUILT AND BUILDING | 462.35 MW commissioned (412.85 MW solar + 49.50 MW wind) · 139.10 MW under execution · about 601 MW under O&M · order book about ₹517 crore (May 2026) |
| SCALE | 217 contracts (164 EPC + 53 O&M) with 164 customers · 1,140 people, 683 of them contract labour |
| OWNERSHIP | Promoters Muthuraj Periyasamy (Chairman and MD) and Jayendran hold 81.93% with group; neither is selling |
| THE ACCESS POINT Renfra Energy is unlisted and awaiting SEBI observations. No price band or dates are published. A pre-IPO placement of up to ₹50 crore may occur first. |
|---|
Executive decision summary
| THE BOTTOM LINE Renfra Energy builds solar and wind plants for utilities and commercial customers, mainly in Tamil Nadu and the south, and maintains plants it or others built. FY26 was a step change: total income doubled to ₹1,018 crore and profit rose 66% to ₹156.8 crore, with a 24% EBITDA margin. The ₹430 crore fresh issue mainly redeems ₹160 crore of debentures and adds working capital. The same year borrowings jumped from ₹3.4 crore to ₹268.1 crore, and the order book quoted by one source (about ₹517 crore, May 2026) covers only about six months of FY26 revenue. A contractor that doubles revenue in a year, funds it with debt and reports a thin order book needs its prospectus tested on receivables, customer concentration and project timing before any price is accepted. |
|---|
| WHICH INVESTOR Fits you IF you want a profitable renewable-EPC contractor with fresh capital and a promoter who is not selling. Look elsewhere IF you want order-book visibility or a debt-light balance sheet: both are open questions in the public summaries. |
|---|
| COMFORT FIT Renfra = the construction contractor behind solar and wind farms: it builds them for owners and then maintains them. KPI Green Energy, KP Energy, Solarworld Energy Solutions, Zodiac Energy = peers named in the DRHP papers. EPC = engineering, procurement and construction: a project is delivered for a fixed contract price. |
|---|
| THE RUPEIA NUMBER ₹268 crore. Borrowings at March 2026, up from ₹3.4 crore a year earlier. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
A = government or regulator record. B = statutory filing. C = independent press. D = company announcement.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Fresh issue ₹430 crore; OFS 47,94,800 shares; pre-IPO ≤₹50 crore; BRLM Unistone Capital | Chittorgarh; Kotak Neo; Free Press Journal (PTI); Mercom | A/B | Established. |
| DRHP 30 Jun / 1 Jul 2026 | Chittorgarh narrative and table; FPJ | B | Dates differ by a day. |
| Total income ₹446.73 / 511.43 / 1,018.22 crore; EBITDA ₹55.41 / 131.08 / 245.94 crore; profit ₹36.86 / 94.55 / 156.82 crore (FY24 / FY25 / FY26) | Chittorgarh (restated consolidated) | B | Established. |
| Net worth ₹48.64 / 252.59 / 466.30 crore; borrowings ₹3.43 crore (FY25), ₹268.07 crore (FY26) | Chittorgarh | B | Debt breakdown not found. |
| Objects: NCD redemption ₹160 crore; working capital ₹70 crore or ₹175 crore | Kotak Neo and FPJ (₹70 crore); Mercom (₹175 crore) | B/C | Conflict. |
| 462.35 MW built; 139.10 MW ongoing; ~601.40 MW O&M | Chittorgarh; Kotak Neo; Mercom | B | O&M figure exceeds EPC total without explanation. |
| Order book ~₹517 crore (May 2026) | Mercom only | C | MW basis not found. |
| Chittorgarh objects text says "100% OFS" | Chittorgarh | C | Contradicts its own ₹430 crore fresh issue; treated as error. |
2 COMPANY OVERVIEW & FOUNDING STORY
Renfra Energy India was incorporated in 2017 and is headquartered in Chennai. Muthuraj Periyasamy (Chairman and Managing Director) and Jayendran (Executive Director) are the promoters. The company delivers solar and wind projects on an EPC or turnkey basis for utility-scale and commercial and industrial customers, offers operations and maintenance (O&M), and also sells land parcels linked to projects.
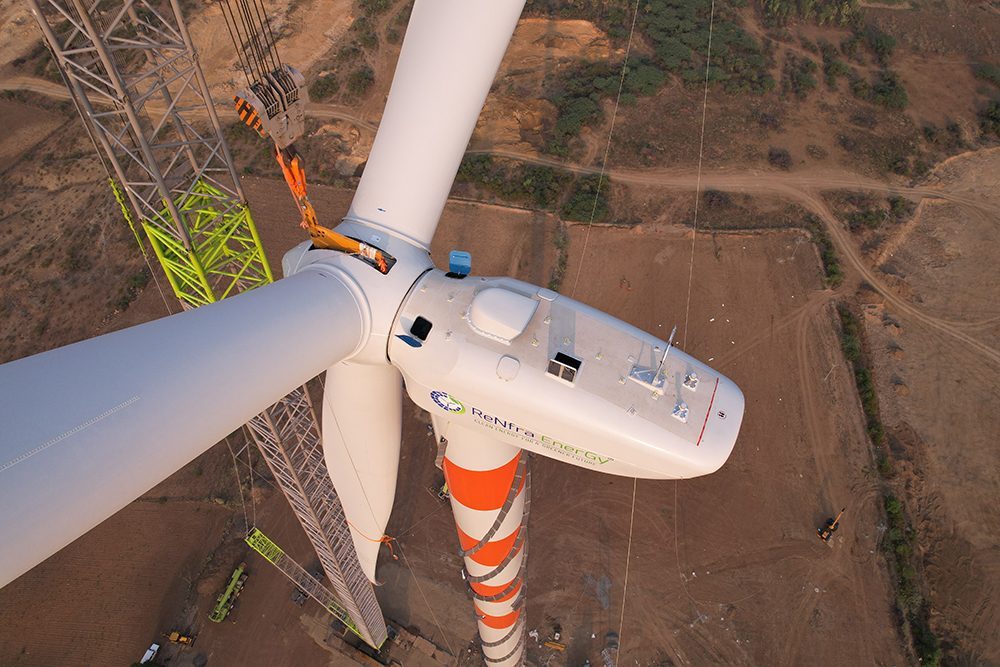
As of 15 May 2026 it had executed 462.35 MW of projects, 412.85 MW solar and 49.50 MW wind, and had 139.10 MW under way (83.00 MW solar and 56.10 MW wind). It reports 217 contracts, 164 EPC and 53 O&M, with 164 customers, and 159 component vendors (128 solar, 31 wind).
It employs 1,140 people at 15 May 2026, of whom 457 are permanent and 683 contract labourers. Sources describe its work as concentrated in Tamil Nadu, Puducherry and the rest of South India. Customer names, concentration and revenue by segment were not found.
3 TIMELINE
| Date | Event |
|---|---|
| 2017 | Incorporated |
| FY24 | Total income ₹446.7 crore; profit ₹36.9 crore |
| FY25 | Total income ₹511.4 crore (+14.5%); profit ₹94.6 crore (+156%); net worth rises to ₹252.6 crore |
| FY26 | Total income ₹1,018.2 crore (+99%); profit ₹156.8 crore; borrowings ₹268.1 crore |
| 15 May 2026 | 462.35 MW executed; 139.10 MW under execution |
| 30 Jun–1 Jul 2026 | DRHP filed |
| 27 Oct 2026 | Chittorgarh page updated; no price band or dates |
4 OFFER STRUCTURE, OBJECTS AND SELLERS
| Item | Detail | Figure | Comment |
|---|---|---|---|
| Fresh issue | New shares | ₹430 crore | Reduced by any pre-IPO placement |
| Offer for sale | 26 non-promoter holders | 47,94,800 shares | 2.8% of 16.95 crore pre-issue shares |
| Pre-IPO placement | Optional | Up to ₹50 crore | Reduces fresh issue |
| Object 1 | Redeem NCDs | ₹160 crore | 37% of fresh issue |
| Object 2 | Working capital | ₹70 crore (or ₹175 crore) | Sources conflict |
| Object 3 | General corporate purposes | ₹200 crore or ₹95 crore (balance) | Rupeia arithmetic from either working-capital figure |
| Reservation | Net offer | QIB ≤50%, NII ≥15%, retail ≥35% | — |
The largest seller is Arumuga Raja (12,60,900 shares, 26% of the OFS), followed by Mangal Keshav Capital (4,34,310) and Deep Ashokbhai Sanghvi (4,00,000); eleven holders sell 70,050 shares each. The promoters do not sell.
| RUPEIA CALCULATION Redeeming ₹160 crore of NCDs removes about 60% of the ₹268.07 crore of FY26 borrowings (160 ÷ 268.07). The ₹430 crore fresh issue is 92% of FY26 net worth (430 ÷ 466.30). If the working-capital object is ₹70 crore, about 47% of the fresh issue (₹200 crore) is unallocated general purposes; if it is ₹175 crore, the unallocated share is 22%. The RHP will settle which. |
|---|
5 FINANCIAL FORENSICS: DOUBLED REVENUE, DEBT-FUNDED
| ₹ crore (restated consolidated) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Total income | 446.73 | 511.43 | 1,018.22 |
| Growth | — | +14.5% | +99.1% |
| EBITDA | 55.41 | 131.08 | 245.94 |
| EBITDA margin on total income | 12.4% | 25.6% | 24.2% |
| Net profit | 36.86 | 94.55 | 156.82 |
| PAT margin on total income | 8.3% | 18.5% | 15.4% |
| Net worth | 48.64 | 252.59 | 466.30 |
| Total borrowings | blank | 3.43 | 268.07 |
| Total assets | 134.15 | 393.44 | 996.28 |
| ROE / ROCE (Chittorgarh) | n/a | 62.77% / 81.53% | 43.63% / 49.58% |
Profit grew 156% in FY25 on only 14.5% revenue growth, then 66% in FY26 on 99% revenue growth, so FY25 was a margin year and FY26 a volume year. Total assets rose 2.5 times in FY26 (393.44 to 996.28), which means the balance sheet grew faster than revenue. Net worth rose by more than profit in both years: ₹204 crore against ₹94.6 crore in FY25, which implies about ₹109 crore of new equity or other additions (Rupeia inference).
| RUPEIA CALCULATION Order-book cover. The order book of about ₹517 crore is 0.51 times FY26 revenue from operations of ₹1,013 crore, about six months of work. A contractor that doubled revenue needs new orders continuously; the 139.10 MW under execution is the visible part. If FY27 revenue were flat at ₹1,013 crore, the company would need to win roughly ₹496 crore of new orders beyond the existing book (1,013 − 517) in addition to timing differences. This is an illustration; the MW basis of the order book is not in the sources. |
|---|
6 BUSINESS MODEL & UNIT ECONOMICS
Renfra earns fixed-price contract revenue for building plants and annual fees for running them.
| Line | How it earns | Pressure point |
|---|---|---|
| Solar EPC | Majority of income; 412.85 MW built, 83.00 MW ongoing | Module price swings; fixed-price contracts |
| Wind EPC | 49.50 MW built, 56.10 MW ongoing | Larger, lumpier projects |
| O&M | 53 agreements; ~601.40 MW under contract | Recurring but small relative to EPC |
| Land sales (project-linked) | Land parcels sold with approvals | Lumpy other income |
| Customers | Utility-scale and C&I; 164 customers | Concentration not disclosed |
EPC margins depend on buying equipment well, finishing on time and being paid promptly. Receivable days and unbilled revenue, not given in the sources, are the core diagnostic for this model.
7 MARKET & COMPETITIVE ANALYSIS
| Peer | Status | Position |
|---|---|---|
| KPI Green Energy | Listed | Named in the draft papers; financials not sourced |
| KP Energy | Listed | Named peer |
| Solarworld Energy Solutions | Listed | Named peer |
| Zodiac Energy | Listed | Named peer |
The papers name four listed peers but the sources do not give their multiples. Solar EPC names have traded at a wide range; the right comparison is live P/E and order-book cover on the day of the price band.
8 1. RENEWABLE EPC ECONOMICS
An EPC contractor wins a fixed-price contract, buys panels or turbines, builds and hands over the plant. Revenue is booked as work progresses; cash arrives in milestones. Margins are decided by procurement cost against contract price and by delays. Renfra's EBITDA margin of 24–26% is high for EPC work and suggests a mix that includes high-margin items, land sales or favourable procurement; the sources do not explain it.
| Feature | EPC contractor | Plant owner (IPP) |
|---|---|---|
| Revenue | Contract fees per project | Power sales over 25 years |
| Capital need | Working capital | Heavy long-term debt |
| Visibility | Order book (months) | Contracted tariffs (years) |
| Margin | Project margin | Operating margin on assets |
| Risk | Delays and cost overruns | Tariff and generation risk |
General description by Rupeia.
9 2. THE DEBT JUMP IN FY26
| Item (₹ crore) | FY25 | FY26 | Change |
|---|---|---|---|
| Borrowings | 3.43 | 268.07 | +₹264.6 crore |
| Total assets | 393.44 | 996.28 | +₹602.8 crore |
| Net worth | 252.59 | 466.30 | +₹213.7 crore |
| Borrowings ÷ net worth | 0.01 | 0.57 | — |
| NCDs to be redeemed | — | 160 (part of borrowings) | 60% of FY26 debt |
Rupeia arithmetic from Chittorgarh figures.
Borrowings rose by ₹264.6 crore, about 44% of the ₹602.8 crore increase in assets; net worth supplied about 35%, and the balance of roughly 21% came from payables and other liabilities (Rupeia: 602.8 − 264.6 − 213.7 = 124.5). The structure suggests growth was financed partly by trade credit, which is common in EPC but reverses if suppliers tighten terms.
10 3. WHAT THE 462 MW AND 139 MW TELL US
| Metric | Figure | Note |
|---|---|---|
| Executed capacity | 462.35 MW | 412.85 MW solar + 49.50 MW wind |
| Under execution | 139.10 MW | 83.00 MW solar + 56.10 MW wind |
| Share of ongoing in wind | 40.3% | Rupeia: 56.10 ÷ 139.10; higher than the 10.7% wind share of executed capacity |
| O&M capacity | ~601.40 MW | Exceeds EPC total; basis not explained |
| EPC contracts / O&M contracts | 164 / 53 | 217 in total, 164 customers |
The ongoing pipeline tilts toward wind (40% against 11% of past work). Wind projects are larger and slower, which changes revenue timing and working capital; the RHP should show how the wind EPC experience compares with solar.
11 4. VALUATION GRID
| Post-issue value (₹ crore) | P/E on ₹156.82 cr | x EBITDA ₹245.94 cr* | x total income ₹1,018 cr | ₹430 cr as % of equity |
|---|---|---|---|---|
| 2,000 | 12.8x | 8.1x | 2.0x | 21.5% |
| 3,000 | 19.1x | 12.2x | 2.9x | 14.3% |
| 4,000 | 25.5x | 16.3x | 3.9x | 10.8% |
| 5,000 | 31.9x | 20.3x | 4.9x | 8.6% |
*Market value as a proxy for enterprise value; net debt after redemption not known. No valuation has been published. Rupeia arithmetic.
| RUPEIA CALCULATION Rupeia calculation: EPS on pre-issue shares is about ₹9.25 (₹156.82 crore ÷ 16.95 crore shares). A price of ₹185 a share (20x) would give a pre-issue market value of about ₹3,136 crore and, after ₹430 crore of new money, about ₹3,566 crore. The price band is not known; this shows how price and earnings link. Net worth shown by the source (₹466.30 crore) implies a share capital of about ₹0.12 crore, which cannot be right for 16.95 crore shares of ₹10; the RHP should reconcile it. |
|---|
12 5. GOVERNANCE AND OWNERSHIP
Promoters: Muthuraj Periyasamy and Jayendran, with group, hold 81.93%; neither sells in the OFS.
Sellers: 26 holders, most of them individuals and small funds, selling 2.8% of pre-issue equity; the largest is Arumuga Raja (26% of the OFS).
Lead manager: a single boutique banker, Unistone Capital; most mainboard issues of this size use two or more.
Labour model: 683 of 1,140 workers (60%) are contract labour, typical for EPC but a compliance item.
Unexplained items: O&M capacity above EPC capacity; net worth less reserves equal to about ₹0.12 crore; "100% OFS" wording on one page.
13 6. RISK MAP
| Risk | Mechanism | Where to look in the RHP |
|---|---|---|
| Order-book cover | ~₹517 crore ≈ 6 months of revenue | Order book by customer and MW |
| Receivables and working capital | EPC payments are milestone-based | Receivable and unbilled revenue days |
| Leverage | Borrowings up from ₹3.4 crore to ₹268 crore | Debt maturities; interest cost |
| Customer concentration | Few large utility or C&I clients | Top ten customer share |
| Regional concentration | Tamil Nadu and South India | Revenue by state |
| Policy and equipment costs | Module, turbine and tariff changes | Contract price clauses |
| Data inconsistencies | Working capital ₹70 crore vs ₹175 crore; share capital | RHP reconciliation |
14 7. QUESTIONS FOR THE RED HERRING PROSPECTUS
Order book in ₹ crore and MW, with customer split and execution timeline.
Receivable days, unbilled revenue and retention money.
Debt schedule: NCDs, bank limits, interest rate and covenants.
Revenue by solar, wind, O&M and land sales.
The reason for the EBITDA margin of 24–26%.
Working-capital object (₹70 crore or ₹175 crore) and the general-corporate-purposes balance.
Top customers and related-party transactions.
Price band and the pre-IPO placement terms.
15 8. GLOSSARY
| Term | Meaning |
|---|---|
| EPC | Engineering, procurement and construction contract |
| MW | Megawatt of generating capacity |
| O&M | Operations and maintenance contract |
| C&I | Commercial and industrial customers |
| NCD | Non-convertible debenture |
| Order book | Value of contracts won but not yet executed |
16 VALUATION SCENARIOS
| Scenario | Post-issue value (₹ crore) | P/E on FY26 | What must be true |
|---|---|---|---|
| Bear | 2,000 | 12.8x | Thin order book and debt dominate |
| Base | 3,000 | 19.1x | Growth continues; margin eases from peak |
| Bull | 4,500 | 28.7x | Large order wins and clean receivables |
Rupeia scenarios; no valuation has been published.
17 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 20% | SEBI clears; RHP shows a large order book and low receivable days; IPO at 25x+ |
| Base | 45% | IPO at 15–20x earnings; growth slows to 25–30% |
| Bear | 35% | Order-book or receivables concerns delay or cut the issue |
18 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Kill condition |
|---|---|---|
| Thin order book (~6 months of revenue) | High | RHP order book |
| Debt-funded growth | High | Borrowings above ₹268 crore |
| Margin sustainability at 24% | Medium | Quarterly margin |
| Customer concentration | Medium | Top ten share |
| Execution of wind projects | Medium | Delays |
| Disclosure inconsistencies | Medium | RHP reconciliation |
19 INVESTOR CLASS ANALYSIS
HNIs and family offices
Wait for the RHP. The decisive items are order book, receivable days and what the ₹160 crore NCD redemption leaves of the debt load.
Institutions
Institutions will test margin quality, receivables and order conversion.
NRIs
NRIs can hold unlisted Indian shares under FEMA pricing and reporting rules; repatriation depends on the account route used.
20 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Q4 2026–2027 | SEBI observations; RHP; price band |
| Optional | Pre-IPO placement of up to ₹50 crore |
| Ongoing | Commissioning of the 139.10 MW pipeline |
21 RUPEIA FINAL INDEPENDENT VIEW
Renfra shows fast growth and strong returns with a sudden debt build and a short order book. The numbers invite a premium; the prospectus must earn it.
| THE RUPEIA NUMBER ₹268 crore. Borrowings at March 2026, up from ₹3.4 crore a year earlier. |
|---|
| RUPEIA VERDICT Fast-growing EPC with open diligence questions. Wait for the RHP. |
|---|
Frequently asked questions
How big is Renfra Energy's IPO?
A fresh issue of ₹430 crore plus an offer for sale of 47.94 lakh shares by 26 non-promoter holders.
What are Renfra's FY26 income and profit?
Total income ₹1,018.22 crore and profit ₹156.82 crore.
How much capacity has Renfra built?
462.35 MW (412.85 MW solar and 49.50 MW wind), with 139.10 MW under execution.
What will the fresh issue fund?
₹160 crore to redeem NCDs, working capital (₹70 crore or ₹175 crore by source) and general purposes.
Has SEBI cleared it?
No observation letter was found in the sources read.
Source log
Chittorgarh: Renfra Energy India IPO
Kotak Neo: Renfra Energy files IPO papers
Free Press Journal (PTI): Renfra Energy files DRHP
Mercom India: Renfra Energy files draft papers
Renewable Watch: Renfra Energy files DRHP
Business Today: Renfra Energy, Innoterra, GNI Infra file DRHPs
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|