Encube Ethicals: ₹3,000 crore offer for sale
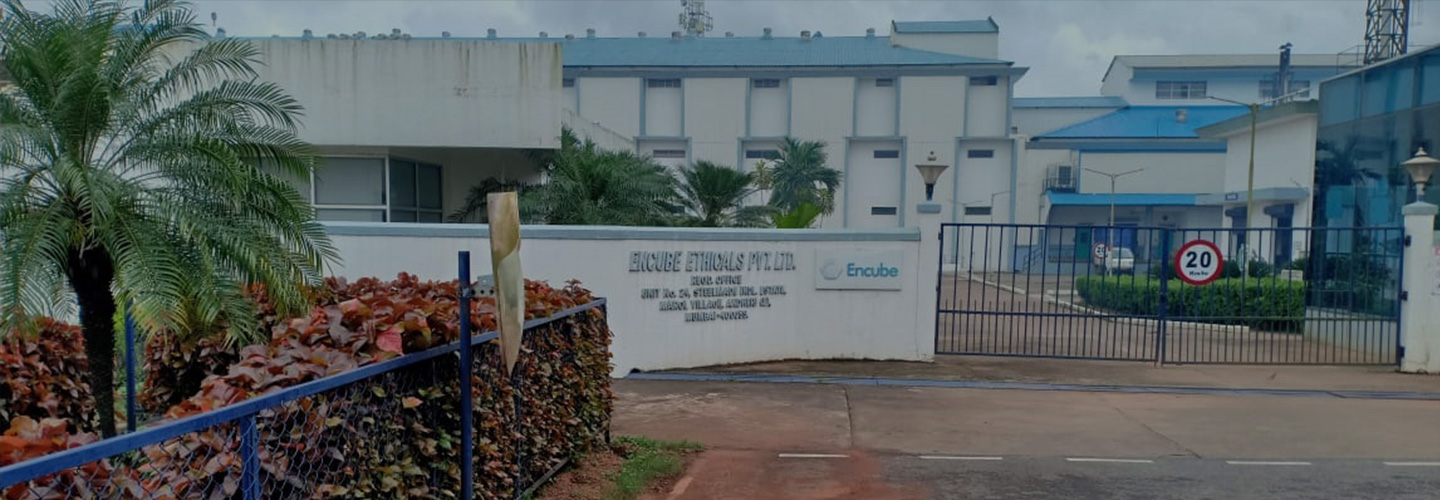
Independent report content
| OFFER | Book-built OFS only, up to ₹3,000 crore; promoter Mehul Madhusudan Shah about ₹2,000 crore and Frontier Investment Holdings about ₹1,000 crore (Chittorgarh estimates); no proceeds to the company |
|---|---|
| FILING | DRHP filed 1–3 Aug 2026 (sources differ) · SEBI approval 4 Nov 2026 per Chittorgarh only, valid 12 months |
| LEAD MANAGERS | JM Financial, Axis Capital, Kotak Mahindra Capital; registrar MUFG Intime |
| FY26 (RESTATED CONSOLIDATED) | Total income ₹1,911.8 crore (+39.6%) · EBITDA ₹663.3 crore · profit ₹436.7 crore (+75.0%) · net worth ₹1,953.6 crore · borrowings ₹221.7 crore |
| RETURNS | ROE 25.65% · ROCE 32.30% · debt/equity 0.13 · EPS ₹14.37 · NAV ₹64.29 |
| MIX | Global Generics 47% · Global CDMO 42% · India Branded 9% of FY26 revenue; global customers 64%, India 36% |
| FOOTPRINT | Goa and Indore plants; 15,624 tonnes capacity; 807 million units of filling/packing; 50 countries; 160+ CDMO customers |
| SHAREHOLDING | Promoter group 80.63%; Frontier Investment Holdings 15.02%; pre-issue shares 30.39 crore |
| THE ACCESS POINT Encube Ethicals is unlisted; the IPO is the route. No price band, issue dates or lot size have been announced. Because the offer is entirely a sale by existing holders, there is no fresh capital for the company. |
|---|
Executive decision summary
| THE BOTTOM LINE Encube Ethicals makes topical and transdermal medicines (creams, gels, lotions and patches) for the US and other global markets, and sells contract-development services to more than 160 customers. FY26 numbers are strong by pharma standards: total income of ₹1,911.8 crore, EBITDA of ₹663 crore (34.7% of total income), profit of ₹436.7 crore and a 32% ROCE, with borrowings of only ₹222 crore. The IPO is an offer for sale of up to ₹3,000 crore by the promoter (about ₹2,000 crore) and Frontier Investment Holdings (about ₹1,000 crore). Profit grew 75% in FY26 and 60% in FY25, which is exactly why the questions are about durability: customer concentration, US pricing and regulatory inspection history are not disclosed in the summaries, and the filings dates and some figures differ by source. |
|---|
| WHICH INVESTOR Fits you IF you want a high-margin, low-debt, specialised pharma manufacturer with CDMO optionality, with disclosure to examine in the RHP. Look elsewhere IF you want a story of growth funded by the IPO: nothing goes to the company, and US generic pricing can move quickly. |
|---|
| COMFORT FIT Encube = a specialist in the hard-to-copy end of generics: creams and patches rather than tablets. CDMO = contract manufacturer that makes and develops products for other drug companies. The OFS = promoter and early investor partially cashing out. |
|---|
| THE RUPEIA NUMBER 75.0%. Growth in FY26 profit (₹249.6 crore to ₹436.7 crore). |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
A = government or regulator record. B = statutory filing. C = independent press. D = company announcement.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Book-built OFS only, up to ₹3,000 crore; JM Financial, Axis Capital, Kotak as BRLMs | Groww; Kotak Neo; Chittorgarh; FPJ; BioSpectrum | A/B | Established. |
| DRHP filed 1–3 Aug 2026 | Groww; Chittorgarh; FPJ | B | Dates differ. |
| SEBI approval 4 Nov 2026, valid 12 months | Chittorgarh | C | Single source. |
| FY24/FY25/FY26 total income ₹1,098.2 / 1,369.0 / 1,911.8 crore; EBITDA ₹297.6 / 452.1 / 663.3 crore; profit ₹156.1 / 249.6 / 436.7 crore | Chittorgarh (restated consolidated); Groww matches | B | Established. |
| FY26 revenue from operations ₹1,848.7 crore (+37.5%) | Kotak Neo; FPJ; BioSpectrum | B | Different base from total income. |
| Promoter group 80.63%; Frontier 15.02% | Chittorgarh; Kotak Neo | B/C | Shah's own holding not found. |
| Revenue mix 47/42/9; customers 64% global, 36% India | Kotak Neo | B/C | Mix sums to 98%. |
| Capacity 15,624 tonnes; 807 million units; Goa approvals from 11 authorities | Kotak Neo; FPJ | C | Reported. |
| Quadria Capital backs Frontier | Kotak Neo headline only | C | Other sources silent; role of Quadria unclear. |
2 COMPANY OVERVIEW & FOUNDING STORY
Encube Ethicals Limited was incorporated in September 1995 and is headquartered in Mumbai. It describes itself as a specialty pharmaceutical formulations company focused on technically complex topical and transdermal dosage forms: creams, gels, lotions, patches and hormone products. It has three verticals: Global Generics, Global CDMO and India Branded Formulations.
It operates two manufacturing sites, in Goa and Indore, and a USFDA-approved R&D centre. The Goa facility is reported to hold approvals from 11 regulators, including USFDA, EU GMP, Japan PMDA, Health Canada, Brazil ANVISA, Australia TGA and the Eurasian Economic Union. Filling and packaging capacity is 807 million units, which the company says is about 2.8 times total US topical demand in FY26.
It had 1,695 permanent employees and 982 factory workers at 31 March 2026 per Chittorgarh (another source says 1,684). It sells to customers in about 50 countries.
3 TIMELINE
| Date | Event |
|---|---|
| Sep 1995 | Incorporated |
| FY24 | Total income ₹1,098.2 crore; profit ₹156.1 crore |
| FY25 | Total income ₹1,369.0 crore (+24.7%); profit ₹249.6 crore (+59.9%) |
| FY26 | Total income ₹1,911.8 crore (+39.6%); profit ₹436.7 crore (+75.0%) |
| 1–3 Aug 2026 | DRHP filed for ₹3,000 crore OFS |
| 4 Nov 2026 | SEBI approval per Chittorgarh |
4 OFFER STRUCTURE AND SELLERS
| Item | Detail | Figure | Comment |
|---|---|---|---|
| Offer | Book-built OFS | Up to ₹3,000 crore | No fresh issue |
| Seller 1 | Mehul Madhusudan Shah (promoter) | ~₹2,000 crore | Chittorgarh estimate; share count not given |
| Seller 2 | Frontier Investment Holdings Pte. Ltd. | ~₹1,000 crore | Holds 15.02% |
| Pre-issue shares | Equity | 30,38,84,790 | Unchanged after issue |
| Face value | Per share | ₹1 | — |
| Reservation | Net offer | QIB ≤50%, NII ≥15%, retail ≥35% | — |
| Price band, dates | Not announced | — | — |
Quadria Capital is named as the backer of Frontier in one headline; no source gives its own stake. Mehul Shah is described as promoter; his individual holding and any founder role are not stated.
| RUPEIA CALCULATION If Frontier sold all of its 15.02% for about ₹1,000 crore, the implied equity value would be about ₹6,658 crore (₹1,000 crore ÷ 0.1502), or about 15.2x FY26 profit. That is a floor-type arithmetic check only, because the ₹1,000 crore is an estimate and Frontier may not be selling its whole stake. At higher valuations the same ₹3,000 crore is a smaller fraction: see the grid in the valuation section. |
|---|
5 FINANCIAL FORENSICS: THREE YEARS OF COMPOUNDING
| ₹ crore (restated consolidated) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Total income | 1,098.2 | 1,369.0 | 1,911.8 |
| Growth | — | +24.7% | +39.6% |
| EBITDA | 297.6 | 452.1 | 663.3 |
| EBITDA growth | — | +51.9% | +46.7% |
| EBITDA margin on total income | 27.1% | 33.0% | 34.7% |
| Net profit | 156.1 | 249.6 | 436.7 |
| Profit growth | — | +59.9% | +75.0% |
| PAT margin on total income | 14.2% | 18.2% | 22.8% |
| Net worth | 1,258.4 | 1,512.8 | 1,953.6 |
| Total borrowings | 228.1 | 230.5 | 221.7 |
| Total assets | 1,871.8 | 2,300.1 | 2,792.1 |
Profit has grown faster than income for two years: margins widened from 14.2% to 22.8% (PAT) as operating leverage worked. Net worth rose 55% over two years with almost no change in debt. Revenue from operations in FY26 was ₹1,848.7 crore (+37.5%); the ~₹63 crore gap to total income is other income (Rupeia derivation).
| RUPEIA CALCULATION Conversion and returns: FY26 EBITDA of ₹663.3 crore became ₹436.7 crore of profit, a 65.8% conversion after depreciation, interest and tax. ROE of 25.65% and ROCE of 32.30% are high, helped by a modest equity base relative to earnings. Chittorgarh's 35.88% EBITDA margin uses revenue from operations (663.3 ÷ 1,848.7); on total income it is 34.7%. |
|---|
6 BUSINESS MODEL & UNIT ECONOMICS
Encube earns from developing and manufacturing hard-to-make topical and transdermal products.
| Line | How it earns | Pressure point |
|---|---|---|
| Global Generics (47% of FY26 revenue, ~₹869 crore) | Own-label and partner generics, mainly US topical | US pricing erosion; ANDA approvals |
| Global CDMO (42%, ~₹776 crore) | Development and manufacturing for 160+ customers in 50 countries | Customer concentration; project timing |
| India Branded Formulations (9%, ~₹166 crore) | Domestic branded medicines | Small; marketing spend |
| Capacity (807 million units) | Spare capacity relative to US demand claim | Utilisation not disclosed |
Topical and transdermal products are harder to formulate and to prove equivalent than tablets, which limits competition and supports margins. The CDMO line gives a second, less price-exposed revenue stream.
7 MARKET & COMPETITIVE ANALYSIS
| Peer | Status | Position |
|---|---|---|
| Glenmark, Taro (Sun Pharma), Perrigo | Listed | Topical generics players |
| Indoco Remedies, Akums, Syngene | Listed | CDMO and formulation peers |
| Alembic, Lupin, Zydus | Listed | Large Indian generic makers with US topical lines |
| Private CDMO and topical specialists | Private | Competition for development contracts |
Rupeia has not sourced live peer multiples here; Encube's margin and return profile (35% EBITDA, 32% ROCE) is above most Indian formulation companies, which is why the market may pay a premium and why the price band needs to be compared with peers on the day.
8 1. WHY TOPICAL AND TRANSDERMAL IS A NICHE
Topical generics (creams, gels, lotions, patches) are absorbed through the skin, so proving that a copy performs like the original needs more than a chemistry match. Manufacturing needs specialised mixing, stability and packaging. This raises the barrier to entry and the price a successful product can hold. The risk is that a few large US buyers set prices and that a regulatory finding at one plant halts shipments.
| Feature | Tablet generic | Topical / transdermal generic |
|---|---|---|
| Bioequivalence proof | Straightforward | Complex; often clinical-endpoint or skin-based |
| Number of competitors per product | Many | Fewer |
| Manufacturing | Standardised | Specialised mixing and filling |
| Price erosion | Fast | Slower, but real |
General industry description by Rupeia; no figures implied.
9 2. BUSINESS MIX AND WHAT IT IMPLIES
| Segment | Share of FY26 revenue | Approx. ₹ crore (Rupeia) | Comment |
|---|---|---|---|
| Global Generics | 47% | ~869 | Largest; US price-sensitive |
| Global CDMO | 42% | ~776 | Project-based; more than 160 customers |
| India Branded | 9% | ~166 | Domestic |
| Unexplained | 2% | ~37 | Percentages sum to 98% |
Revenue base ₹1,848.7 crore; percentages from Kotak Neo.
The CDMO share is unusually high for a generics company and may justify a different valuation lens: contract manufacturers are valued on visibility and utilisation, generics makers on pipeline and pricing.
10 3. CAPACITY AND REGULATORY PROFILE
| Item | Figure | Source |
|---|---|---|
| Plants | Goa and Indore | Kotak Neo |
| Total capacity | 15,624 tonnes | Kotak Neo |
| Filling and packaging | 807 million units | Kotak Neo |
| US topical demand (company claim) | ~288 million units implied by "2.8x" (Rupeia derivation) | Kotak Neo |
| Goa approvals | 11 authorities incl. USFDA, EU GMP, PMDA, Health Canada, ANVISA, TGA, EAEU | FPJ; Kotak Neo |
| R&D | USFDA-approved R&D centre | Groww |
| USFDA inspection history, 483s, warning letters, ANDA count, R&D spend | Not found in sources | — |
The absence of inspection history in the summaries is the single largest information gap for a pharma exporter. The prospectus will set out any observations and their resolution.
11 4. RETURNS, BALANCE SHEET AND CAPITAL EFFICIENCY
| Metric (31 Mar 2026) | Figure |
|---|---|
| ROE | 25.65% |
| ROCE | 32.30% |
| RoNW | 25.21% |
| Debt / equity | 0.13 (221.7 ÷ 1,953.6 = 0.11 on Rupeia's arithmetic) |
| NAV per share | ₹64.29 |
| EPS (FY26) | ₹14.37 (436.7 ÷ 30.39 crore shares) |
The small gap between reported and recomputed debt/equity probably reflects the definition of debt used; it is not material to the thesis.
12 5. VALUATION GRID
| Valuation (₹ crore) | P/E on ₹436.7 cr | x EBITDA ₹663.3 cr | x total income ₹1,911.8 cr | ₹3,000 cr as % of equity |
|---|---|---|---|---|
| 10,000 | 22.9x | 15.1x | 5.2x | 30.0% |
| 15,000 | 34.3x | 22.6x | 7.8x | 20.0% |
| 20,000 | 45.8x | 30.2x | 10.5x | 15.0% |
| 25,000 | 57.2x | 37.7x | 13.1x | 12.0% |
Market value used as proxy for enterprise value; net cash is not in the sources. Rupeia arithmetic. No valuation has been published.
| RUPEIA CALCULATION Rupeia calculation: if profit grows 20% a year for five years (1.2^5 = 2.49x) and the multiple holds at 34x, the investor earns about 20% a year. If the multiple compresses from 34x to 20x over the same period, the return falls to about 7.9% a year ((2.49 × 20 ÷ 34)^(1/5) − 1). At high multiples, compression matters as much as growth. Illustration only. |
|---|
13 6. OWNERSHIP AND THE SELLERS
| Holder | Stake | Role in offer |
|---|---|---|
| Promoter group | 80.63% pre-issue | Mehul Madhusudan Shah sells ~₹2,000 crore (estimate) |
| Frontier Investment Holdings Pte. Ltd. | 15.02% | Sells ~₹1,000 crore (estimate) |
| Others | ~4.35% (remainder) | Not stated |
| Post-issue public float | 19.37% (Chittorgarh) | Figure as shown by the source |
If the valuation were ₹15,000 crore, the promoter's ₹2,000 crore would be about 13.3% of equity and Frontier's ₹1,000 crore about 6.7%. The promoter group would fall from 80.63% to about 67.3% and Frontier from 15.02% to about 8.3% (Rupeia arithmetic, assuming the estimated amounts are right). The 19.37% post-issue public float shown on one page does not appear to reflect a sale of that size.
14 7. RISK MAP FOR A US-EXPOSED TOPICAL GENERICS COMPANY
| Risk | Mechanism | Where to look in the RHP |
|---|---|---|
| US price erosion | More approvals or buyer consolidation cut prices | Revenue by product and price trend |
| Customer concentration | A few distributors or CDMO clients | Top ten customer share |
| Regulatory action | Warning letter or import alert at Goa or Indore | Inspection history |
| Tariffs and trade policy | US duties on pharma imports | Risk factors; management commentary |
| Key-person dependence | Promoter-led business | Management and governance chapters |
| Foreign-exchange | Most revenue in US dollars | Hedging policy |
15 8. QUESTIONS FOR THE RED HERRING PROSPECTUS
Price band, lot size and final sellers' share counts.
Top ten customers and top three products as a share of revenue.
ANDA filings, approvals and pipeline count; R&D spend.
USFDA and other inspection outcomes at Goa and Indore.
Capacity utilisation by plant.
Quadria Capital's role and holding, if any.
Related-party transactions, contingent liabilities and tax disputes.
Dividend policy after the offer.
16 9. GLOSSARY
| Term | Meaning |
|---|---|
| CDMO | Contract development and manufacturing organisation |
| Topical / transdermal | Applied to or through the skin |
| ANDA | Abbreviated New Drug Application to the USFDA for generics |
| USFDA 483 / warning letter | Inspection observations and escalated regulatory action |
| RoNW / ROCE | Return on net worth; return on capital employed |
| OFS | Offer for sale by existing shareholders |
17 VALUATION SCENARIOS
| Scenario | Value (₹ crore) | P/E on FY26 | What must be true |
|---|---|---|---|
| Bear | 10,000 | 22.9x | US pricing and concentration concerns weigh |
| Base | 17,500 | 40.1x | Margins hold; CDMO adds stability |
| Bull | 25,000 | 57.2x | Growth continues near 40%; clean inspection record |
Rupeia scenarios; no valuation has been published by the company.
18 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 25% | Priced at 40–55x earnings; growth sustained; clean regulatory file |
| Base | 45% | Priced near 30–40x; FY27 growth slows to 20–25% |
| Bear | 30% | US price erosion, a regulatory finding or market weakness delays or cuts the IPO |
19 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Kill condition |
|---|---|---|
| US generic pricing | High | Product-level price trends in the RHP |
| Customer concentration | High | Top ten customer share |
| Regulatory inspection at Goa or Indore | High | 483 observations or warning letter |
| High valuation after 75% profit growth | Medium | Price band vs 30–45x earnings |
| OFS-only: no growth capital | Medium | Capex plan funded from internal accruals |
| Disclosure differences between sources | Medium | RHP numbers vs summaries |
| Tariffs and trade policy | Medium | US measures on pharma imports |
20 INVESTOR CLASS ANALYSIS
HNIs and family offices
Compare the price band with listed Indian formulation and CDMO peers on live quotes and be sceptical of any grey-market price; the profit curve (+60%, +75%) is steep and may not repeat.
Institutions
Institutional investors will look for customer concentration, inspection history and the rationale for Frontier's exit.
NRIs
NRIs can hold unlisted Indian shares under FEMA pricing and reporting rules; repatriation depends on the account route used.
21 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Nov–Dec 2026 | Possible RHP and price band |
| Q3 FY27 | First results if listed |
| Ongoing | USFDA inspections; ANDA approvals |
22 RUPEIA FINAL INDEPENDENT VIEW
Encube is a profitable, low-debt specialist with a steep earnings curve. Its returns and margins are high enough to justify a premium, and the prospectus gaps (customers, inspections, pipeline) are where the real due diligence sits.
| THE RUPEIA NUMBER 75.0%. Growth in FY26 profit (₹249.6 crore to ₹436.7 crore). |
|---|
| RUPEIA VERDICT Quality financial profile; diligence gaps. Wait for the band. |
|---|
Frequently asked questions
What is Encube Ethicals' IPO size?
Up to ₹3,000 crore, entirely an offer for sale.
Who is selling?
Promoter Mehul Madhusudan Shah (about ₹2,000 crore) and Frontier Investment Holdings (about ₹1,000 crore), per Chittorgarh estimates.
What were FY26 profit and EBITDA?
Profit ₹436.7 crore and EBITDA ₹663.3 crore on total income of ₹1,911.8 crore.
What does Encube make?
Topical and transdermal formulations (creams, gels, lotions, patches), contract development and manufacturing, and domestic branded medicines.
Is Quadria Capital a seller?
Sources conflict: one headline links Quadria to Frontier; others do not mention it.
Source log
Groww: Encube Ethicals files DRHP for ₹3,000 crore
Kotak Neo: Quadria-backed Encube Ethicals files DRHP
Chittorgarh: Encube Ethicals IPO details
Free Press Journal (PTI): Encube Ethicals files papers
BioSpectrum India: Encube Ethicals files DRHP
Business Today: Encube Ethicals DRHP
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|