Sagar Defence Engineering: ₹300 crore pre-IPO at ₹20,000 crore
Independent report content
| SEBI STATUS | Confidential DRHP submitted 5–6 Aug 2026 · observations 4 Nov 2026 (valid 18 months, per Chittorgarh) |
|---|---|
| PRE-IPO ROUND | ₹300 crore (about US$33 million) from unnamed domestic institutions, announced 6 Nov 2026; valuation ₹20,000 crore before the new money |
| IPO SIZE | Not announced; earlier reports estimated ₹2,000–3,000 crore; fresh issue vs OFS split not announced |
| REVENUE | FY25 operating income about ₹104 crore (Venture Intelligence summary); other years and profit not found |
| BUSINESS | Unmanned marine surface vehicles and autonomous systems; retrofit kits that convert existing vessels; vertically integrated |
| LICENCE | Industrial licence (reported 10 Sep 2026) to manufacture surface and underwater vessels for military use, subject to conditions; issuer not named in the source |
| FOUNDER | Capt. Nikunj Parashar, founder and chairman; incorporated May 2015 |
| LEAD MANAGERS | JM Financial (named as BRLM); one page lists IIFL Capital, Kotak and UBS as well |
| THE ACCESS POINT Sagar Defence is unlisted. There is no price band, issue size or date. The pre-IPO round was placed with institutions, not the public. Retail access is only through the IPO. |
|---|
Executive decision summary
| THE BOTTOM LINE Sagar Defence Engineering builds unmanned and autonomous marine systems for the Indian armed forces and has the regulatory approvals to broaden into military vessels. The company raised ₹300 crore pre-IPO at a ₹20,000 crore valuation days after SEBI cleared its draft, on the back of a business whose only published revenue figure is about ₹104 crore of operating income in FY25. That is roughly 190 times revenue. No profit, order book or customer list was found in any source, which makes this the thinnest-disclosed report in the archive relative to its valuation. The story is real: a 2015 start-up from a 150 sq ft workspace, an Indian Navy-linked appearance, a military licence. The question for investors is whether the draft prospectus supports a multiple that the market normally reserves for proven defence compounders. |
|---|
| WHICH INVESTOR Fits you IF you want to follow India's unmanned-maritime defence theme and are prepared to wait for audited figures in the RHP. Look elsewhere IF you want valuation support today: the only revenue figure found is about ₹104 crore against a ₹20,000 crore price. |
|---|
| COMFORT FIT Sagar Defence = a drone-boat maker that wants to become a naval shipbuilder. ideaForge, Zen Technologies, Data Patterns = listed Indian defence-technology companies against which it will be compared. The pre-IPO round = a last private price before the public one, set while the revenue base is small. |
|---|
| THE RUPEIA NUMBER ~190x. The ₹20,000 crore pre-money valuation divided by FY25 operating income of about ₹104 crore. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
A = government or regulator record. B = statutory filing. C = independent press. D = company announcement.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Pre-IPO ₹300 crore (~US$33 million) at ₹20,000 crore valuation before new money; investors unnamed | India Sentinels (6 Nov 2026); Raksha Anirveda headline | B/C | Dollar conversions are the source's. |
| SEBI observations 4 Nov 2026; confidential DRHP filed 5–6 Aug 2026 | Chittorgarh; Groww | B | Established. |
| FY25 operating income ~₹104 crore | Venture Intelligence | C | Single source; basis not stated. |
| Industrial licence for surface and underwater military vessels (10 Sep 2026) | The Week (PTI) | B/C | Issuer and number not stated. |
| Founded 2015 by Capt. Nikunj Parashar; began in a 150 sq ft workspace | Chittorgarh; India Sentinels | B | Co-founders unnamed. |
| Unmanned marine vehicle inducted into/supplied to the Indian Armed Forces | Chittorgarh; Groww | C | No service, quantity or date given. |
| IPO estimate ₹2,000–3,000 crore | Venture Intelligence; IPO Central headline | C | Estimate. |
| Lead managers: JM Financial; four names on one page | Chittorgarh; Groww | C | Pages conflict. |
2 COMPANY OVERVIEW & FOUNDING STORY
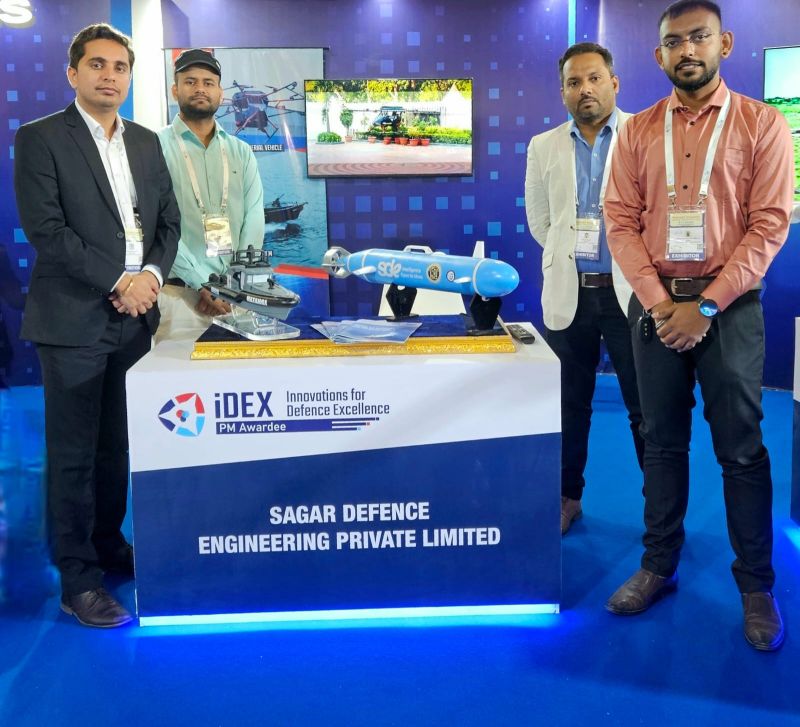
Sagar Defence Engineering was incorporated in May 2015 by Capt. Nikunj Parashar, who has a maritime background, and started in about 150 square feet of workspace. It makes unmanned marine surface vehicles (UMSVs) that collect and communicate ocean data in real time, plus retrofit systems that turn existing vessels into autonomous or remotely operated ones, using optical, AIS and acoustic sensors. The company describes itself as vertically integrated across research, design, engineering and manufacturing.
Operations are described in Mumbai (registered contact address in Borivali East), with manufacturing and research expansion in Pune, and an "Autonomous Systems Shipyard" and "Maritime Systems Research Centre" being developed in Andhra Pradesh; sizes and status are not given. Press describes the company as Maharashtra-based.
One source says it builds marine and aerial systems; the other pages mention only marine vehicles. Its marine vehicle is described as inducted into or supplied to the Indian Armed Forces, without a service, quantity or date. In September 2026 it was reported to have received an industrial licence to manufacture surface and underwater military vessels, after an earlier licence for arms, explosives and ammunition.
3 TIMELINE
| Date | Event |
|---|---|
| May 2015 | Incorporated; founded by Capt. Nikunj Parashar |
| 2016 | MIS 2016–DP World Prize (Ministry of Shipping, Invest India, DP World) |
| FY25 | Operating income about ₹104 crore (Venture Intelligence) |
| Months before Sep 2026 | Earlier licence for arms, explosives and ammunition (date not given) |
| 5–6 Aug 2026 | Confidential DRHP filed |
| 10 Sep 2026 | Industrial licence for military surface and underwater vessels reported |
| 26–27 Oct 2026 | Founder speaks at Swavlamban 2026, the Navy's innovation seminar |
| 4 Nov 2026 | SEBI observations |
| 6 Nov 2026 | ₹300 crore pre-IPO round announced at ₹20,000 crore |
4 PRE-IPO ROUND, IPO PLAN AND WHAT IS DISCLOSED
| Item | Detail | Figure | Comment |
|---|---|---|---|
| Pre-IPO round | Domestic institutional investors (unnamed) | ₹300 crore (~US$33 million) | Use: R&D, autonomous systems, advanced manufacturing, indigenous technology |
| Pre-money valuation | Stated "before the new money" | ₹20,000 crore (~US$2.2 billion) | Post-money = ₹20,300 crore (Rupeia) |
| IPO size | Estimate | ₹2,000–3,000 crore | Not confirmed; split between fresh issue and OFS not announced |
| Lead managers | JM Financial; one page adds IIFL, Kotak, UBS | — | Conflict |
| Registrar, price band, dates | Not announced | — | — |
The company says it has "received SEBI's final observations and has successfully concluded our pre-IPO fundraising round". Investor names, share counts and the price per share of the round were not disclosed.
| RUPEIA CALCULATION The ₹300 crore bought about 1.5% of the company (₹300 crore ÷ ₹20,300 crore post-money). An IPO of ₹2,000–3,000 crore would be about 9.9–14.8% of ₹20,300 crore, before any listing premium or discount. A price set at ₹20,000 crore means public investors would be asked to pay the pre-IPO price, with the pre-IPO investors holding a security that costs them the same. |
|---|
5 FINANCIAL FORENSICS: WHAT CAN AND CANNOT BE SAID
| Metric | Figure | Source | Comment |
|---|---|---|---|
| FY25 operating income | ~₹104 crore | Venture Intelligence | Single source |
| Valuation ÷ FY25 operating income | ~192x (₹20,000 crore ÷ ₹104 crore) | Rupeia | Before new money |
| Post-money ÷ FY25 operating income | ~195x | Rupeia | ₹20,300 crore ÷ ₹104 crore |
| Profit, EBITDA, order book | Not found | — | Draft figures not in sources read |
| Employees, shareholding | Not found | — | — |
Without profit or order-book data no earnings-based valuation is possible. The RHP will be the first document where revenue growth, margins and customer concentration can be assessed.
| RUPEIA CALCULATION What growth would justify ₹20,000 crore? If the company earned a 15% net margin at maturity and the market paid 40x earnings, it would need profit of about ₹500 crore, which is revenue of about ₹3,333 crore (₹500 crore ÷ 0.15). From ₹104 crore that is 32 times in revenue terms; at 40% annual growth it would take about 10.3 years (ln 32 ÷ ln 1.4). These margin and multiple inputs are Rupeia assumptions to show the scale of the hurdle, not forecasts. |
|---|
6 BUSINESS MODEL & UNIT ECONOMICS
Sagar Defence sells unmanned and autonomous marine systems and related engineering to defence and commercial customers.
| Line | How it earns | Pressure point |
|---|---|---|
| Unmanned marine surface vehicles | Platforms for surveillance, hydrographic surveys, ocean data and rescue | Procurement cycles; limited public order detail |
| Retrofit autonomy kits | Convert existing vessels to unmanned or remotely operated | Depends on vessel owners and approvals |
| Military vessel manufacturing (licensed) | Surface and underwater vessels for naval defence, subject to conditions | Early; capital intensive |
| Commercial and research uses | Offshore operations, ocean sensing, disaster management | Smaller markets |
Defence revenue comes from government tenders, trials and repeat orders. A small company with a few large buyers can see revenue swing sharply from year to year, which makes the order book and receivable days the key items in the prospectus.
7 MARKET & COMPETITIVE ANALYSIS
| Peer | Status | Position |
|---|---|---|
| ideaForge Technology | Listed | Drone maker; reference for unmanned-systems valuations |
| Zen Technologies, Data Patterns | Listed | Defence technology companies |
| Cochin Shipyard, Mazagon Dock, GRSE | Listed PSU shipbuilders | Naval platform builders the licence puts it near |
| Other private unmanned and maritime start-ups | Private | Competitors for naval trials |
Rupeia has not sourced peer multiples for this report. The listed names above are the comparison set the market will likely use; their current multiples should be taken from live quotes at the time of the price band.
8 1. WHAT AN UNMANNED SURFACE VESSEL DOES
An unmanned surface vessel is a boat with no crew on board that operates autonomously or by remote control. In defence it is used for patrol, surveillance, mine detection, harbour security and as a platform for sensors or payloads, reducing risk to crews and cost per hour. Sagar Defence also sells retrofit systems that add autonomy to vessels already in service, which lowers the buyer's cost of adoption.
| Capability | Use | Buyer |
|---|---|---|
| Autonomous navigation | Patrol and survey without a crew | Navy, Coast Guard, port authorities |
| Optical, AIS and acoustic sensing | Detect vessels and underwater objects | Defence and maritime agencies |
| Retrofit kits | Convert existing boats | Fleet owners |
| Ocean data collection | Hydrography and research | Government and commercial users |
Capabilities as described by Chittorgarh and Groww; no technical specifications are published in the sources.
9 2. THE LICENCE: WHAT IS AND IS NOT KNOWN
| Item | Detail |
|---|---|
| Reported date | 10 September 2026 (PTI via The Week) |
| What it covers | Design, manufacture, construction, integration, assembly and testing of specified naval defence platforms: surface and underwater vessels for military use |
| Conditions | "Subject to regulatory approvals and licence conditions" |
| Issuing authority and licence number | Not stated in the source read |
| Earlier licence | Arms, explosives and ammunition, a few months earlier |
| What it is not | An order: no Navy or Coast Guard contract is named |
A manufacturing licence lets a company bid for and build such platforms; it does not itself bring revenue. The market value attached to the licence depends on whether tenders follow.
10 3. HOW INDIAN DEFENCE PROCUREMENT SHAPES REVENUE
Defence demand is lumpy. Orders are placed after trials and evaluation, often with indigenisation preferences, and revenue is recognised on delivery or milestones. For a company of this size, a single contract can move annual revenue by tens of per cent. Investors should read, in the RHP, the order book at a recent date, its conversion into revenue over the next 12–24 months, and the share of the largest customer.
| Disclosure to look for | Why it matters |
|---|---|
| Order book and execution period | Visibility of the next two years of revenue |
| Largest customer share | Concentration risk |
| Receivable days | Government payment delays tie up cash |
| Advance payments and guarantees | Cash cycle and bank-guarantee limits |
| Export share | Diversification away from one buyer |
11 4. VALUATION: THE 190X PROBLEM
| Valuation (₹ crore) | x FY25 operating income (₹104 crore) | Profit needed at 40x P/E (₹ crore) | Revenue needed at 15% margin (₹ crore) |
|---|---|---|---|
| 5,000 | 48x | 125 | 833 |
| 10,000 | 96x | 250 | 1,667 |
| 20,000 | 192x | 500 | 3,333 |
| 30,000 | 288x | 750 | 5,000 |
Rupeia arithmetic; the 40x P/E and 15% net margin are assumptions used for scale, not forecasts.
| RUPEIA CALCULATION Rupeia calculation: at ₹20,000 crore, the company would need about 32 times its FY25 revenue to support a 40x multiple at a 15% margin. Defence companies can grow quickly on large orders, but a ₹300 crore pre-IPO cheque at this price is a statement about growth expectations, not an audited fact. |
|---|
12 5. COMPARISON FRAMEWORK AGAINST LISTED DEFENCE NAMES
| Test | What to check in the RHP | Why |
|---|---|---|
| Revenue scale | Revenue FY23–FY26 | Is the ₹104 crore figure a base for a multi-fold step-up? |
| Margins | EBITDA and PAT margin | Hardware start-ups often have thin margins |
| Order book ÷ revenue | Months of cover | Visibility |
| Intellectual property | Patents, indigenous content | Moat |
| Capex plan | Pune, Andhra Pradesh facilities | Capital needs and use of IPO funds |
| Customer concentration | Top customer share | Single-buyer risk |
13 6. GOVERNANCE AND DISCLOSURE GAPS
Entity name: pages refer to both "Private Limited" and "Limited"; conversion to a public company is presumably complete, but the sources do not reconcile it.
Lead managers: JM Financial is named as book-running lead manager; one page lists IIFL Capital, Kotak Mahindra Capital and UBS as well.
Headquarters: Mumbai contact address versus Pune expansion and Andhra Pradesh projects.
Investors in the pre-IPO round: described only as domestic institutions.
Founders: one founder is named; co-founders are referred to but not named.
14 7. QUESTIONS FOR THE RED HERRING PROSPECTUS
Revenue, EBITDA, PAT and cash flow for FY23–FY26 and the latest quarter.
Order book, customer list and largest customer share.
Fresh issue versus offer for sale, and use of proceeds.
Price band relative to the pre-IPO round price.
Promoter holding, selling shareholders and lock-in.
Licence terms and any export or technology-transfer restrictions.
Related-party transactions and contingent liabilities.
15 8. GLOSSARY
| Term | Meaning |
|---|---|
| UMSV / USV | Unmanned marine (or surface) vehicle |
| Retrofit | Adding autonomy equipment to an existing vessel |
| AIS | Automatic Identification System used by ships to broadcast position |
| Confidential pre-filing | SEBI route that lets a company file draft papers without public disclosure until later |
| Pre-IPO round | Private placement just before the public offer |
| BRLM | Book-running lead manager |
16 VALUATION SCENARIOS
| Scenario | Value (₹ crore) | x FY25 operating income | What must be true |
|---|---|---|---|
| Bear | 8,000 | 77x | RHP shows slower growth or thin margins; IPO re-priced |
| Base | 15,000 | 144x | Order book supports multi-year growth; IPO below the pre-IPO mark |
| Bull | 20,000+ | 192x+ | Large orders and margins justify the pre-IPO price |
Rupeia scenarios for illustration only; no earnings data are available to anchor them.
17 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 20% | RHP shows a strong order book; IPO at or above ₹20,000 crore |
| Base | 40% | IPO priced below the pre-IPO mark; listing follows after revision |
| Bear | 40% | Disclosure fails to support the valuation; IPO delayed or re-sized |
18 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Kill condition |
|---|---|---|
| Valuation far ahead of reported revenue | High | RHP revenue and margins |
| Order concentration and lumpy revenue | High | Largest customer share |
| Execution of shipyard and facility expansion | High | Pune and Andhra Pradesh timelines |
| Procurement delays and policy changes | Medium | Tender calendar |
| Technology and competition | Medium | New entrants and trials |
| Thin disclosure to date | High | Missing financials in sources |
| Licence conditions | Medium | Regulatory approvals |
19 INVESTOR CLASS ANALYSIS
HNIs and family offices
Do not anchor on the ₹20,000 crore pre-IPO mark. Wait for audited revenue, margins and order book in the RHP and compare the price band with listed defence peers on live quotes.
Institutions
Institutional buyers will focus on order-book visibility, customer concentration and whether the pre-IPO price is a ceiling or a floor.
NRIs
NRIs can hold unlisted Indian shares under FEMA pricing and reporting rules; repatriation depends on the account route used.
20 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Nov–Dec 2026 | Possible updated DRHP, RHP and price band |
| 2027 | First orders under the vessel licence |
| Ongoing | Naval and Coast Guard trial results |
21 RUPEIA FINAL INDEPENDENT VIEW
The business and the licence are real and relevant to India's unmanned-systems policy. The published numbers are too thin to support the headline valuation, so this is a watch-and-read-the-RHP situation.
| THE RUPEIA NUMBER ~190x. The ₹20,000 crore pre-money valuation divided by FY25 operating income of about ₹104 crore. |
|---|
| RUPEIA VERDICT Real theme, unproven numbers. Wait for the RHP. |
|---|
Frequently asked questions
What is Sagar Defence's valuation?
₹20,000 crore before the ₹300 crore pre-IPO round, per India Sentinels.
What is its revenue?
About ₹104 crore of operating income in FY25 per Venture Intelligence; no other figures were found.
Has SEBI cleared the IPO?
Observations were issued on 4 November 2026.
What does it make?
Unmanned marine surface vehicles, autonomous retrofit systems and, under a new licence, military surface and underwater vessels.
Who founded it?
Capt. Nikunj Parashar in 2015.
Source log
India Sentinels: Sagar Defence raises ₹300 crore pre-IPO at ₹20,000 crore
Raksha Anirveda: From 150 sq ft to ₹20,000 crore
The Week (PTI): Private firm wins licence to build military vessels
Chittorgarh: Sagar Defence Engineering IPO
Groww: Mahanadi Coalfields, Sagar Defence and Arjun Jewellers receive SEBI approval
Venture Intelligence: Sagar explores ₹3,000 crore IPO
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|