| ACQUIRER | Marico Ltd · MD and CEO Saugata Gupta; Group CFO Pawan Agrawal · three stated domains: digital foods, digital personal care, global digital brands |
|---|
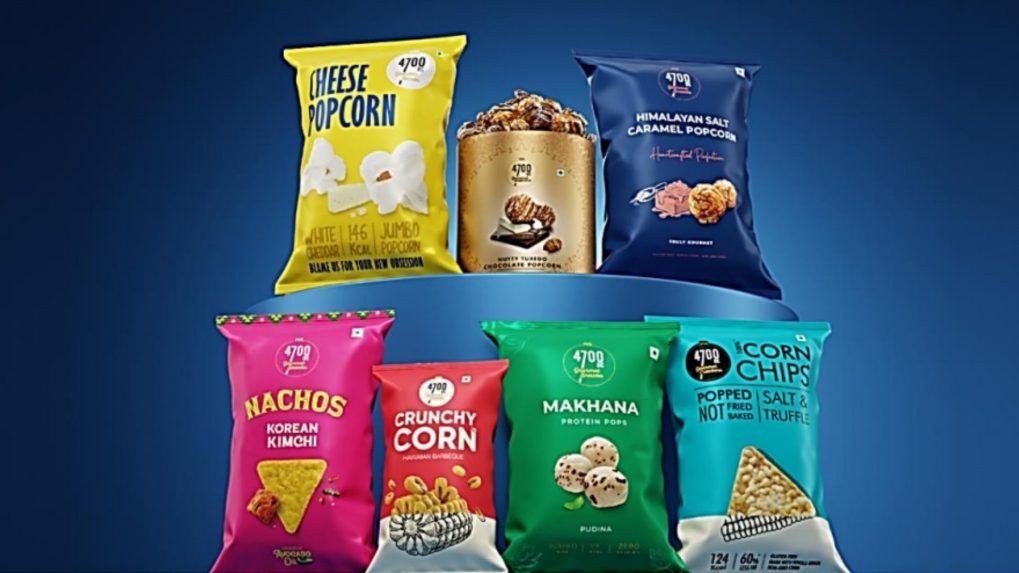
| 4700BC | 93.27% of Zea Maize Pvt Ltd (popcorn and snacking) for up to ₹226.83 Cr, all cash · seller PVR INOX · founder Chirag Gupta (the sources opened do not say whether a founder stake remains) |
| COSMIX | 60% of Cosmix Wellness (plant-based nutrition, founded 2019) for ₹225.67 Cr in cash · founders Vibha Harish and Soorya Jagadish keep 40% and run operations |
| IMPLIED VALUES | 4700BC about ₹243 Cr for 100% (Rupeia arithmetic) · Cosmix about ₹376 Cr by Rupeia arithmetic (one report puts it near ₹375 Cr) |
| REVENUE, FY25 | 4700BC ₹98.66 Cr · Cosmix ₹50.93 Cr · profit of 4700BC not disclosed · Cosmix profit ₹8.21 Cr (Entrackr) against about ₹17 Cr (Inc42, Green Queen) |
| DATES | 4700BC completion reported 29 Jan 2026 (search results, not opened) · Cosmix agreed about 4 Feb 2026, article dates 5 Feb · the brief's 12 Feb is not supported |
| REMAINING STAKES | 4700BC: option to buy the balance after three years at a value set then · Cosmix: sources conflict (after FY29 with milestones, or over three years) |
| LATER PLIX STEP | Additional 24.09% of Plix parent Satiya Nutraceuticals for ₹1,012.03 Cr, completed 5 Oct 2026, raising the holding to 84.09% |
| THE ACCESS POINT
Marico shares trade on NSE and BSE. The two brands are now inside Marico and cannot be traded separately. |
|---|
Executive decision summary
| THE BOTTOM LINE | Marico spent about ₹452 crore in early 2026 to take control of two small food brands. It signed for 93.27% of the popcorn maker 4700BC on 26 January for up to ₹226.83 crore, bought from PVR INOX, and agreed 60% of the plant-based nutrition brand Cosmix on about 4 to 5 February for ₹225.67 crore. The research brief said 12 February for Cosmix and a four-week close for 4700BC; the sources give an earlier Cosmix date and a reported 4700BC completion on 29 January. 4700BC grew revenue 31% to ₹98.66 crore in FY25, while Cosmix more than doubled to ₹50.93 crore. The prices imply about 2.5 times revenue for 4700BC and 7.4 times for Cosmix, and Cosmix profit is reported as ₹8.21 crore by one outlet and about ₹17 crore by two others. 4700BC profit is not published. |
|---|
| WHICH INVESTOR | The deals fit a Marico watch-list IF you want to see how a large consumer company buys fast-growing digital food brands in stages.
Wait IF you need 4700BC profit, the Cosmix profit reconciliation and the buy-out terms for the remaining stakes: none is published in the sources read. |
| COMFORT FIT | Implied valuation = the price paid divided by the stake bought, which gives a value for 100% of the company.
Secondary buyout = shares are bought from existing owners, so the money goes to sellers and not into the company.
D2C = a brand that sells directly to consumers, mostly online.
Milestone payment = extra money due later if the business meets agreed targets. |
| THE RUPEIA NUMBER | 7.4x. Cosmix's implied 100% value of about ₹376 Cr against FY25 revenue of ₹50.93 Cr, compared with about 2.5x for 4700BC. |
1 CLAIM REGISTER: EVIDENCE GRADING
| Claim | Source | Grade | Rupeia assessment |
|---|
| 4700BC: 93.27% of Zea Maize for up to ₹226.83 Cr, all cash | Storyboard18; Outlook Business (citing the NSE filing) | B | Established |
| 4700BC signed 26 Jan 2026; completed 29 Jan 2026 | Marketscreener; ScanX (search results) | D | Not opened. The brief's four weeks was the earlier expectation of about 30 days |
| Cosmix: 60% for ₹225.67 Cr in cash | Venture Intelligence (citing the exchange filing) | B | Established; press rounds it to ₹226 Cr |
| Cosmix agreed about 4–5 Feb 2026, not 12 Feb | Manifest Media (search); Venture Intelligence; Entrackr | C | The brief's date is not supported |
| Cosmix FY25 profit ₹8.21 Cr or about ₹17 Cr | Entrackr (filings); Inc42 and Green Queen (search) | C | Conflict, unresolved |
| Cosmix remaining 40%: after FY29 with milestones, or over three years | One outlet; Bar & Bench; Indian Startup News | D | Conflict; filing text not read |
| Plix: further 24.09% for ₹1,012.03 Cr, completed 5 Oct 2026 | CXO Digital Pulse | C | Single source |
2 THE TWO DEALS SIDE BY SIDE
| Item | 4700BC (Zea Maize Pvt Ltd) | Cosmix Wellness |
|---|
| Stake | 93.27% | 60% |
| Consideration | Up to ₹226.83 Cr, all cash | ₹225.67 Cr, cash |
| Seller | PVR INOX, majority holder since about 2015 | Founders per search summaries; sellers not confirmed in the text read |
| Signing and close | Signed 26 Jan 2026; completion 29 Jan 2026 as reported | Agreed about 4 Feb 2026; articles dated 5 Feb |
| Remaining stake | Option to buy the balance after three years at a valuation set then; one source adds milestones | Conflicting reports; not in the filing text read |
| Operator after the deal | Founder Chirag Gupta, minority holder | Founders Vibha Harish and Soorya Jagadish, holding 40% |
| Base | Founded 2013 (most sources) or 2012 (one source) | Founded 2019; Harohalli, Karnataka (Venture Intelligence) or Bengaluru base (search); not resolved |
| Calculation (Rupeia) | Result |
|---|
| Total consideration | ₹226.83 Cr + ₹225.67 Cr = ₹452.5 Cr |
| 4700BC implied 100% value | ₹226.83 Cr ÷ 0.9327 = ₹243.2 Cr |
| Cosmix implied 100% value | ₹225.67 Cr ÷ 0.60 = ₹376.1 Cr, against about ₹375 Cr reported |
| Combined implied 100% value | ₹243.2 Cr + ₹376.1 Cr = ₹619.3 Cr |
| Time from signing to reported completion, 4700BC | 29 Jan − 26 Jan = 3 days, against the expected 30 days |
| US$ equivalent of the total | ₹452.5 Cr ÷ 96.5 = US$4.69 Cr, or about US$46.9m |
| RUPEIA READ
Both deals are secondary purchases, so the ₹452 crore went to sellers and not into the two companies. Marico took control of each business while leaving the founders in charge, with the remaining shares left for a later step. The 4700BC price is stated as an upper limit, so the final figure can be lower; no source read gives a final number. |
|---|
3 4700BC: THE POPCORN BUSINESS
| Item | Detail | Source |
|---|
| Revenue FY23 | ₹48.47 Cr | Storyboard18 (filing) |
| Revenue FY24 | ₹75.29 Cr | Storyboard18 (filing) |
| Revenue FY25 | ₹98.66 Cr | Storyboard18 (filing) |
| Profit | Not published | Filing summary silent |
| Position | Number two in popcorn; ₹140 Cr annual run rate (ARR) | Marico investor call |
| Market claim | Western snacking market ₹24,000 Cr | Investor call; no independent size read |
| Calculation (Rupeia) | Result |
|---|
| Growth FY24 | ₹75.29 Cr ÷ ₹48.47 Cr = 1.553, so +55.3% |
| Growth FY25 | ₹98.66 Cr ÷ ₹75.29 Cr = 1.310, so +31.0% |
| Value to FY25 revenue | ₹243.2 Cr ÷ ₹98.66 Cr = 2.5x |
| Run rate against FY25 revenue | ₹140 Cr ÷ ₹98.66 Cr = 1.42x, so +41.9% |
| Value to run rate | ₹243.2 Cr ÷ ₹140 Cr = 1.74x |
| Balance of the company still outside Marico | 100% − 93.27% = 6.73%, worth about ₹16.4 Cr at the same value (6.73% × ₹243.2 Cr) |
| RUPEIA READ
4700BC is the cheaper of the two deals relative to sales and the more established, with three years of rising revenue and a number-two position. The weak point is disclosure: no profit is published and the run rate is a company statement. PVR INOX, whose MD Ajay Bijli called the sale a monetisation of a non-core asset, has exited. The growth rate slowed from 55% to 31%, and the run-rate claim implies renewed acceleration that the filings do not show. |
|---|
4 COSMIX: THE PLANT-BASED NUTRITION BUSINESS
| Item | Detail | Source |
|---|
| Revenue FY23 | ₹5.39 Cr | Consistent across sources |
| Revenue FY24 | ₹24.2–24.32 Cr | Consistent across sources |
| Revenue FY25 | ₹50.93 Cr; total income ₹51.18 Cr | Entrackr (filings) |
| Profit FY24 and FY25 | ₹2.83 Cr and ₹8.21 Cr | Entrackr (filings) |
| Profit FY25, other reports | About ₹17 Cr | Inc42; Green Queen (search, not opened) |
| EBITDA margin FY25 | 22.48% | Entrackr |
| Management view | An EBITDA drag today; target EBITDA positive in 12–18 months | Investor call via Investywise |
| Calculation (Rupeia) | Result |
|---|
| Growth FY24 | ₹24.2 Cr ÷ ₹5.39 Cr = 4.5x |
| Growth FY25 | ₹50.93 Cr ÷ ₹24.2 Cr = 2.10x, so +110% |
| Net margin FY25 at ₹8.21 Cr | ₹8.21 Cr ÷ ₹50.93 Cr = 16.1% |
| Net margin FY25 at ₹17 Cr | ₹17 Cr ÷ ₹50.93 Cr = 33.4%, which would exceed the 22.48% EBITDA margin and so looks inconsistent |
| Value to FY25 revenue | ₹376.1 Cr ÷ ₹50.93 Cr = 7.4x |
| Remaining 40% at the same value | ₹376.1 Cr − ₹225.67 Cr = ₹150.4 Cr (illustrative; the buy-out price is not published) |
| RUPEIA CALCULATION
A net profit of ₹17 crore on ₹50.93 crore of revenue would be a 33.4% net margin, higher than the 22.48% EBITDA margin reported by Entrackr. That cannot both be true on the same basis, so the ₹8.21 crore figure from the filings is the more consistent number. The CFO's description of Cosmix as an EBITDA drag points to a current-year position that differs from the FY25 margin; the sources do not reconcile the two. |
|---|
| RUPEIA READ
Cosmix is the more expensive deal at 7.4 times revenue, and its price assumes continued fast growth. Revenue rose more than four times in FY24 and then doubled in FY25, so the base is still small. The profit conflict and the gap between a 22% reported margin and an EBITDA drag are the main open points. |
|---|
5 STRATEGY AND THE WIDER DEAL TRAIL
| Item | Detail | Source |
|---|
| Investor call, 13 Feb 2026 | Three domains: digital foods, digital personal care, global digital brands | Investywise |
| Targets stated | New businesses 33% of Indian revenue by FY30; global digital brands at least ₹4,000 Cr top line by FY30; management avoids "FOMO-led premiums" | Investywise |
| Earlier deals | Beardo (45% in March 2017, price undisclosed, later full takeover about 2020); Just Herbs (60%, 2021, price not published); True Elements (majority, 2022, price not published) | Open Magazine; search results |
| Plix, 2023 | 58% for ₹369.01 Cr | July 2023 report |
| Plix, Oct 2026 | Additional 24.09% for ₹1,012.03 Cr, completed 5 Oct 2026; holding 84.09%; aggregate ₹1,392.07 Cr; remaining 14.09% due July 2027, base up to ₹592 Cr plus milestones | CXO Digital Pulse |
| Plix turnover | FY24 ₹155.32 Cr, FY25 ₹432.84 Cr, FY26 ₹864.31 Cr; the entity is not clearly labelled | CXO Digital Pulse |
| Beardo and Plix | About ₹1,000 Cr combined annual run rate; not sourced to a filing | Open Magazine |
| Calculation (Rupeia) | Result |
|---|
| Plix implied 100% value, 2023 | ₹369.01 Cr ÷ 0.58 = ₹636.2 Cr |
| Plix implied 100% value, Oct 2026 | ₹1,012.03 Cr ÷ 0.2409 = ₹4,201 Cr |
| Plix value, balance 14.09% | ₹592 Cr ÷ 0.1409 = ₹4,202 Cr, consistent with the 24.09% step |
| Plix value step-up | ₹4,201 Cr ÷ ₹636.2 Cr = 6.6x |
| Plix value to FY26 turnover | ₹4,201 Cr ÷ ₹864.31 Cr = 4.9x (entity unclear; indicative) |
| Stake arithmetic | 84.09% − 24.09% = 60%, so the holding before October was 60%, not the 58% of 2023 |
| Two stake sums reported | ₹369.01 Cr + ₹1,012.03 Cr = ₹1,381.04 Cr, against the reported aggregate ₹1,392.07 Cr: a gap of ₹11.03 Cr that no source explains |
| Plix October step against the two early-2026 deals | ₹1,012.03 Cr ÷ ₹452.5 Cr = 2.2x |
| RUPEIA READ
The two early-2026 deals are small next to Plix, where a single follow-on purchase cost 2.2 times both of them together. The pattern is control first, with the rest bought later at a value set by performance. That keeps founders motivated, but the buy-out cost depends on future results and is not yet known for 4700BC or Cosmix. The Plix numbers have three loose ends: the unexplained ₹11.03 crore gap, the 58% against 60% stake and the unclear turnover entity. |
|---|
6 RISKS, SCENARIOS AND CHECKLIST
| Risk | Evidence | Severity | Kill condition |
|---|
| Price paid | Cosmix at 7.4x FY25 revenue | HIGH | Growth falls below the pace the price assumes |
| Profit disclosure | 4700BC profit not published; Cosmix profit ₹8.21 Cr or about ₹17 Cr | HIGH | Filings show losses after integration |
| Buy-out cost | Terms for remaining stakes conflict or are not published | MEDIUM | Milestone payments exceed the current price |
| Founder dependence | Founders run both businesses and keep minority stakes | MEDIUM | A founder exits early |
| Cosmix margin | Management calls it an EBITDA drag | MEDIUM | EBITDA stays negative past 18 months |
| Run-rate claim | 4700BC ARR ₹140 Cr is a company statement | LOW | FY26 filing shows lower sales |
| Scenario | What happens | Outcome |
|---|
| Bull | Both brands keep growing above 30% and Cosmix turns EBITDA positive in 12–18 months | Remaining stakes bought at higher values from larger earnings |
| Base | Growth slows to 20–30% and margins improve slowly | Prices paid look fair, not cheap |
| Bear | Cosmix growth stalls and 4700BC loses share in popcorn | The 7.4x entry price looks high |
| Investor class | Fit | Why |
|---|
| Listed-market investor in Marico | PARTIAL | The deals are small in rupees, but the filings omit profit for one of them |
| Short-term trader | WATCH | Cosmix and 4700BC filings, and the next quarterly results |
| D2C and food researcher | FIT | Clear example of staged control deals at different multiples |
Rupeia does not recommend buying or selling any security and is not a SEBI-registered investment adviser or research analyst. Open items are 4700BC profit, the Cosmix profit reconciliation, the buy-out terms for both remaining stakes and the exchange-filing text, which did not parse.
7 KEY TERMS USED IN THIS REPORT
The terms below are used in this report. Each is explained in plain words.
| Term | Meaning |
|---|
| Implied valuation | The price paid divided by the stake bought, giving a value for 100%. |
| Secondary buyout | Shares bought from existing owners, so the cash goes to sellers. |
| D2C | Direct-to-consumer: a brand that sells straight to buyers, mostly online. |
| ARR | Annual run rate: recent sales scaled to a full year. |
| EBITDA | Operating profit before interest, tax, depreciation and amortisation. |
| Milestone payment | Extra money due later if agreed targets are met. |
Frequently asked questions
What did Marico pay for 4700BC?
Up to ₹226.83 crore in cash for 93.27% of Zea Maize Pvt Ltd, which implies about ₹243 crore for 100%. PVR INOX was the seller.
What did Marico pay for Cosmix?
₹225.67 crore in cash for 60% of Cosmix Wellness, an implied value of about ₹376 crore for 100%. The founders keep 40%.
When were the deals agreed?
4700BC was signed on 26 January 2026 and reported completed on 29 January. Cosmix was agreed about 4 to 5 February 2026, not 12 February.
How big are the two businesses?
FY25 revenue was ₹98.66 crore for 4700BC and ₹50.93 crore for Cosmix. 4700BC profit is not published; Cosmix profit is ₹8.21 crore in the filings summary, with other outlets citing about ₹17 crore.
Will Marico buy the rest?
For 4700BC there is an option to buy the balance after three years at a value set then. For Cosmix the sources conflict between after FY29 with milestones and over three years.
How do these compare with Plix?
Marico raised its Plix holding to 84.09% on 5 October 2026 with a ₹1,012.03 crore purchase of 24.09%, which implies about ₹4,200 crore for 100% against ₹636 crore in 2023.
Source log
Venture Intelligence: Marico acquires 60% stake in Cosmix
Outlook Business: PVR INOX exits 4700BC, sells stake to Marico for ₹226.8 crore
Storyboard18: Marico to acquire 93.27% in Zea Maize
Investywise: Marico strategic investments call, 13 Feb 2026
Open Magazine: Inside Marico's deal trail, from Beardo to Cosmix
Entrackr: Cosmix by the numbers, what Marico gets
CXO Digital Pulse: Marico acquires additional 24.09% in Plix parent
| DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|