| TRUST | Road infrastructure investment trust (InvIT) sponsored by I Squared Capital · privately placed and listed on BSE in April 2023 · manager Cube Highways Fund Advisors · trustee Axis Trustee Services |
|---|
| JULY 2026 OFFER | Up to ₹5,000 Cr, all offer for sale (OFS), so the trust received no proceeds · issue price ₹152 (band ₹151–152) · valuation ₹20,430 Cr at the top of the band |
| DEMAND | Anchor book ₹1,687.5 Cr from 59 anchors · overall subscription "more than nine times", QIB "more than thirteen times" (sponsor); one source gives 2.55x |
| STRATEGIC INVESTORS | ₹1,250 Cr at ₹152 (8.22 crore units), led by Prazim (Azim Premji-backed) with ₹950 Cr · locked in to about 27 January 2027 |
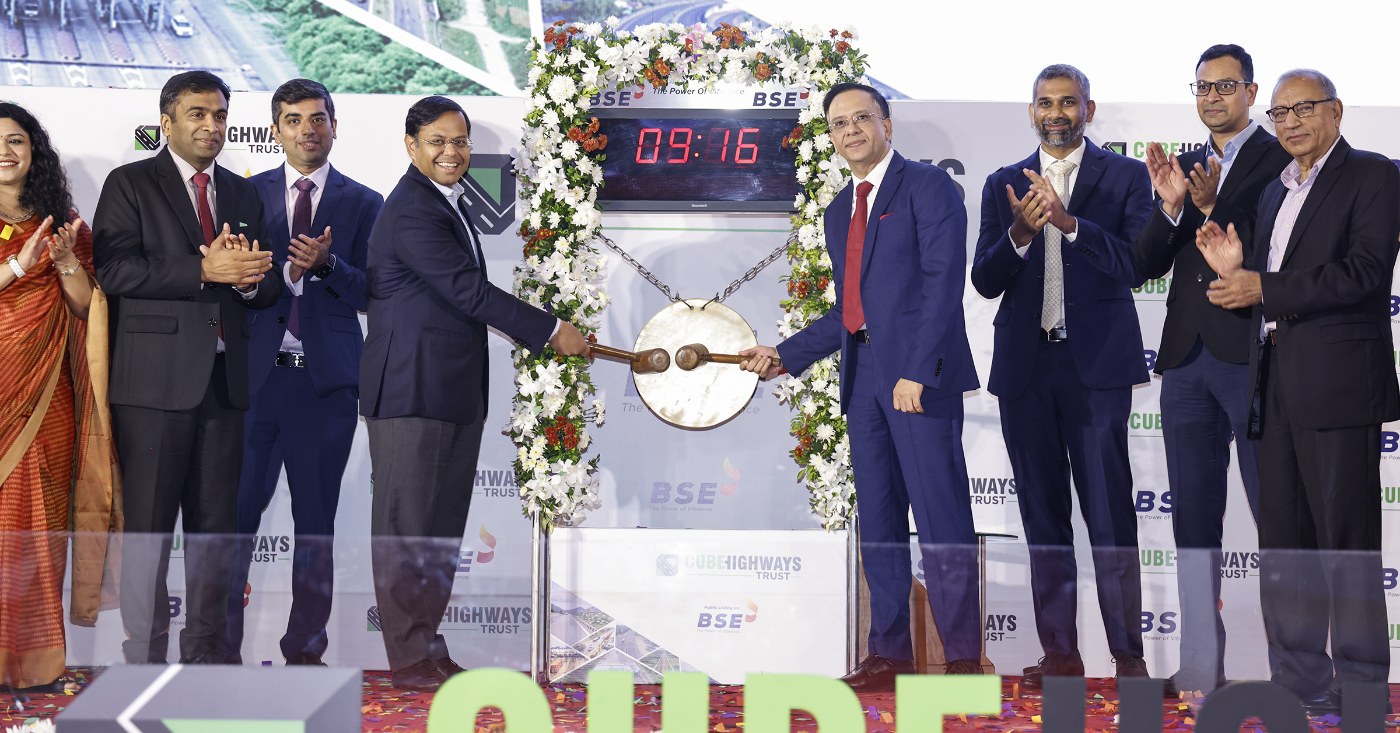
| LISTING AND PRICE | Listed 31 July 2026 at about ₹155 · ₹152 on 9 November 2026 · market cap ₹20,423 Cr (Screener) |
| PORTFOLIO | 27 road assets at 31 Mar 2026 (26 operating after the Western UP Tollway concession ended in June 2026, per Outlook Business), 12 states and 1 union territory · 85% toll, 15% annuity · concession life over 18 years · AUM ₹36,842 Cr · 8,754 lane km (sponsor) or 2,005 km (Outlook Business) |
| DISTRIBUTIONS | FY26 distribution per unit (DPU) ₹13.77, total ₹1,851 Cr · H1 FY27 ₹7.74 · FY27 guidance ₹15.50, up from ₹14.50 |
| LEVERAGE AND RATING | Net debt ₹17,768 Cr · net debt to EV 46.82% · cost of debt 7.49–7.53% · AAA/Stable from CRISIL, ICRA and India Ratings |
| THE ACCESS POINT
Cube Highways Trust units are listed on NSE and BSE and can be bought in the market. Leadership names are not published in the sources read. |
|---|
Executive decision summary
| THE BOTTOM LINE | Cube Highways Trust is a listed road InvIT that existed before its July 2026 public offer. The ₹5,000 crore issue at ₹152 a unit was entirely an offer for sale by existing unit holders, so the trust raised nothing. Demand was strong on the sponsor's account (more than nine times overall) and units listed on 31 July about 2% above issue; they now trade at ₹152, level with the issue price. The trust paid ₹13.77 a unit in FY26, about 9% of the offer price, and guides to ₹15.50 for FY27. Against that, net debt is ₹17,768 crore, about 47% of enterprise value, and sources disagree sharply on FY26 revenue (₹4,239 crore or ₹2,911 crore), NAV and road length. The ₹1,250 crore of strategic units leave lock-in around 27 January 2027, and a further US$400 million sale is reported to be under exploration. |
|---|
| WHICH INVESTOR | Cube fits an income-focused listed-market investor IF you want a large AAA-rated road portfolio paying quarterly and accept leverage near 47%.
Wait IF you need one consistent set of audited FY26 figures: the sources conflict and the annual report was not opened. |
| COMFORT FIT | InvIT = a trust that owns operating infrastructure and pays out most of its cash to unit holders.
Offer for sale (OFS) = existing holders sell units; the trust receives no money.
Toll vs annuity = toll roads earn from traffic; annuity roads receive fixed government payments.
DPU = distribution per unit, the cash paid for each unit held. |
| THE RUPEIA NUMBER | 9.1%. FY26 distribution of ₹13.77 a unit as a share of the ₹152 offer price; the sponsor says about 9%. |
1 CLAIM REGISTER: EVIDENCE GRADING
| Claim | Source | Grade | Rupeia assessment |
|---|
| Up to ₹5,000 Cr OFS at ₹152; no proceeds to the trust | Outlook Business; Multibagg | B | Established. Not a first listing: the trust listed on BSE in April 2023 |
| Anchors ₹1,687.5 Cr; strategic ₹1,250 Cr | Outlook Business | B | Single detailed source |
| Subscription more than nine times | I Squared; Ventura 9.35x | C | One source gives 2.55x (page not opened) |
| Listed 31 July 2026 at about ₹155 | I Squared; Multibagg | C | Earlier sources said 3 August; exchange data not found |
| FY26 revenue ₹4,239 Cr, PAT ₹1,422.9 Cr | Whalesbook; Outlook | D | Screener shows revenue ₹2,911 Cr |
| FY26 DPU ₹13.77; FY27 guidance ₹15.50 | Multibagg; Screener | C | Quarterly figures sum to ₹15.21 |
| US$400m sale explored by ADIA and I Squared | Zawya | D | Single report |
2 THE JULY 2026 OFFER AND THE LISTING
| Item | Detail |
|---|
| Structure | Up to ₹5,000 Cr, all OFS; the trust became publicly listed; no proceeds to the trust |
| Dates | Anchor allotment 21 July; issue 22–24 July; listing 31 July 2026 (sponsor announcement, 12 August) |
| Subscription | Overall more than nine times, QIB more than thirteen times (sponsor); 9.35x and 13.20x (Ventura); 2.55x (Brokerchooser) |
| Listing prices | About ₹155 (Multibagg); one source gives BSE close ₹156.88, NSE close ₹156.96, high ₹158.40 |
| Latest | ₹152, down 0.53%, 11:15 am on 9 November 2026 (Screener) |
| Calculation (Rupeia) | Result |
|---|
| Offer as a share of the valuation | ₹5,000 Cr ÷ ₹20,430 Cr = 24.5% |
| Units implied by the valuation | ₹20,430 Cr ÷ ₹152 = 134.4 crore units |
| Anchor share of the offer | ₹1,687.5 Cr ÷ ₹5,000 Cr = 33.8% |
| Listing against issue price | ₹3 ÷ ₹152 = 2.0% gain at ₹155; NSE close ₹4.96 ÷ ₹152 = 3.3% |
| RUPEIA READ
Institutional demand was solid on the sponsor's account and units opened modestly above issue. That gain has gone: at ₹152 the units are level with the issue price. The sponsor announcement and Ventura agree on nine times, so that figure is better supported than 2.55x. |
|---|
3 WHO SOLD, WHO BOUGHT AND THE LOCK-IN
| Item | Detail | Source |
|---|
| Sellers (announcement) | I Squared Capital, ADIA, BCI and Mubadala | I Squared, 12 Aug 2026 |
| Sellers (offer documents) | BCI IRR India Holdings, Seventy Second Investment Company, Cube Highways and Infrastructure (II/III), Cube Mobility Investments | Outlook Business; Asksfuzz |
| Strategic investors | Prazim ₹950 Cr; HDFC Life and HDFC Pension ₹100 Cr each; Axis Max Life ₹50 Cr; WhiteOak ₹50 Cr; locked in 180 days from listing | Outlook Business |
| Possible further sale | ADIA and I Squared reportedly hired bankers to sell up to US$400m | Zawya, single report |
| Calculation (Rupeia) | Result |
|---|
| Strategic tickets added up | ₹950 Cr + ₹200 Cr = ₹1,150 Cr, and ₹1,150 Cr + ₹100 Cr = ₹1,250 Cr, matching the reported total |
| Strategic units | ₹1,250 Cr ÷ ₹152 = 8.22 crore units, matching the report; as a share of all units, 8.22 ÷ 134.4 = 6.1% |
| US$400m in rupees | US$400m × ₹96.5 = ₹38,600 m, and ₹38,600 m ÷ 10 = ₹3,860 Cr |
| RUPEIA READ
The sellers are the sponsor and its co-investors, so the offer was an exit and a wider register, not a funding round. The two seller lists differ because one names shareholders and the other the legal entities that held the units. The lock-in ends about 79 days after the date of this note,. |
|---|
4 THE ASSETS AND THE FINANCIALS
| Measure | Source A | Source B |
|---|
| FY26 revenue | ₹4,239 Cr, +28% (Whalesbook) | ₹2,911 Cr (Screener) |
| FY26 EBITDA | ₹3,092 Cr (Whalesbook); ₹3,234.5 Cr (ScanX) | ₹2,774 Cr (Screener) |
| FY26 PAT | ₹1,422.9 Cr; ₹216.7 Cr also cited in the same article (Outlook source) | ₹1,423 Cr (Screener) |
| Q1 FY27 revenue | ₹11,266 Cr against ₹9,443 Cr; its unit labels imply ₹1,126.6 Cr (Multibagg) | Not found elsewhere |
| Q2 FY27 | Sales ₹852 Cr, EBITDA ₹624 Cr, PAT ₹287 Cr (Screener) | Toll revenue ₹862.25 Cr against ₹758.77 Cr (Arthneeti) |
| Lane km | 8,754 for 27 assets (sponsor) | 2,005 for the same 27 assets (Outlook) |
| Calculation (Rupeia) | Result |
|---|
| EBITDA margin, Whalesbook | ₹3,092 Cr ÷ ₹4,239 Cr = 72.9%; ScanX figure ₹3,234.5 Cr ÷ ₹4,239 Cr = 76.3% |
| EBITDA margin, Screener | ₹2,774 Cr ÷ ₹2,911 Cr = 95.3%, too high for a toll business, so the lines may be on different bases |
| Gap between revenue figures | ₹4,239 Cr ÷ ₹2,911 Cr = 1.46x |
| Q1 FY27 as printed | ₹11,266 Cr ÷ ₹4,239 Cr = 2.7x the whole of FY26, which is not credible; either unit reading gives ₹11,266 ÷ ₹9,443 = 1.19x, about 19% growth |
| Q2 FY27 margins and growth | ₹624 Cr ÷ ₹852 Cr = 73.2%; toll revenue ₹103.48 Cr ÷ ₹758.77 Cr = 13.6% (₹862.25 − ₹758.77 = ₹103.48) |
| RUPEIA READ
The revenue, EBITDA, profit and length figures cannot all be right, and the audited annual report is the missing reference. The sources may be using consolidated and trust-level bases, but none says so. What stays consistent is the shape: an EBITDA margin near three-quarters, mostly toll income (85%), and Q2 toll revenue up about 14%. |
|---|
5 DISTRIBUTIONS, NAV AND VALUATION
| Item | Detail | Source |
|---|
| FY26 DPU | ₹13.77, total ₹1,851 Cr; quarters ₹3.94, ₹3.60, ₹4.10, ₹3.57 | Multibagg |
| FY27 so far | Q1 ₹3.95; Q2 ₹3.79 (record date 31 October, paid by 6 November); H1 ₹7.74 | Multibagg; Screener |
| Guidance | FY27 DPU raised to ₹15.50 from ₹14.50 | Multibagg |
| NAV | ₹145.77 at 31 March 2026; Screener book value ₹94.1 | Conflict |
| Yield | About 9% on the offer price (sponsor); 5.10% at the current price (Screener) | Conflict |
| NDCF | Full-year net distributable cash flow: not published in the sources read | Not found |
| Calculation (Rupeia) | Result |
|---|
| Quarters added up | ₹3.94 + ₹3.60 = ₹7.54; ₹7.54 + ₹4.10 = ₹11.64; ₹11.64 + ₹3.57 = ₹15.21 |
| Gap to stated FY26 DPU | ₹15.21 − ₹13.77 = ₹1.44, unexplained in the sources |
| Units implied by the total | ₹1,851 Cr ÷ ₹13.77 = 134.4 crore units, matching the valuation |
| H1 FY27 and guidance | ₹3.95 + ₹3.79 = ₹7.74; ₹7.74 ÷ ₹15.50 = 49.9% of guidance; raise ₹1.00 ÷ ₹14.50 = 6.9% |
| Yield on ₹152 | FY26 ₹13.77 ÷ ₹152 = 9.1%; guidance ₹15.50 ÷ ₹152 = 10.2%; H1 ₹7.74 ÷ ₹152 = 5.1%, so Screener's 5.10% is a half-year figure |
| Price to NAV | ₹152 ÷ ₹145.77 = 1.04x; against book value, ₹152 ÷ ₹94.1 = 1.62x |
| RUPEIA READ
The 5.10% and the 9% are not a contradiction: they measure half a year and a full year. The quarterly figures, however, add to ₹15.21 against a stated ₹13.77, a gap the sources do not explain. At ₹152 the units pay about 9% on last year's distribution and trade only 4% above March NAV. NAV is a valuation of the roads and book value an accounting number, so the two are not interchangeable. |
|---|
6 LEVERAGE, RATING AND THE ACQUISITION
| Item | Detail | Source |
|---|
| Net debt | ₹17,768 Cr; to EV 46.82% (FY26); to AUM 45.17% (Q1 FY27); debt to EBITDA 4.21x | Multibagg |
| Borrowings | ₹17,543 Cr (March 2026); ₹17,928 Cr (September 2026); cost of debt 7.49–7.53% | Screener; Multibagg |
| Rating | AAA/Stable, CRISIL, ICRA and India Ratings, reaffirmed 30 April 2026; ICRA comfort level "below 55%" | Trendlyne; Whalesbook |
| Acquisition | Assets from the sponsor group for ₹7,292.5 Cr, said to add more than ₹3 a unit to NAV | Whalesbook, May 2026 |
| Calculation (Rupeia) | Result |
|---|
| Net debt against AUM | ₹17,768 Cr ÷ ₹36,842 Cr = 48.2%, above both published ratios, which come from different dates |
| EBITDA implied by 4.21x | ₹17,768 Cr ÷ 4.21 = ₹4,220 Cr, above every FY26 EBITDA figure, so the ratio seems to use a pro forma base |
| Headroom to 55% | 55 − 46.82 = 8.18 percentage points |
| Interest at 7.5% | ₹17,928 Cr × 0.075 = ₹1,344.6 Cr, and ₹1,344.6 Cr ÷ ₹3,092 Cr = 43.5% of FY26 EBITDA |
| Acquisition size | ₹7,292.5 Cr ÷ ₹36,842 Cr = 19.8% of AUM; claimed gain ₹3 × 134.4 = ₹403 Cr |
| RUPEIA READ
AAA from three agencies and borrowing near 7.5% are real strengths. The weak point is that leverage quoted sits at 45% to 48% after an acquisition worth a fifth of AUM, and the 4.21x debt to EBITDA does not match reported EBITDA; its definition is not published in the sources read. Older cover ratios (CRISIL about 1.75x, ICRA about 2.5x) are not current. |
|---|
7 PEERS: IRB INVIT AND RAAJMARG
| Item | IRB InvIT Fund (Screener, 9 Nov 2026) | Raajmarg Infra InvIT (snippets) |
|---|
| Price | Unit ₹61.3; market cap ₹10,128 Cr | Listed March 2026 at ₹107 on a ₹99–100 band |
| NAV | ₹75.46 (30 Sep 2026) | ₹100.72 (FY26); ₹109.79 (Q1 FY27) |
| Distributions | FY26 DPU ₹6.60; Q2 FY27 ₹1.625 | Q1 FY27 ₹2.40; Q2 FY27 ₹2.43, with an implausible ₹1,458 Cr total |
| Calculation (Rupeia) | Result |
|---|
| IRB discount to NAV | ₹75.46 − ₹61.3 = ₹14.16, and ₹14.16 ÷ ₹75.46 = 18.8% |
| IRB yield | ₹6.60 ÷ ₹61.3 = 10.8%, against Cube 9.1% at ₹152 |
| Cube against IRB market cap | ₹20,423 Cr ÷ ₹10,128 Cr = 2.0x (an earlier note said about 4x; the arithmetic gives 2.0x) |
| Raajmarg total check | 60 crore units × ₹2.43 = ₹145.8 Cr, so ₹1,458 Cr is a slip by a factor of ten |
| RUPEIA READ
IRB trades about 19% below NAV and yields about 10.8%, while Cube trades at NAV and yields about 9%: the market pays a premium for Cube's scale and rating. Cube is about twice IRB's market value. The Raajmarg figures come from search snippets and carry at least one visible error. |
|---|
8 RISKS, SCENARIOS AND CHECKLIST
| Risk | Evidence | Severity | Kill condition |
|---|
| Data conflicts | Revenue ₹4,239 Cr or ₹2,911 Cr; NAV ₹145.77 or ₹94.1; 8,754 or 2,005 lane km | HIGH | Audited accounts differ from the figures used |
| Leverage | Net debt ₹17,768 Cr; 45–47% of EV | MEDIUM | Ratio nears the 55% comfort level |
| Selldown overhang | US$400m sale reported; lock-in ends about 27 Jan 2027 | MEDIUM | Large blocks sold below ₹152 |
| Costs and growth | Management flags high bitumen prices for three years, GDP slowing to 6.5%, West Asia tensions | MEDIUM | Traffic or costs turn against plan |
| Scenario | What happens | Outcome |
|---|
| Bull | DPU reaches ₹15.50 and units rerate above NAV | Yield above 10% on ₹152 |
| Base | Distributions near guidance; units hold near ₹152 | Income of about 9–10% a year |
| Bear | Block sales at a discount; costs rise; DPU misses guidance | Units fall below issue price |
| Investor class | Fit | Why |
|---|
| Income-seeking investor | PARTIAL | High yield and AAA rating, but leverage and conflicting disclosures |
| Short-term trader | WATCH | Lock-in date near 27 January 2027 and block deals |
| Infrastructure researcher | FIT | Large listed road platform with a close peer in IRB InvIT |
Rupeia does not recommend buying or selling any security and is not a SEBI-registered investment adviser or research analyst. Open items are the audited annual report, a consistent NAV, exchange listing data, full-year NDCF and the names of the manager's leadership, none of which is published in the sources read.
9 KEY TERMS USED IN THIS REPORT
The terms below are used in this report. Each is explained in plain words.
| Term | Meaning |
|---|
| InvIT | Infrastructure investment trust: owns operating assets and pays most cash to unit holders. |
| OFS | Offer for sale: existing holders sell and the trust receives no money. |
| DPU | Distribution per unit: cash paid for each unit held. |
| NAV | Net asset value per unit: assessed asset value less debt, divided by units. |
| Lane km | Road length counted for each lane of traffic. |
| Lock-in | A period in which certain investors cannot sell their units. |
Frequently asked questions
Did Cube Highways Trust raise money in July 2026?
No. The ₹5,000 crore offer was entirely an offer for sale by existing unit holders, so the trust received no proceeds.
What was the issue price and when did units list?
₹152 a unit, with the issue open 22–24 July 2026. Units listed on 31 July 2026 at about ₹155.
What is the distribution?
FY26 DPU was ₹13.77, about 9% of the ₹152 offer price. H1 FY27 was ₹7.74 and FY27 guidance was raised to ₹15.50 from ₹14.50.
How much debt does the trust have?
Net debt is ₹17,768 crore, 46.82% of enterprise value at FY26. CRISIL, ICRA and India Ratings rate it AAA/Stable.
Why do sources disagree on its financials?
FY26 revenue is ₹4,239 crore in one source and ₹2,911 crore on Screener, and lane km is 8,754 or 2,005. The audited annual report was not opened, so both are shown.
When does the strategic lock-in end?
About 27 January 2027, 180 days after listing, for the ₹1,250 crore of strategic units led by Prazim with ₹950 crore.
Source log
Multibagg: Cube Highways Trust InvIT lists 2% higher post IPO
Outlook Business: Cube Highways InvIT fixes ₹151-152 price band for ₹5,000 cr IPO
Whalesbook: Cube Highways Trust FY26 Revenue Up 28% to ₹4,239 Crore
Screener: Cube Highways Trust (CUBEINVIT)
Screener: IRB InvIT Fund (IRBINVIT)
Multibagg: Cube Highways Trust Q1 results, FY27 revenue up 19%
I Squared Capital: Cube Highways listing announcement
Multibagg: Cube Highways Q1 FY27 earnings call
| DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|