Pocket FM: seeking up to US$120m at about US$2bn
Independent report content
| REPORTED RAISE | Up to US$100–120m (Mint, April 2026), aiming for a valuation near US$2bn; previous valuation about US$750m |
|---|---|
| ARR | Reports of US$400–450m, up from about US$200m a year earlier (unaudited, from press) |
| PROFITABILITY | NewsBytes: cash-flow profitable with EBITDA margins near 5%; Caplight: profitable as of June 2026; another investor-report site shows a loss (unverified) |
| REVENUE (DATABASE) | Tracxn: ₹500–1,000 crore at 31 March 2025 |
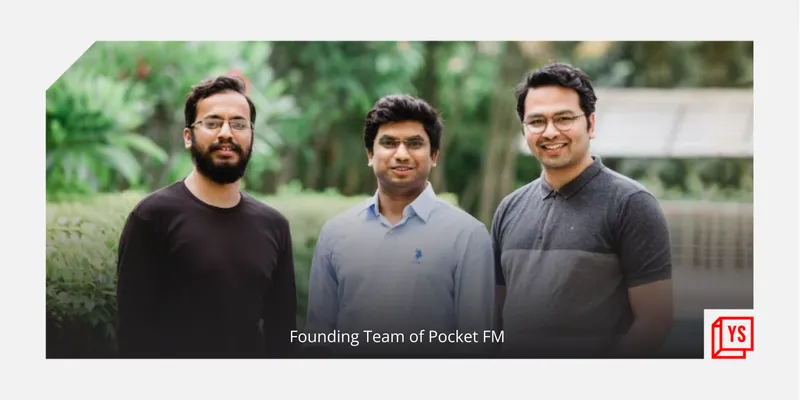
| FOUNDERS | Rohan Nayak, Prateek Dixit and Nishanth KS |
| IPO | No confirmed IPO plan found |
| EARLIER ATTEMPT | A funding push the year before was reported as unsuccessful |
| THE ACCESS POINT Pocket FM is private. Investors include Lightspeed, Stepstone, Tiger Global and others. Individuals can reach it only via funds. |
|---|
Executive decision summary
| THE BOTTOM LINE Pocket FM sells serial audio fiction and, increasingly, video and text series, to listeners who pay per episode or by subscription. A sharp growth path (annual recurring revenue reported to have more than doubled in a year to US$400–450m) and a reported move to cash-flow profit have put a roughly US$2bn valuation in play, up from about US$750m. The numbers are from press and company statements and have not been audited, and the previous funding attempt did not close. |
|---|
| WHICH INVESTOR Fits you IF you want a high-growth consumer-subscription business in audio and micro-entertainment, led by its founders. Look elsewhere IF you want audited financials or low execution risk: the model depends on paid acquisition and content costs. |
|---|
| COMFORT FIT Pocket FM = a streaming service for stories you listen to, paid for by the episode. Kuku FM, Audible, Storytel = audio-story rivals. EloElo (Story TV), ReelShort = video-microdrama peers. |
|---|
| THE RUPEIA NUMBER 2.7x. The step-up from a US$750m valuation to nearly US$2bn that the company is reported to seek. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
A = government or regulator record. B = statutory filing. C = independent press. D = company announcement.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Seeking US$100–120m at close to US$2bn | Mint via Inshorts; NewsBytes; TechStory | C | Reported talks; not announced as closed. |
| Previous valuation about US$750m | Press | C | Reported. |
| ARR US$400–450m | Press (April 2026) | D/C | Unaudited; sources differ. |
| Cash-flow profitable; EBITDA near 5% | NewsBytes | C | Reported. |
| Revenue ₹500–1,000 crore at 31 Mar 2025 | Tracxn | C | Range only. |
2 COMPANY OVERVIEW & FOUNDING STORY
Pocket FM was founded in 2018 in Bengaluru by Rohan Nayak, Prateek Dixit and Nishanth KS. It began as an audio-series app in Hindi and built a library of thousands of titles by working with writers and voice artists, then used data to decide which stories to extend. It expanded to the United States with a similar model and added video and AI-assisted production.
The business model is "freemium": listeners get the first few episodes free and then pay with coins or a subscription to hear more. Hits drive large revenue because a successful story can run for hundreds of episodes. Pocket FM says it uses listening data to decide which stories to commission and extend.
The weakness of the model is dependence on paid marketing to find new listeners and on a steady pipeline of hits. If advertising costs rise or story fatigue sets in, margins fall quickly.
3 TIMELINE
| Date | Event |
|---|---|
| 2018 | Founded in Bengaluru |
| 2021–22 | Series B and C; international expansion |
| 2024 | Series D led by Lightspeed at about US$750m |
| 2025 | ARR reported near US$200m; funding attempt reported unsuccessful |
| Apr 2026 | ARR reported at US$400–450m; talks to raise US$100–120m near US$2bn |
4 FUNDING HISTORY AND THE NEW ROUND
| Date | Round | Amount | Comment |
|---|---|---|---|
| 2024 | Series D | ~US$103m | Led by Lightspeed; about US$750m valuation (company announcement as reported) |
| 2025 | Attempted raise | Not completed | Reported as unsuccessful |
| Apr 2026 | Talks | US$100–120m | Target valuation near US$2bn |
The second attempt at a larger valuation comes after a year of reported growth, which is the standard route to a re-rating. If the round closes, it will be among the largest for an Indian consumer-subscription company in 2026.
| RUPEIA CALCULATION US$120m at US$2bn is a 6% stake; at US$100m it is 5%. A valuation of US$2bn on ARR of US$400–450m is 4.4–5.0x ARR, lower than the 10x or more some AI-subscription companies command, and about 2.7x the prior mark. |
|---|
5 FINANCIAL PICTURE
| Metric | Figure | Source quality |
|---|---|---|
| ARR (April 2026) | US$400–450m | Press; unaudited |
| ARR a year earlier | ~US$200m | Press |
| Revenue at 31 Mar 2025 | ₹500–1,000 crore | Tracxn range |
| EBITDA margin | ~5% (cash-flow profit) | NewsBytes |
| Valuation ÷ ARR at US$2bn | 4.4–5.0x | Rupeia calculation |
ARR is a run-rate figure. For a pay-per-episode business it can be inflated by a hit story or a promotional month, so audited revenue will matter more once available.
| RUPEIA CALCULATION ARR of US$400–450m is about ₹3,860–4,340 crore at ₹96.5. The Tracxn revenue range for FY25 (₹500–1,000 crore) would imply growth of 4–8x in about a year, which is unusually steep and shows the two figures are measured differently (ARR vs recognised revenue). |
|---|
6 BUSINESS MODEL & UNIT ECONOMICS
Pocket FM earns from listeners who pay for episodes or subscribe, and increasingly from advertising and partnerships.
| Line | How it earns | Pressure point |
|---|---|---|
| Coins and pay-per-episode | Listeners buy coins to unlock episodes | Hit dependence; marketing cost |
| Subscriptions | Monthly or yearly plans | Churn |
| International (US) | Same model in English-language series | High acquisition cost |
| Video and AI-assisted production | New formats with lower cost per episode | Quality and rights risks |
Cost of content is front-loaded (writing, voice work, production) while revenue arrives over the run of the story. A story that runs long earns a high return; one that flops costs the full production budget.
7 MARKET & COMPETITIVE ANALYSIS
| Peer | Status | Position |
|---|---|---|
| Kuku FM | Private | Largest Indian audio-series rival |
| Audible (Amazon), Storytel | Global listed parents | Audiobook and audio-series leaders |
| StoryTV (EloElo), ReelShort | Private | Video microdrama rivals competing for the same spend |
| Spotify, YouTube | Listed | Platforms offering free alternatives |
No listed peer matches the model, so valuation talk draws on subscription and streaming comparables, which are volatile.
8 HIT-DRIVEN ECONOMICS: A WORKED EXAMPLE
| Story outcome | Illustrative production cost | Illustrative lifetime revenue | Result |
|---|---|---|---|
| Flop (stops at episode 20) | ₹20 lakh | ₹10 lakh | Loss of ₹10 lakh |
| Average (episode 100) | ₹60 lakh | ₹90 lakh | Profit ₹30 lakh |
| Hit (episode 400) | ₹1.2 crore | ₹6 crore | Profit ₹4.8 crore |
Rupeia illustration to show the shape of the economics, not Pocket FM data.
This is why the company's data approach to picking and extending stories matters: if it can cut flops early and fund hits, margin improves quickly.
9 WHAT TO READ IN THE ARR CLAIM
Does ARR count only subscriptions or also coin purchases, which are one-off?
Is it gross of app-store fees (typically 15–30%)?
What share is India and what share is the United States, where acquisition costs are higher?
How much of ARR comes from the top ten titles?
Without these answers an ARR of US$400–450m can mean very different businesses.
10 COMPETITION AND CONTENT RISK
Kuku FM competes directly on Indian audio series, and video microdramas are drawing entertainment budgets from audio. A company that prices a story at ₹5 per episode can lose a listener to a free video clip overnight. Pocket FM's defence is its content library and data, but the barriers are lower than in platforms such as Spotify.
11 VALUATION SCENARIOS
| Valuation | ₹ crore (₹96.5/US$) | x ARR (US$425m mid-point) |
|---|---|---|
| US$750m (prior) | ~7,240 | 1.8x |
| US$1.5bn | ~14,475 | 3.5x |
| US$2bn (target) | ~19,300 | 4.7x |
Rupeia calculation using the ARR mid-point of US$425m.
12 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 25% | Round closes near US$2bn; ARR passes US$600m; profits stay positive |
| Base | 45% | Round closes at US$1.2–1.6bn |
| Bear | 30% | Growth slows; round fails again or prices below US$1bn |
13 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Kill condition |
|---|---|---|
| Hit dependence and content cost | High | Top-ten titles above 40% of revenue |
| Paid-acquisition cost | High | Customer acquisition cost above lifetime value |
| Competition from video micro-dramas | Medium | Share loss to Story TV and ReelShort |
| Unaudited metrics | Medium | Filed revenue far below ARR |
14 INVESTOR CLASS ANALYSIS
HNIs and family offices
Access is through funds. Ask whether ARR is audited and how it is defined before paying for an indirect stake.
Institutions
Lightspeed and Stepstone are existing holders; they will set the terms of any new round.
NRIs
NRIs can hold unlisted Indian shares under FEMA pricing and reporting rules; repatriation depends on the account route used.
15 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Q4 2026–Q1 2027 | Confirmation of the funding round and valuation |
| 2027 | FY26 audited revenue and loss |
| 2027–28 | IPO preparation, if any |
16 RUPEIA FINAL INDEPENDENT VIEW
Pocket FM is a strong Indian consumer-subscription story with unusually fast reported growth and a path to profit. The company's numbers are reported by the press and not yet audited.
| THE RUPEIA NUMBER 2.7x. The step-up from a US$750m valuation to nearly US$2bn that the company is reported to seek. |
|---|
| RUPEIA VERDICT High-growth and unproven in audited numbers. A venture-style position at best. |
|---|
Frequently asked questions
Is Pocket FM raising money?
Reports say it seeks US$100–120m at close to US$2bn.
What is its previous valuation?
About US$750m.
What is its ARR?
Reports cite US$400–450m, unaudited.
Who founded Pocket FM?
Rohan Nayak, Prateek Dixit and Nishanth KS.
Is it profitable?
Reports describe cash-flow profit with EBITDA near 5%; not independently confirmed.
Source log
Inshorts: Pocket FM seeks US$120m at US$2bn (Mint)
NewsBytes: Pocket FM seeks up to US$120m
TechStory: Pocket FM plans new funding round
Tracxn: Pocket FM
PitchBook: Pocket FM
Caplight: Pocket FM
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|