CleanMax Enviro Energy Solutions: ₹2,500 Cr green bond (Sep 2026)
· By Somyesh
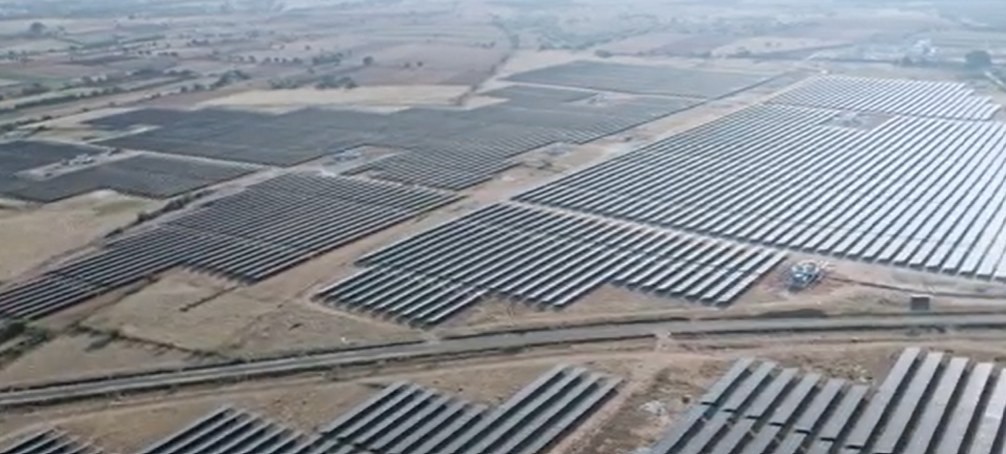
A solar plant, as published with press coverage of CleanMax's financing · Image: pv magazine India
Independent report content
COMPANY
CleanMax Enviro Energy Solutions Ltd (founded 2010), commercial and industrial solar, wind and hybrid power for corporate buyers under open-access and captive structures · founder and MD Kuldeep Jain
MAY 2026 FINANCING
About US$575m for roughly 1 GW of grid-connected projects in Rajasthan and Karnataka · mostly bank loans and ECBs, no equity raise disclosed
SEP 2026 BOND
₹2,500 Cr secured listed green NCDs · five series of 2 to 10 years · coupon 8.25% to 8.76% · CRISIL AA/Stable (CARE separately upgraded its bank-facility and NCD ratings to AA-/Stable, per Mercom) · anchors IFC, NaBFID and IIFCL
IPO
Issue price ₹1,053 · bidding 23–25 Feb 2026 · listed 2 Mar 2026 at about ₹952–960, below issue · DRHP size ₹5,200 Cr, reported actual about ₹3,080–3,100 Cr
FY26
Revenue ₹1,913 Cr (+28%) · EBITDA ₹1,295 Cr · PAT ₹85.6 Cr (₹19.4 Cr in FY25) · 3,088 MW operational
H1 FY27
PAT about ₹120 Cr · net debt ₹13,838 Cr · operating cash flow about −₹200 Cr · EBITDA up 56%
CUSTOMERS
588 customers · data centres and AI infrastructure 42% of the 5.7 GW contracted portfolio
BRIEF CORRECTIONS
Capital Dynamics and Dutch FMO were not found as CleanMax investors; the company was already listed when this note was written
THE ACCESS POINT
CleanMax is listed on NSE and BSE and can be bought in the market. Its bonds are privately placed and listed but are held mainly by institutions.
Executive decision summary
THE BOTTOM LINE
CleanMax sells renewable power to companies and is now a listed business that raises most of its money as debt. In May 2026 it reported about US$575 million of project financing for roughly one gigawatt of solar and wind capacity in Rajasthan and Karnataka, and in September it issued ₹2,500 crore of green bonds at 8.25% to 8.76%, rated CRISIL AA/Stable. Its IPO was priced at ₹1,053 and it listed on 2 March 2026 about 9% below that issue price. In FY26 it earned ₹85.6 crore on ₹1,913 crore of revenue with 3.1 gigawatts operating. Net debt reached ₹13,838 crore at the end of September, operating cash flow was negative about ₹200 crore in the half year, and grid curtailment cut generation sharply in the first half. Management expects EBITDA of at least ₹3,000 crore in FY28, which is an expectation rather than guidance.
WHICH INVESTOR
CleanMax fits a listed-equity or bond investor IF you want exposure to corporate renewable power and accept a high debt load.
Wait IF you need positive operating cash flow, lower curtailment and a clear route to cutting net debt.
COMFORT FIT
C&I renewable power = green electricity sold directly to factories, offices and data centres under long contracts.
Open access = a rule that lets large consumers buy power from a chosen supplier over the grid.
Curtailment = the grid asks a plant to produce less than it could, so revenue is lost.
Green NCD = a bond whose proceeds fund renewable projects.
THE RUPEIA NUMBER
4.75x. FY26 net debt to adjusted EBITDA, with net debt of ₹9,684 Cr rising to ₹13,838 Cr by September 2026.
1 CLAIM REGISTER: EVIDENCE GRADING
Claim
Source
Grade
Rupeia assessment
About US$575m for 1 GW in Rajasthan and Karnataka, May 2026
440.6 + 76 + 74 = US$590.6m; the rupee loans were converted at about ₹85.5 per US$, an older rate
Rate implied by Mercom
₹650 Cr ÷ US$67.9m ≈ ₹95.7 per US$
Interest on ₹2,500 Cr at 8.5%
About ₹212 Cr a year, an illustration at the middle of the stated range
RUPEIA READ
The two totals in the sources are not a contradiction. The US$575 million figure holds when the rupee loans are converted at today's rate and the US$591 million figure appears when an older rate is used, so the right number is about US$575 million. Almost all of the money is debt from banks and development lenders, which means the growth plan is being financed by leverage and not by new shares.
3 LISTING AND OWNERSHIP
Item
Detail
Source quality
DRHP
Filed 18 Aug 2025 for ₹5,200 Cr: fresh issue up to ₹1,500 Cr and offer for sale up to ₹3,700 Cr; SEBI nod Nov 2025
Free Press Journal; Business Today
Issue price and dates
₹1,053; bidding 23–25 Feb 2026; listing 2 Mar 2026
Single source for dates
Reported issue size
₹3,080 Cr, ₹3,083.83 Cr or ₹3,100 Cr, against the DRHP ₹5,200 Cr
Aggregators; unresolved
Listing prices
Open ₹952.20 on BSE and ₹960 on NSE; listing close about ₹867.5; a later last trade ₹846.30 (undated)
Free Press Journal; Trendlyne; 5paisa
History
Warburg Pincus (up to US$100m, 2017) and IFC (US$15m, 2017); Augment Infra ₹1,650 Cr (2021); Brookfield US$360m for 51% (2023); Temasek and Bain led a pre-IPO round of about ₹1,500 Cr
Zawya; YourStory; Venture Intelligence
Augment sell-down
7.25% for ₹1,095.93 Cr; stake down from 9.5% to 2.25%
PTI via HDFC Sky; single source
Calculation (Rupeia)
Result
Opening prices against ₹1,053
BSE ₹952.20 = −9.6%; NSE ₹960 = −8.8%
Listing close against issue price
₹867.5 ÷ ₹1,053 − 1 = −17.6% (the earlier research note's −8.8% belongs to the NSE opening price)
Later last trade against issue price
₹846.30 ÷ ₹1,053 − 1 = −19.6%
Shares sold at the reported ₹3,083.83 Cr
₹3,083.83 Cr ÷ ₹1,053 ≈ 2.93 crore shares
Value implied for 100% by the Augment sale
₹1,095.93 Cr ÷ 7.25% ≈ ₹15,100 Cr (single source)
RUPEIA READ
CleanMax listed at a discount and kept falling in the one later snapshot found, which means early public investors have a loss against the issue price. The gap between the DRHP size of ₹5,200 crore and the reported ₹3,100 crore suggests the offer was cut before launch, but no source in the set says so directly. The price after listing was not verified.
4 THE BUSINESS: EARNINGS, DEBT AND CASH
Measure
Value
Source
FY26 revenue from operations
₹1,913 Cr (+28% from ₹1,496 Cr)
Whalesbook; pv-magazine India
FY26 EBITDA
₹1,295 Cr (+28%); a separate run-rate EBITDA of ₹1,870 Cr (+64%) is a different measure
Whalesbook
FY26 PAT
₹85.6 Cr (₹19.4 Cr in FY25)
Whalesbook
Capacity
3,088 MW operational; 2.6 GW under execution; 5.7 GW contracted
Company, via Whalesbook
FY26 net debt
₹9,684 Cr; 4.75x adjusted EBITDA
Whalesbook; Multibagg
H1 FY27
EBITDA +56%; renewable power sales EBITDA about ₹986 Cr at 84% margin; PAT about ₹120 Cr; net debt ₹13,838 Cr; operating cash flow about −₹200 Cr
At least 1,500 MW added in FY27; capex above ₹10,000 Cr a year; FY28 EBITDA at least ₹3,000 Cr as an expectation, not guidance
Multibagg
Calculation (Rupeia)
Result
FY26 EBITDA and PAT margins
EBITDA ₹1,295 Cr ÷ ₹1,913 Cr = 67.7%; PAT 4.5%
Net debt change in six months
₹13,838 Cr ÷ ₹9,684 Cr − 1 = 42.9%
Contracted capacity check
3,088 MW + 2,600 MW = 5,688 MW, matching 5.7 GW
FY27 capacity addition
1,500 MW ÷ 3,088 MW = +48.6%
FY28 EBITDA target against FY26
₹3,000 Cr ÷ ₹1,295 Cr = 2.3x, about 52% a year over two years
Capex against FY26 EBITDA
₹10,000 Cr ÷ ₹1,295 Cr = 7.7x
H1 profit against FY25 full year
₹120 Cr ÷ ₹19.4 Cr = 6.2x
RUPEIA READ
The business earns an EBITDA margin near two-thirds because the power is sold under long contracts, but most of that is paid out as interest and depreciation, leaving a 4.5% net margin. Net debt rose by almost half in six months while operating cash flow was negative, which is what a company in a heavy build phase looks like. Management attributes part of the weak cash flow to a payment to a wind-turbine supplier, and payable days fell from 334 to about 135–140.
5 THE MARKET AND THE RISKS THAT FOLLOW
Fact
Detail
Source quality
Customers
588; data centres and AI infrastructure 42% of the contracted portfolio (2,380 MW)
Mercom; company
Open access
Consumers above 100 kW can buy renewable power via open access; open-access solar additions 2.7 GW in Q1 2026; Crisil projects C&I open-access renewable capacity could reach 57 GW by FY28
Mercom; Crisil via TaiyangNews; regulatory text not verified
Curtailment
70% in Q1 FY27, 44% in September, 26% in October
Multibagg
Peers
Fourth Partner Energy targets 9 GW by 2031; ReNew group FY26 revenue ₹13,220 Cr (+36.2%) with ReNew Green 2.5 GW committed; Sembcorp agreed to buy ReNew's 300 MW solar unit for about US$246m
Company websites; press
Other deals
Shell India about 30 MW hybrid (Apr 2026); Envision Energy term sheet for 1,550 MW of wind turbines (value ₹155 Cr, single source)
Press
RUPEIA CALCULATION
42% of 5.7 GW is 2.39 GW, matching the 2,380 MW reported for data centres and AI customers. If curtailment of 70% in the first quarter had applied to the whole fleet, generation would have been 30% of potential in that quarter; the sources give curtailment as a share but do not say which assets it covered.
6 RISKS, SCENARIOS AND CHECKLIST
Risk
Evidence
Severity
Kill condition
Leverage
Net debt ₹13,838 Cr; 4.75x EBITDA at FY26
HIGH
Debt grows faster than EBITDA
Cash flow
Operating cash flow about −₹200 Cr in H1 FY27
HIGH
Negative cash flow persists
Curtailment
70% in Q1 FY27, falling to 26% in October
MEDIUM
Grid limits return
Customer concentration
42% of contracted portfolio to data centres and AI
Growth and contracts, but leverage and a price below issue
Fixed-income investor
PARTIAL
AA rating and 8.25–8.76% coupon, with a heavy build programme
Short-term trader
WATCH
Lock-in dates and quarterly results
Rupeia does not recommend buying or selling any security and is not a SEBI-registered investment adviser or research analyst. Open items are current share price, bond lenders and operating cash flow.
7 KEY TERMS USED IN THIS REPORT
The terms below are used in this report. Each is explained in plain words.
Term
Meaning
C&I
Commercial and industrial customers, such as factories and data centres.
Open access
A rule allowing large consumers to buy power from a chosen supplier over the grid.
Curtailment
The grid asks a plant to produce less than it could.
ECB
External commercial borrowing: a foreign-currency loan to an Indian company.
Green NCD
A non-convertible debenture whose money goes to environmentally approved projects.
Net debt to EBITDA
Debt less cash divided by operating profit; a measure of leverage.
Frequently asked questions
What did CleanMax raise in 2026?
About US$575 million of project financing for roughly 1 GW in May, and ₹2,500 crore of green bonds in September, plus an IPO that listed on 2 March 2026.
Is CleanMax listed?
Yes. It listed on NSE and BSE on 2 March 2026 after an issue price of ₹1,053 and opened below it.
What does CleanMax earn?
FY26 revenue was ₹1,913 crore with EBITDA of ₹1,295 crore and a profit of ₹85.6 crore.
How much debt does it have?
Net debt was ₹9,684 crore at FY26 (4.75 times adjusted EBITDA) and ₹13,838 crore at 30 September 2026.
Who are CleanMax's customers?
588 customers; data centres and AI infrastructure are 42% of the contracted power-sales portfolio.
What is curtailment?
When the grid asks a plant to produce less than it could. CleanMax reported 70% in the first quarter of FY27, falling to 26% in October.
Source log
Powerline: CleanMax raises US$575 million for 1 GW renewable projects across Rajasthan and Karnataka
Infrastructure Today: CleanMax raises US$575 million for 1 GW renewable push
Yahoo Finance: CleanMax raises US$575 million for India renewable buildout
Mercom India: CleanMax secures US$575 million for 1 GW solar, wind projects
Energetica India: CleanMax raises ₹2,500 crore through green NCDs
Multibagg: CleanMax fixes 53.7% debt after ₹2,500 crore green bond
Whalesbook: CleanMax FY26 profit soars 4.4x to ₹86 crore as capacity hits 3 GW
pv-magazine India: CleanMax posts 340% growth in consolidated PAT for FY2025-26
Free Press Journal: Clean Max Enviro Energy lists at 10% discount on BSE and NSE
DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing.