Clinics On Cloud: ₹120 crore at ₹600 crore Series A
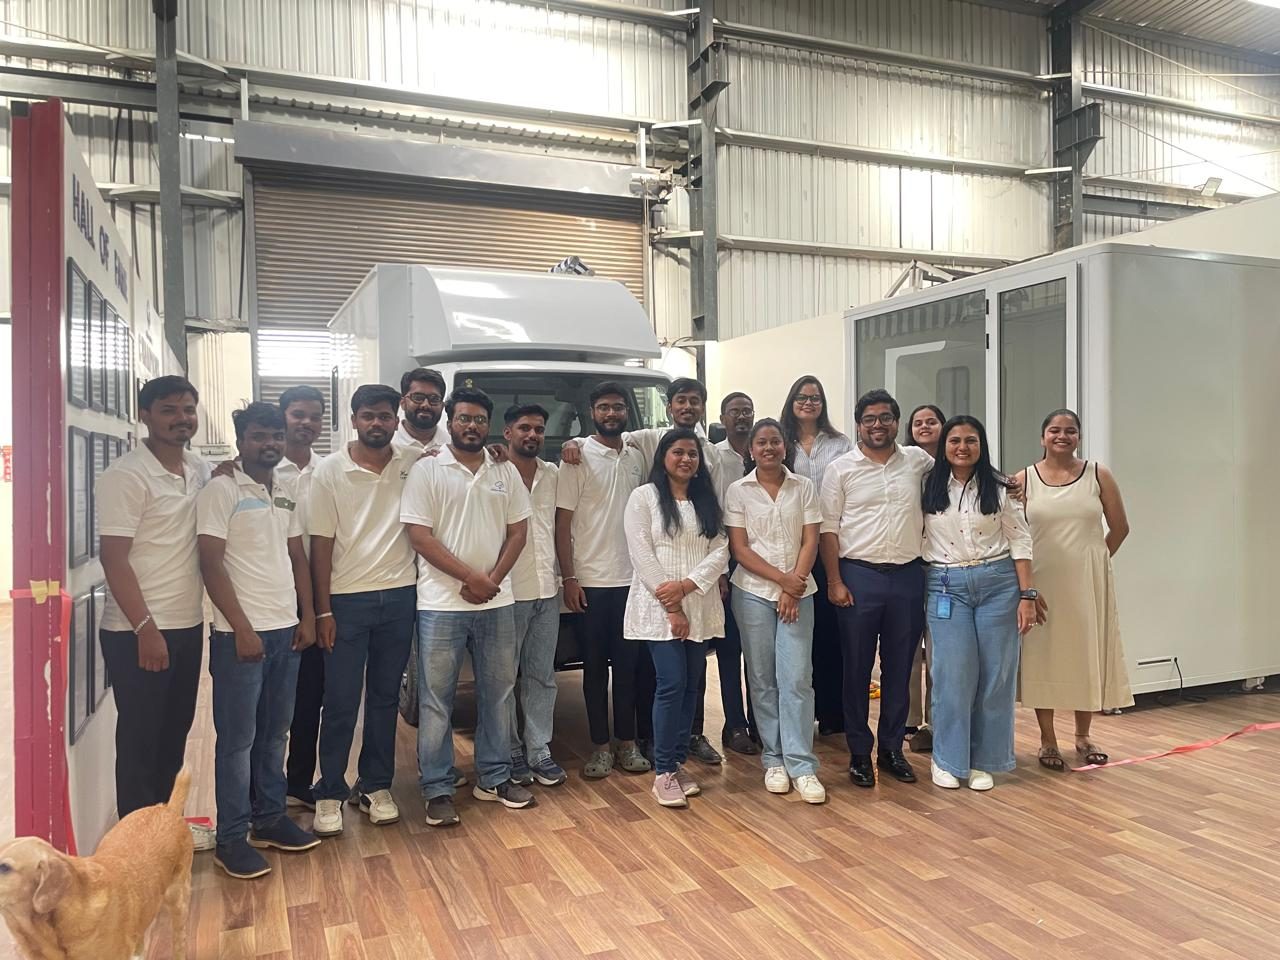
The Clinics On Cloud team Source: Clinics On Cloud
Independent report content
| ROUND | Series A · ₹120 crore (about US$12.5m) · announced 2–3 Nov 2026 |
|---|---|
| INVESTOR | Model42, the medtech investment arm of UAE-based Enlightened Minds Investments (sole named investor) |
| VALUATION | ₹600 crore (about US$63m) as reported by Inc42 and Digital Health News; pre- or post-money not stated |
| PRIOR FUNDING | None disclosed. The company says it was bootstrapped for eight years |
| REVENUE | FY25 total revenue ₹17.4 crore; expenses ₹15.8 crore; profit after tax ₹1.2 crore (Inc42 extract of filings) |
| KEY METRIC | 3,500+ deployments in 200 cities across India and seven other countries; 1.2 crore+ people screened (company) |
| PRODUCTS | Health ATM / health kiosk, Health Lounge, portable Box Clinic, mobile medical units, AI health reports and teleconsultation |
| USE OF FUNDS | UAE as a base for Africa, the US and Southeast Asia; AI capabilities; R&D; micro-clinic network |
| COMPANY | Sehatpro Technologies Pvt Ltd · founded 2017–18 by Abhay Agarwal (CEO) and Manashrri Agarwal · plant at Chakan MIDC, Pune |
| THE ACCESS POINT Clinics On Cloud is a private company with a single disclosed outside investor, Model42 of the UAE. There is no fund, listed vehicle or regular secondary market that gives exposure. An individual investor could only participate through a negotiated purchase from founders or a future round, which would most likely be offered to family offices and healthcare-focused funds. |
|---|
Executive decision summary
| THE BOTTOM LINE Clinics On Cloud builds and installs health ATMs: kiosks and portable clinic boxes that run dozens of screening tests in minutes and connect the user to a doctor by video. It was profitable and self-funded for eight years. FY25 revenue was ₹17.4 crore with ₹1.2 crore of profit. Its first outside round, ₹120 crore from the UAE's Model42, priced the company at ₹600 crore. That is about 34 times FY25 revenue, a large multiple for a hardware-led business. The money funds an international push from the UAE. The thesis is that a low-cost, Indian-made screening box can sell to governments, employers and pharmacies across emerging markets. The weakness is visibility: one investor, no audited FY26 figures, and a 2024 public promise of ₹100 crore revenue by 2026 that the filed numbers do not yet support. |
|---|
| WHICH INVESTOR Clinics On Cloud fits you IF you want early exposure to point-of-care screening hardware made in India, can accept a single-investor cap table, and can wait 5–7 years for an exit through a strategic sale or a later round. Look elsewhere IF you need disclosed audited growth, a diversified investor base or near-term liquidity. The ₹600 crore price already assumes several years of strong growth. |
|---|
| COMFORT FIT Clinics On Cloud = the ATM maker for health checks. It builds the machine, places it where people already are (offices, pharmacies, army camps) and earns from the box and the service. Diagnostic chains (Dr Lal PathLabs, Metropolis, Thyrocare) = the bank branches. Full-service, accredited, listed and profitable, but expensive to reach rural India. Krsnaa Diagnostics = the government-contract operator. It shows how public-private screening contracts can scale, and how they can delay payment. Even Healthcare = the integrated health plan (see Rupeia's Even report). It is a possible buyer of screening capacity, not a competitor. |
|---|
| THE RUPEIA NUMBER 34x. ₹600 crore valuation divided by ₹17.4 crore of FY25 revenue. Listed Indian diagnostics companies trade at roughly 4–10x revenue. Clinics On Cloud is being priced as a high-growth technology platform. FY26 revenue, due in filings over the next few months, has to show a step change for the price to hold. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
Every material claim in this note is graded by the strength of its published source. A = government, regulator or customer record. B = statutory filing or financial statement (including extracts). C = independent press. D = company announcement.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| ₹120 crore Series A from Model42 | Inc42, YourStory, Entrepreneur India, Digital Health News (Nov 2026) | C | Established as an announced round. Allotment filing (PAS-3) and price per share not yet public. |
| Valuation ₹600 crore | Inc42; Digital Health News | C | Reported. The basis (pre- or post-money) is not stated. Rupeia treats it as post-money in the base case. |
| Bootstrapped for eight years | Company statements in round coverage | D | Consistent with databases showing no earlier institutional round. |
| FY25 revenue ₹17.4 crore, PAT ₹1.2 crore, expenses ₹15.8 crore | Inc42 financials page (filing extract) | B | Established from a secondary extract. Rupeia has not inspected the audited PDF. |
| 3,500+ deployments, 200 cities, 8 countries, 1.2 crore screenings | Company statement via Inc42 (Nov 2026) | D | Company figures. In 2024 the company cited 3,000 units and 80 lakh screenings, so the growth claim is internally consistent. |
| Serves the Indian Army, Navy and BSF | Company statement; client marks on company website | D | Plausible; no public tender award found by Rupeia. Contract values unknown. |
| Set to cross ₹100 crore revenue by 2026 | Digital Health News (2024 interview) | C | A past management forecast. FY25 revenue was ₹17.4 crore. |
| 80% share of India's health ATM market | The Quint brand studio (sponsored content) | D | Paid content. Treat as marketing. |
| Health Kiosk and Health Lounge live at Reliance corporate headquarters | Company newsroom (15 Jul 2026) | D | Named enterprise reference; deal value not disclosed. |
| CDSCO, CE, US FDA, ISO 13485, ISO 27001 and HIPAA marks | Company website | D | Certification marks displayed. Scope of each (which device, which class) not published. |
2 COMPANY OVERVIEW & FOUNDING STORY
Clinics On Cloud is the trading name of Sehatpro Technologies Private Limited, a Pune company. Inc42's database dates the incorporation to 2017; round coverage gives 2018 as the operating start. Its founders are Abhay Agarwal (co-founder and CEO) and Manashrri Agarwal (co-founder and managing director). The company designs and assembles its devices at its own plant in Chakan MIDC, outside Pune.
The idea is to move routine screening out of hospitals. A health ATM is a booth or kiosk with built-in instruments: weight and body composition, blood pressure, pulse oximetry, temperature, ECG, blood glucose and other point-of-care tests. The company says its kiosks measure more than 65 parameters. Results are compiled into an AI-generated report and the user can speak to a doctor by video on the spot. The same kit is packed into a portable Box Clinic for health camps, and into vans as mobile medical units.
What the company sells
| Product | Format | Typical buyer | Revenue type |
|---|---|---|---|
| Health ATM / Health Kiosk | Enclosed or open kiosk with 50–65+ tests and teleconsultation | State health missions, corporates, pharmacies, housing societies | Hardware sale or lease, plus service and consumables |
| Health Lounge | Larger walk-in screening space built around kiosks | Corporate campuses (e.g. Reliance HQ) | Project fee plus service |
| Portable Box Clinic | Suitcase-style digital clinic set up in minutes | Health camps, NGOs, defence and paramilitary units | Hardware sale |
| Mobile medical unit | Van fitted with screening equipment | Government programmes, CSR projects | Vehicle build plus operations contract |
| Software and AI reports | Health records, analytics, doctor network | All of the above | Subscription or per-screening fees |
This mix matters for valuation. Most revenue today almost certainly comes from building and selling hardware. Recurring income from software, consumables and per-screening fees is what investors would pay a technology multiple for, and the company has not disclosed the split.
3 TIMELINE: 2017–2026
| Year | Milestone |
|---|---|
| 2017 | Sehatpro Technologies Pvt Ltd incorporated (Inc42 database) |
| 2018 | Clinics On Cloud begins operations in Pune; first health ATM builds |
| 2019–2022 | Box Clinic and mobile units added; defence and paramilitary orders (company); exports begin |
| 2024 | Company cites 3,000+ health ATMs in India and seven countries and 80 lakh screenings; tells Digital Health News it expects to cross ₹100 crore revenue by 2026 |
| FY25 | Total revenue ₹17.4 crore; profit after tax ₹1.2 crore (filing extract) |
| Jul 2026 | Health Kiosk and Health Lounge go live at Reliance corporate headquarters; pharmacy kiosk tie-up with PharmDrive |
| 2–3 Nov 2026 | ₹120 crore Series A from Model42 at a reported ₹600 crore valuation; UAE named as international base |
4 FUNDING HISTORY & INVESTOR BEHAVIOUR FORENSICS
| Date | Round | Amount | Investor | Comment |
|---|---|---|---|---|
| 2017–2026 | Founder capital and internal accruals | Not disclosed | Founders | Eight years without outside equity |
| Nov 2026 | Series A | ₹120 crore | Model42 (Enlightened Minds Investments, UAE) | First institutional round; sole investor named |
What the investor pattern shows
A strategic, not a syndicate. One Gulf-based medtech investor wrote the whole cheque. That suggests the round was negotiated around the UAE expansion, possibly with commercial help in the Gulf. It also means no Indian VC has yet tested the price.
No insider follow-on signal exists because there were no earlier investors. The usual check (do existing backers keep investing?) cannot be applied.
Bootstrapped history is a strength. The company reached ₹17 crore of revenue and a profit without outside money, which says something about cost discipline.
Primary or secondary? Coverage describes the money as growth capital for expansion and R&D, which implies primary. The split has not been confirmed in a filing.
| RUPEIA CALCULATION If ₹600 crore is post-money, Model42 owns ₹120 crore ÷ ₹600 crore = 20%. If ₹600 crore is pre-money, post-money is ₹720 crore and Model42 owns 16.7%. Either way the founders keep a large majority, which is unusual and favourable for alignment. |
|---|
5 FINANCIAL FORENSICS: WHAT THE FILINGS SHOW
| Metric | FY25 | Reading |
|---|---|---|
| Total revenue | ₹17.4 crore | Includes any other income; operating revenue not separately confirmed |
| Total expenses | ₹15.8 crore | Implies a pre-tax surplus of about ₹1.6 crore |
| Profit after tax | ₹1.2 crore | Net margin about 6.9% |
| FY26 (Apr 2025–Mar 2026) | Not yet public | Due with the registrar by about end-November 2026 |
| Outside equity before Nov 2026 | Nil disclosed | Growth funded from operations |
A profitable hardware business is rarer in Indian healthtech than it should be. The concern is scale against promises. In 2024 the company publicly targeted ₹100 crore revenue by 2026. Filed FY25 revenue was ₹17.4 crore.
| Scenario for FY26 revenue | FY26 revenue | Growth on FY25 | Valuation ÷ FY26 revenue |
|---|---|---|---|
| Hits the 2024 target | ₹100 crore | 5.7x | 6x |
| Strong year | ₹45 crore | 2.6x | 13x |
| Doubles | ₹35 crore | 2.0x | 17x |
| Grows 40% | ₹24 crore | 1.4x | 25x |
6 BUSINESS MODEL & UNIT ECONOMICS
The company does not publish unit prices or margins. Public tender documents in India price multi-parameter health kiosks over a wide range depending on the test menu and enclosure. Rupeia therefore shows the model's shape, not its exact numbers.
| Lever | How it works | What would prove it |
|---|---|---|
| Hardware margin | In-house design and assembly at Chakan lowers bill of materials versus imported kiosks | Gross margin disclosed above 40% on hardware |
| Utilisation | Revenue per kiosk rises with screenings per day where fees are per test | Screenings per installed unit per month |
| Consumables | Glucose strips, cuvettes and printed reports sold with every test | Consumable revenue as a share of total |
| Software and doctors | Teleconsultation and reports on a subscription | Annual recurring revenue figure |
| Government contracts | Large orders for camps and rural centres; often operate-and-maintain | Named state contracts and receivable days |
| RUPEIA CALCULATION 3,500 deployments over about eight years and ₹17.4 crore of FY25 revenue. If FY25 added, say, 500–700 units, revenue per new unit including services would be roughly ₹2.5–3.5 lakh. That looks like a mid-priced kiosk business, not a large recurring-software base. The company's own deployment count per year is the missing figure. |
|---|
7 CUSTOMER & CONTRACT INTELLIGENCE
| Customer / channel | What is known | Grade | Reading |
|---|---|---|---|
| Indian Army, Indian Navy, BSF | Named by the company as customers; logos on website | D | Defence and paramilitary health camps; values unknown |
| AIIMS | Logo shown on website | D | Likely pilot or camp use |
| Reliance corporate headquarters | Health Kiosk and Health Lounge live (Jul 2026) | D | Marquee corporate reference |
| Corporates: Bajaj, Godrej, HP, IDBI, Konica Minolta, Medi Assist | Logos on website | D | Workplace wellness and insurance-linked screening |
| PharmDrive pharmacies | Kiosks placed inside pharmacies to create micro-clinics | D | Retail channel; tests per day will decide economics |
| Overseas | Seven countries outside India (company); UAE next | D | Countries not named |
The customer list is broad but almost entirely company-published. Rupeia found no government e-marketplace (GeM) or state tender award naming Clinics On Cloud in this review. That does not mean none exists; it means the strongest grade of evidence is missing. A family office doing diligence should ask for the top ten customers by FY25 and FY26 revenue.
8 MARKET & COMPETITIVE ANALYSIS
India has about 1.4 billion people and a shortage of primary-care doctors in rural areas. The government's own primary-care network (Ayushman Arogya Mandirs, formerly Health and Wellness Centres) runs screening for diabetes, hypertension and common cancers. That creates demand for cheap, connected screening devices, from the state, from employers and from insurers.
| Company | Type | Overlap | Edge vs Clinics On Cloud |
|---|---|---|---|
| Yolo Health (Bhopal) | Private health ATM maker | Direct | Similar kiosk model; competes on government tenders |
| Imported kiosk makers (e.g. SoloHealth-type US kiosks) | Global | Direct outside India | Brand in the US; higher cost |
| Dr Lal PathLabs, Metropolis, Thyrocare | Listed diagnostics chains | Indirect | Accredited lab tests; scale; listed and profitable |
| Krsnaa Diagnostics | Listed PPP diagnostics operator | Indirect (government contracts) | Proven at state-level contracts |
| Healthians, Redcliffe, Tata 1mg Labs | Home-collection labs | Indirect | Lab-grade tests at the doorstep |
| Apollo, Practo, Tata 1mg teleconsultation | Telemedicine | Indirect | Doctor networks and brands |
Listed diagnostics peers trade at roughly 4–10x revenue depending on growth and margin. Point-of-care device makers abroad trade on hardware multiples. Clinics On Cloud's ₹600 crore price is closer to a software multiple.
9 MOAT ANALYSIS
| Moat source | Strength | Comment |
|---|---|---|
| In-house manufacturing at Chakan | Medium | Lower cost and faster customisation than importers; Make in India preference in public tenders |
| Installed base and screening data | Medium | 1.2 crore screenings is a useful dataset if consented and portable under data law |
| Regulatory approvals | Medium | CDSCO and CE marks take time; scope undisclosed |
| Defence and government references | Medium | Helpful for tenders; tenders are price-led |
| Brand with consumers | Weak | Buyers are institutions; end users rarely choose the kiosk brand |
10 FOUNDERS' PATH
Abhay Agarwal leads product, innovation and global expansion, according to the company's team page. He has been the public face of the health ATM category in Indian media since 2019. Manashrri Agarwal is co-founder and, per Inc42's database, managing director. The two built the company without outside capital for eight years, which shaped a frugal operating style.
Neither founder's earlier corporate career is documented in detail in the sources Rupeia reviewed. Investors should ask for full biographies, including any earlier companies, as part of diligence.
11 TEAM, GOVERNANCE & PEOPLE
Board. A founder-controlled board until now. Model42 will normally take a board or observer seat after a 16–20% stake.
Related parties. The two founders share a surname and control the company. Related-party transactions should be checked in the FY25 and FY26 notes to accounts.
Manufacturing. An owned plant with production, assembly and quality-inspection areas at Chakan MIDC (company manufacturing page).
Auditor and controls. Not disclosed publicly. A first institutional round usually triggers a move to a larger audit firm.
12 POLICY & REGULATORY SURFACE
Medical Devices Rules, 2017. All medical devices in India now need registration or licence from CDSCO or state licensing authorities by risk class. Each instrument inside a kiosk (BP monitor, glucometer, ECG) may need its own approval.
Telemedicine Practice Guidelines (2020). Allow registered doctors to consult by video and prescribe within limits. The kiosk's doctor network must follow them.
Digital Personal Data Protection Act, 2023 and Rules (2025). Health screening data is personal data. Consent, purpose limits and breach reporting now carry penalties of up to ₹250 crore per breach.
Ayushman Bharat Digital Mission (ABDM). Linking screenings to ABHA health IDs could make kiosks part of the national health record system; the company displays an ABDM mark.
Exports. Gulf and African markets require their own device registrations (for example the UAE's Ministry of Health and Prevention). US FDA clearance for a full kiosk is a high bar; the website mark should be checked against the FDA database.
13 VALUATION ANALYSIS
| Measure | Value | Comment |
|---|---|---|
| Reported valuation | ₹600 crore | About US$63m at ₹95–96 per dollar |
| ÷ FY25 revenue (₹17.4 crore) | 34x | Technology-platform multiple |
| ÷ FY25 PAT (₹1.2 crore) | 500x | Not a meaningful anchor at this size |
| Listed diagnostics, EV/revenue | ~4–10x | Lal PathLabs, Metropolis, Thyrocare, Krsnaa (range, 2026) |
| FY26 revenue needed for 10x | ₹60 crore | 3.4x FY25 |
| RUPEIA READING The price assumes the business is about to grow several-fold, most likely helped by large contracts already in hand or the 2024 ₹100 crore ambition being partly met in FY26. If FY26 revenue is closer to ₹25 crore, the round looks generously priced for a hardware company. |
|---|
14 SCENARIO ANALYSIS
| Scenario | Probability (Rupeia) | What has to happen | FY28 revenue | Value effect |
|---|---|---|---|---|
| Bull | 25% | Gulf government or hospital-group contracts; a state-wide Indian programme; software and consumables reach 30% of revenue | ₹150 crore+ | Series B at 2x+ the Series A price |
| Base | 50% | Steady corporate and pharmacy growth; one or two overseas markets work | ₹60–100 crore | Flat to modest step-up |
| Bear | 25% | Overseas expansion burns cash; tenders priced down; FY26 growth weak | <₹40 crore | Down round or strategic sale below ₹600 crore |
15 ENTRY MATHS FOR A LATE INVESTOR
There is no secondary market in the shares. If founders or Model42 later sell a small stake, the test is simple: what revenue does the price assume?
| Entry valuation | Revenue needed at 8x | Revenue needed at 5x | Comment |
|---|---|---|---|
| ₹600 crore (Series A) | ₹75 crore | ₹120 crore | Needs 4–7x FY25 revenue |
| ₹450 crore (25% discount) | ₹56 crore | ₹90 crore | More reasonable for a late entrant |
| ₹900 crore (next-round premium) | ₹113 crore | ₹180 crore | Only after audited FY27 |
16 EXIT ANALYSIS
| Route | Likelihood (5–7 yrs) | Comment |
|---|---|---|
| Strategic sale to a hospital group, diagnostics chain or Gulf healthcare holding | Medium | Model42's parent could itself become the buyer |
| SME IPO in India | Medium | A profitable hardware company with ₹50–100 crore revenue fits the SME board |
| Main-board IPO | Low | Needs much larger, audited scale |
| Secondary to a later investor | Medium | Most likely route for any early minority holder |
17 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Evidence | Kill condition |
|---|---|---|---|
| Forecast credibility | High | ₹100 crore by 2026 promised; ₹17.4 crore in FY25 | FY26 revenue below ₹30 crore |
| Valuation stretch | High | 34x FY25 revenue | Next round flat or down |
| Single-investor dependence | Medium | Only Model42 named | Investor exits or blocks follow-on funding |
| Overseas execution | Medium | UAE, Africa, US, SE Asia at once | No named overseas contract by end-2027 |
| Government receivables | Medium | Tender customers pay late | Receivable days above 150 |
| Device regulation | Medium | Multiple instruments, multiple countries | Any recall or licence suspension |
| Data protection | Medium | 1.2 crore screenings of health data | A reported data breach |
18 INVESTOR CLASS ANALYSIS
For HNIs
There is no route in today. If offered shares, ask for the Series A share price, the shareholders' agreement (especially Model42's rights) and audited FY26 accounts.
For family offices
Healthcare family offices could co-invest in a Series B. Diligence priorities: revenue by customer, hardware versus recurring split, overseas pipeline, and regulatory approvals by device.
For institutions
Healthcare PE funds will wait for ₹75–100 crore revenue. Insurers and hospital groups may prefer commercial partnerships first.
For NRIs
Unlisted Indian shares can be held under FEMA non-debt instrument rules. Gulf-based NRIs may find the UAE subsidiary a more natural future entry point if it raises locally.
19 COMFORT FIT: THE DECISION PAGE
| If you want… | Best fit | Why | Caution |
|---|---|---|---|
| Indian-made screening hardware with profits | CLINICS ON CLOUD | Bootstrapped, profitable, own plant | 34x revenue price; one investor |
| Listed diagnostics | Dr Lal PathLabs, Metropolis, Thyrocare | Liquid; audited | Slower growth |
| Government health contracts | Krsnaa Diagnostics | Listed PPP model | Receivable risk |
| Integrated care and insurance | Even Healthcare (Rupeia report) | Owns the patient relationship | Loss-making growth stage |
20 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event | Why it matters |
|---|---|---|
| Nov 2026–Jan 2027 | FY26 accounts filed with the MCA | First test of the ₹600 crore price |
| Q4 2026 | PAS-3 allotment filing for the Series A | Confirms price per share, primary amount and Model42's stake |
| H1 2027 | UAE entity set-up and first Gulf contract | Proves the use of funds |
| 2027 | Any state-wide Indian screening contract | Large, visible revenue step |
| 2027 | Hiring of a CFO or independent director | Governance upgrade before Series B |
21 RUPEIA FINAL INDEPENDENT VIEW
Clinics On Cloud is a real, profitable business with its own factory and a recognisable product. It has done what many funded healthtech startups have not: grown to ₹17 crore of revenue while making money. The ₹120 crore round from Model42 gives it its first serious capital and a route into the Gulf. The price is the issue. At ₹600 crore, the company is valued at 34 times its last filed revenue, and its own 2024 forecast of ₹100 crore by 2026 is far ahead of what the filings show. Rupeia would want FY26 accounts and a named overseas contract before paying anything near the Series A price.
| THE RUPEIA NUMBER 34x FY25 revenue. FY26 revenue of ₹60 crore would bring it to 10x; anything below ₹30 crore leaves the round looking expensive. |
|---|
| RUPEIA VERDICT Credible operator, full price. Watch, do not chase. Revisit after the FY26 filing and the Series A allotment details. |
|---|
Frequently asked questions
How much did Clinics On Cloud raise?
₹120 crore (about US$12.5 million) in a Series A from Model42, the medtech arm of UAE-based Enlightened Minds Investments, announced in early November 2026.
What is Clinics On Cloud's valuation?
₹600 crore (about US$63 million), as reported by Inc42 and Digital Health News. The company has not said whether this is pre- or post-money.
What is Clinics On Cloud's revenue?
FY25 total revenue was ₹17.4 crore with ₹1.2 crore of profit after tax, according to Inc42's extract of its filings. FY26 figures are not yet public.
What is a health ATM?
A kiosk with built-in medical instruments that runs dozens of screening tests, such as blood pressure, glucose, ECG and body composition, and links the user to a doctor by video.
Who founded Clinics On Cloud?
Abhay Agarwal (CEO) and Manashrri Agarwal. The company is registered as Sehatpro Technologies Pvt Ltd in Pune.
Who are Clinics On Cloud's customers?
The company names the Indian Army, Navy and BSF, corporates including Reliance, Bajaj and Godrej, and pharmacy chains. Contract values are not disclosed.
Was Clinics On Cloud bootstrapped?
Yes. The company says it ran for eight years without outside investment before the November 2026 Series A.
Can I invest in Clinics On Cloud?
Not through any public route. It has one outside investor and no secondary market. Any future access would come through a later private round.
Source log
Inc42: Clinics On Cloud bags ₹120 Cr to take its health ATMs global (Nov 2026)
Digital Health News: Clinics On Cloud raises INR 120 Cr at INR 600 Cr valuation (Nov 2026)
YourStory: Clinics On Cloud raises $12.5M to expand microclinic network (Nov 2026)
Entrepreneur India: Clinics On Cloud raises USD 12.5 Mn in Series A (Nov 2026)
StartupTalky: Clinics On Cloud raises ₹120 Cr Series A from Model42 (Nov 2026)
Inc42 DataLabs: Clinics On Cloud financials
Inc42 DataLabs: Clinics On Cloud people
Digital Health News: Clinics on Cloud to hit INR 100 Cr milestone (2024)
The Quint brand studio: Meet Abhay Agarwal (sponsored)
Clinics On Cloud: Home and newsroom (Reliance HQ, PharmDrive)
Clinics On Cloud: Our Team
Clinics On Cloud: Manufacturing facility, Chakan
Indian Pharma Post: Pune health-tech startup Clinics On Cloud raises $12.5 million (Nov 2026)
CDSCO: Medical Devices Rules, 2017
Ministry of Health: Telemedicine Practice Guidelines (Mar 2020)
MeitY: Digital Personal Data Protection Act, 2023
National Health Authority: Ayushman Bharat Digital Mission
Ayushman Arogya Mandir (Health and Wellness Centres)
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|