Aster DM Quality Care: TPG's Centella block sale (Aug 2026) and Moopen
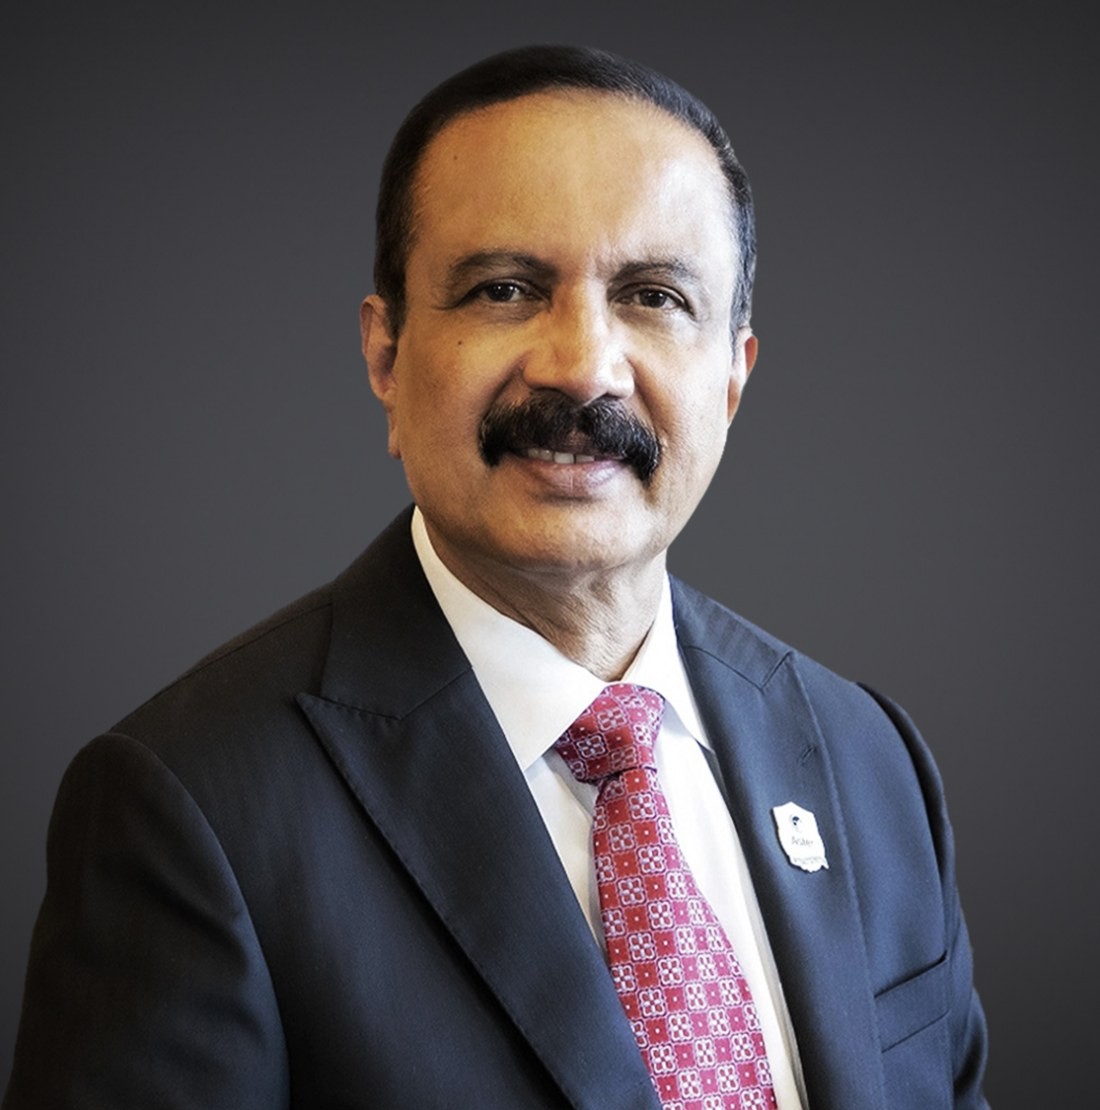
Dr Azad Moopen, founder chairman of Aster DM Healthcare · Image: Aster DM Healthcare website
Independent report content
| COMPANY | Aster DM Quality Care Ltd (formerly Aster DM Healthcare), listed hospital group formed by merging Aster DM Healthcare with Quality Care India · NCLT Hyderabad sanction 19 Jun 2026 |
|---|---|
| MERGER TERMS | 977 Aster shares for every 1,000 Quality Care India shares · shareholder approval 96.68% · 87.17 crore shares after the merger (InvestyWise) |
| BLOCK SALE | Centella Mauritius (a TPG vehicle) sold 5.81 crore shares, 6.66%, at an average ₹766.17, ₹4,451.45 Cr (bulk-deal data) · Business Today put the block at 6.24 crore shares, 7.2% |
| MOOPEN PURCHASE | Union (Mauritius) Holdings bought 46.09 lakh shares, about 0.57%, at ₹760, about ₹350 Cr, on 2 Sep 2026 · family holding about 24.58% |
| RESIDUAL | Centella left with 3.24% (or 2.74% on the larger block), under a 60-day lock-in |
| SCALE | FY26 pro forma revenue ₹9,273 Cr and operating EBITDA ₹2,013 Cr · Q1 FY27 pro forma revenue ₹2,597 Cr (+20%), EBITDA ₹576 Cr (+30%) |
| NETWORK | 10,559 operational beds against 10,898 capacity beds · blended occupancy about 64% |
| BLOCK BUYERS | PTI via HDFC Sky names HDFC Mutual Fund, Kotak Mahindra Mutual Fund, Citigroup Global Markets Singapore and Integrated Core Strategies Asia as buyers of 2,98,60,469 shares (about 3.4%) at about ₹766.1; the rest of the block is unattributed |
| NOT PUBLISHED | TPG entry price and returns, Q1 FY27 ARPOB |
| THE ACCESS POINT Aster DM Quality Care is listed on NSE and BSE. Anyone can buy it in the market; no private access is needed. |
|---|
Executive decision summary
| THE BOTTOM LINE | Aster DM Quality Care is a large listed hospital group made by merging Aster DM Healthcare with Quality Care India, and the merger changed who owns it. TPG's vehicle Centella Mauritius received 9.90% of the enlarged company, then sold about 6.7% in a block on 18 and 19 August 2026 for ₹4,451 crore, leaving 3.24%. Two weeks later the founding Moopen family bought a further 0.57% from Centella at ₹760, about ₹350 crore, taking its holding to about 24.58%. Pro forma FY26 revenue is ₹9,273 crore and operating EBITDA ₹2,013 crore, with Q1 FY27 growth of 20% and 30% respectively. The record has gaps: the block's size differs between sources, only part of the buyers are named, and no returns for TPG or earlier investor Olympus are published. |
|---|---|
| WHICH INVESTOR | The group fits a listed-equity investor IF you want exposure to Indian hospital capacity growth with a promoter that bought more shares after the sell-down. Wait IF you need the full list of block buyers, TPG's returns or Q1 ARPOB: they were not found. |
| COMFORT FIT | Block deal = a large share sale done in one trade, usually at a small discount to the market price. Pro forma = results shown as if the merger had happened for the full period. Occupancy = the share of operational beds filled by patients. Lock-in = a period during which a seller agrees not to sell more. Centella's residual stake has 60 days. |
| THE RUPEIA NUMBER | ₹4,451 Cr. The value of TPG's block sale at an average ₹766.17 a share, per bulk-deal data: 5.81 crore shares, 6.66% of the company. |
1 CLAIM REGISTER: EVIDENCE GRADING
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Merger sanctioned by NCLT 19 Jun 2026; 977:1,000 exchange ratio | InvestyWise; IndiaPharmaPost | C | Established |
| Block of 5.81 crore shares, 6.66%, ₹4,451.45 Cr at ₹766.17 | Venture Intelligence; HDFC Sky (bulk-deal data) | B | Established |
| Block of 6.24 crore shares, 7.2%, about ₹4,780 Cr | Business Today; Bar & Bench | C | Conflicts with bulk-deal data |
| Moopen purchase 0.57% (0.52% in one source) at ₹760 | Angel One; HDFC Sky; SAHI | C | Established; percentage differs |
| Pro forma FY26 revenue ₹9,273 Cr, EBITDA ₹2,013 Cr | Whalesbook; InvestyWise | C | Company figures, as reported |
| Buyers: HDFC MF, Kotak MF, Citigroup Global Markets Singapore, Integrated Core Strategies Asia | HDFC Sky (PTI) | C | Named buyers of about 3.4%; other buyers not named |
| TPG and Olympus returns | Not found | D | Missing; not estimated |
2 THE MERGER AND THE SHARE COUNT
| Item | Detail |
|---|---|
| Scheme | Aster DM Healthcare merged with Quality Care India Ltd (QCIL); the listed entity was renamed Aster DM Quality Care |
| NCLT sanction | Hyderabad Bench, 19 Jun 2026; shareholders approved the swap with 96.68% |
| Exchange ratio | 977 Aster shares for 1,000 QCIL shares |
| Shares credited to Centella | 17 Aug 2026: 8,16,65,541 shares; holding rose from 0.90% (46,51,992 shares) to 9.90% (8,63,17,533 shares) |
| Shares in issue after the merger | 87,16,72,439 |
| QCIL sponsor | Described as Blackstone-backed (ThePrint); Venture Intelligence says TPG advised on the merger. The two sources conflict |
| Calculation (Rupeia) | Result |
|---|---|
| Centella holding check | 8,63,17,533 ÷ 87,16,72,439 = 9.90% |
| New shares issued to all QCIL holders | 87.17 crore − 51.81 crore (pre-deal Aster) ≈ 35.4 crore; Centella took 8.17 crore, about 23% of them |
| Residual after the 5.81 crore block | (8.63 − 5.81) ÷ 87.17 = 3.24%, matching Venture Intelligence |
| Residual after the 6.24 crore block | (8.63 − 6.24) ÷ 87.17 = 2.74%, matching the other report |
| Market value at ₹766 | 87.17 crore × ₹766 ≈ ₹66,770 Cr, about US$6.9bn at ₹96.5 per US$ |
| RUPEIA READ The research note raised a worry that 51.81 crore plus 8.17 crore shares does not add to 87.17 crore. It does once the other Quality Care holders are counted: the merger issued about 35 crore new shares in total and Centella received about 23% of them. Both the 3.24% and 2.74% residual figures reconcile with their own block sizes, so the conflict is about which block size is right, not about the share count. |
|---|
3 THE BLOCK SALE AND THE PROMOTER PURCHASE
| Date | Event | Detail |
|---|---|---|
| 17 Aug 2026 | Shares credited | Centella receives 8.17 crore shares under the merger |
| 18–19 Aug 2026 | Block sale | Floor price ₹766.10, a 6.34% discount to the prior close; arranger Citi; shares fell about 4% on the day |
| 19 Aug 2026 | Bulk-deal record | 5.81 crore shares, 6.66%, average ₹766.17, ₹4,451.45 Cr |
| 2 Sep 2026 | Moopen purchase | Union (Mauritius) Holdings buys 46.09 lakh shares at ₹760 from Centella, about ₹350.3 Cr |
| Calculation (Rupeia) | Result |
|---|---|
| Block value check | 5.81 crore × ₹766.17 = ₹4,451 Cr; 6.24 crore × ₹766 = ₹4,780 Cr, so the two reports describe two different share counts |
| Prior close implied by the floor price | ₹766.10 ÷ (1 − 6.34%) ≈ ₹818 |
| Block as share of the company | 5.81 ÷ 87.17 = 6.67% |
| Moopen purchase value | 46.09 lakh × ₹760 = ₹350.3 Cr, matching Angel One |
| Price paid by the family against the block | ₹760 ÷ ₹766.17 − 1 = −0.8% |
| RUPEIA READ The family bought at ₹760, slightly below the block price, and took the shares directly from the seller two weeks later. That is a supportive signal from the promoter, but it is small: about ₹350 crore against a block of about ₹4,450 crore. PTI via HDFC Sky does name four buyers of the block, which together took about 3.4% of the company, about half of the block; the earlier search suggestion that two mutual funds and two foreign firms bought 3.42% was not confirmed by a source and is not used here. |
|---|
4 THE BUSINESS: FY26 AND Q1 FY27
| Measure | Value | Basis |
|---|---|---|
| FY26 revenue | ₹9,273 Cr (+14%) | Pro forma, Aster plus QCIL |
| FY26 operating EBITDA | ₹2,013 Cr (+21%) | Pro forma |
| Q1 FY27 revenue | ₹2,597 Cr (+20%) | Pro forma |
| Q1 FY27 operating EBITDA | ₹576 Cr (+30%), margin 22.2%, up 170 bps | Pro forma |
| Occupancy, Q1 FY27 | About 64%, up 510 bps | Blended |
| Beds, Q1 FY27 | 10,559 operational; 10,898 capacity | Pro forma |
| Pre-merger Aster, FY26 | Revenue ₹4,643 Cr (+12%); EBITDA ₹947 Cr (20.4%); PAT ₹464 Cr (₹427.1 Cr in another report) | Standalone |
| Pre-merger Aster operations | 20 hospitals, 5,449 beds, 16 cities, 5 states; occupancy 61%; ALOS 3.1 days; ARPOB ₹51,800 | March 2026 |
| Revenue per in-patient, Q1 FY27 | Aster ₹1,30,352 (+10%); QCIL ₹1,44,064 (+9%) | Company |
| Calculation (Rupeia) | Result |
|---|---|
| FY26 pro forma EBITDA margin | ₹2,013 Cr ÷ ₹9,273 Cr = 21.7% |
| Annualised Q1 FY27 revenue and EBITDA | ₹2,597 Cr × 4 = ₹10,388 Cr; ₹576 Cr × 4 = ₹2,304 Cr |
| Operational beds as share of capacity | 10,559 ÷ 10,898 = 96.9% |
| Market value ÷ annualised Q1 revenue | ₹66,770 Cr ÷ ₹10,388 Cr = 6.4x (market value, not enterprise value; debt not in sources read) |
| Pre-merger Aster share of the pro forma FY26 revenue | ₹4,643 Cr ÷ ₹9,273 Cr = 50% |
Standalone Aster Q1 FY27 revenue was ₹1,311 Cr (+22%) with EBITDA of ₹277 Cr (₹264 Cr and ₹279 Cr in other reports). Reported profit after tax fell about 81% to about ₹16 Cr, while a normalised figure excluding a one-off Kasaragod item was up 46% to about ₹131 Cr. The sources read do not explain the Kasaragod item.
| RUPEIA READ Margins improved and occupancy rose five points in one quarter, which is what a listed investor wants from a combined group. Occupancy of about 64% is slightly above ICRA's sample of 63.5% for FY26. The reported profit swing is large enough that the Kasaragod item should be understood before the quarterly profit is quoted. |
|---|
5 WHO OWNED WHAT: THE INVESTOR PATH
| Investor | Event | Detail |
|---|---|---|
| Olympus Capital Asia | Entry | About US$100m invested in January 2012 (AVCJ) |
| Aster DM Healthcare | IPO | February 2018, price band ₹180–190 |
| Olympus Capital | Sale, 27 Mar 2024 | 9.8% for about ₹1,978 Cr at about ₹405–407 a share |
| Olympus Capital | Sale, 21 Jun 2024 | 9% for about ₹1,530 Cr in two tranches; holding reported falling to 1.1% |
| Moopen family | 2023 purchase | Stake raised from 37.88% to 41.88% for AED 207m (about ₹460 Cr); this was before the merger |
| Centella (TPG) | Merger and sell-down, 2026 | Receives 9.90%, sells about 6.7%, then sells 0.57% to the family |
No source read gives TPG's entry valuation, MOIC or IRR, or Olympus's overall return. They are not estimated here. The per-share prices before and after the merger are not comparable, because the merger changed the share count and the business.
6 SECTOR CONTEXT AND THE YATHARTH LINK
| Fact | Detail | Source |
|---|---|---|
| ICRA sample of 11 listed hospital companies | FY26 occupancy 63.5%; FY27 expected 62–64%; FY26 ARPOB up 9.2%; FY27 revenue growth 13–15%; outlook Positive | ICRA via Business Today, July 2026 |
| Beds per 1,000 people | India 1.3 against a global median of 2.9 | Cited in Business Today |
| Manipal ARPOB | ₹68,958 in FY26 against ₹58,865 three years earlier | Business Today |
| Advent and Aster | Reported in talks about a controlling stake in Yatharth Hospital; no deal confirmed | Angel One, 28 Aug 2026 |
| RUPEIA READ Report 28 covers Advent International's agreed ₹3,150 crore investment in Yatharth Hospital. The reported interest of Aster in the same asset shows how crowded the Indian hospital-consolidation field has become, and Aster's stated preference for a cash deal means a further purchase would draw on its balance sheet. |
|---|
7 RISKS, SCENARIOS AND CHECKLIST
| Risk | Evidence | Severity | Kill condition |
|---|---|---|---|
| Residual overhang | Centella holds 3.24% after a 60-day lock-in | MEDIUM | A further block at a deeper discount |
| Integration | Two large hospital networks combined in 2026 | MEDIUM | Margin gains reverse |
| Disclosure gaps | Block size, the other half of the buyers and Q1 ARPOB are unconfirmed | MEDIUM | Exchange filings show a different picture |
| Profit volatility | Reported Q1 profit −81% against normalised +46% | MEDIUM | Further one-offs |
| Title and governance changes | Titles for Azad and Alisha Moopen differ across sources | LOW | Unclear succession |
| Capex and acquisitions | Possible Yatharth bid; new beds being added | MEDIUM | Leverage rises |
| Scenario | What happens | Outcome |
|---|---|---|
| Bull | Occupancy and ARPOB rise; margins stay above 22% | Rerating supported |
| Base | Growth near 13–15% sector pace; overhang absorbed | Steady performance |
| Bear | Integration slips and a further block weighs on the price | Weaker share price |
| Investor class | Fit | Why |
|---|---|---|
| Long-term listed-market investor | PARTIAL | Strong growth, but merger and disclosure gaps |
| Income investor | LOW | Growth capex and acquisitions take priority |
| Short-term trader | WATCH | Events: Centella lock-in expiry and any Yatharth news |
Rupeia does not recommend buying or selling any security and is not a SEBI-registered investment adviser or research analyst. The open items are the remaining block buyers, the TPG return and the Kasaragod item.
8 KEY TERMS USED IN THIS REPORT
The terms below are used in this report. Each is explained in plain words.
| Term | Meaning |
|---|---|
| Block deal | A single large trade of shares, usually done at a small discount to the market price. |
| Pro forma | Results shown as though a merger had been in place for the whole period. |
| ARPOB | Average revenue per occupied bed per day. |
| ALOS | Average length of stay in days. |
| MOIC and IRR | Money multiple and annual return of an investment. |
| NCLT | National Company Law Tribunal, which sanctions mergers. |
Frequently asked questions
What is Aster DM Quality Care?
It is the listed hospital group formed when Aster DM Healthcare merged with Quality Care India. NCLT sanctioned the merger on 19 June 2026.
What did TPG's Centella sell?
Bulk-deal data show 5.81 crore shares, 6.66%, at an average ₹766.17, worth ₹4,451.45 crore. Business Today reported a larger block of 6.24 crore shares, 7.2%.
Who bought the shares?
PTI via HDFC Sky names HDFC Mutual Fund, Kotak Mahindra Mutual Fund, Citigroup Global Markets Singapore and Integrated Core Strategies Asia as buyers of about 3.4% of the company, roughly half of the block. The other buyers were not named.
What did the Moopen family do?
On 2 September 2026 the family's Union (Mauritius) Holdings bought 46.09 lakh shares, about 0.57%, from Centella at ₹760, about ₹350 crore.
How large is the combined group?
Pro forma FY26 revenue was ₹9,273 crore and operating EBITDA ₹2,013 crore, with 10,559 operational beds.
What does Centella still hold?
About 3.24% on the bulk-deal figures, or 2.74% on the larger block, subject to a 60-day lock-in.
Source log
Business Today: Aster DM shares, why this stock fell 4% today (block deal)
InvestyWise: Aster DM Healthcare, Centella Mauritius Holdings stake to 9.90% post-acquisition
HDFC Sky: TPG pares 6.66 pc stake in Aster DM Quality Care for ₹4,451 crore
Venture Intelligence: TPG sells 6.66% stake in Aster DM Quality Care
Angel One: Moopen family buys additional 0.57% stake worth ₹350 crore
Tribune India/PTI: Aster DM Quality Care Q1 FY27 revenue up 20% to ₹2,597 Cr
ScanX: Aster DM FY26 revenue rises 12% to ₹4,643 crore
Business Standard: Olympus Capital divests 9.8% stake in Aster DM Healthcare
Aster DM Healthcare: Leadership
Angel One: Advent International in reported talks for controlling stake in Yatharth Hospital
Business Today: What is fuelling India's healthcare sector growth
| DISCLAIMER This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing. |
|---|