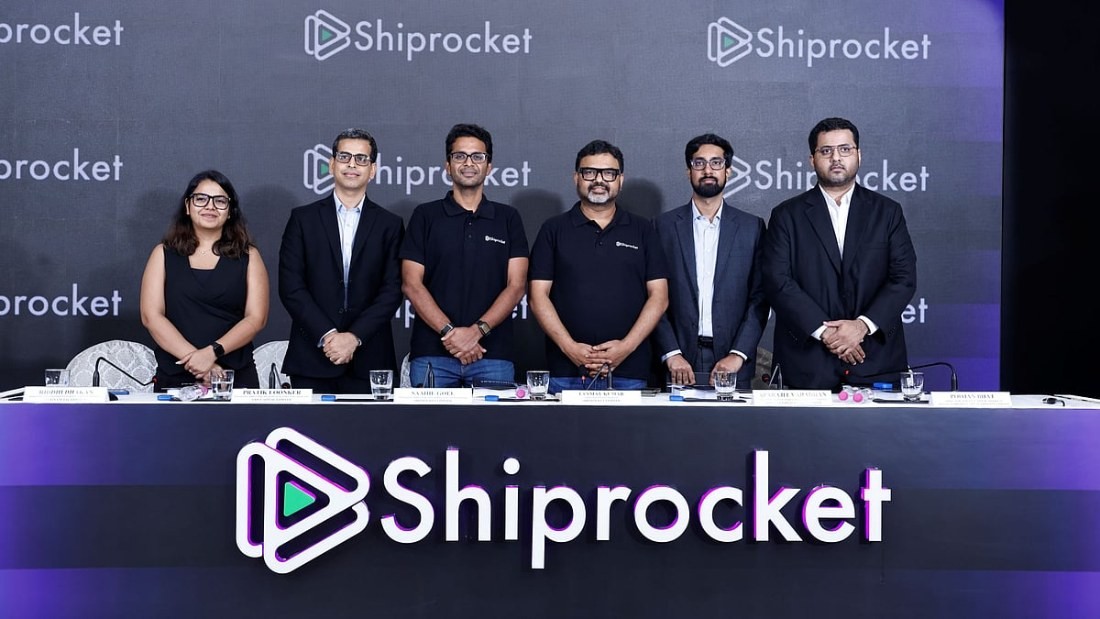
Shiprocket's leadership team at a press event · Image: Free Press Journal
Independent report content
COMPANY
Shiprocket Ltd, e-commerce logistics and enablement platform that connects sellers to courier partners and sells seller tools · MD and CEO Saahil Goel
IPO
Final size ₹1,617.48 Cr: fresh ₹885.50 Cr and offer for sale ₹731.98 Cr · price band ₹92–97, priced at ₹97 · bidding 12–14 Aug 2026 · subscribed 99.38x on NSE data
UPDATED DRHP
Dec 2025: ₹2,342 Cr (fresh ₹1,100 Cr, OFS ₹1,242.3 Cr), so the final issue was about 31% smaller
LISTING
19 Aug 2026: NSE ₹131 open (+35.05%); BSE ₹129.50
FY26
Revenue about ₹2,024 Cr (+24%) · net loss ₹79.25 Cr (3.9% of revenue) · operating cash flow +₹52.6 Cr
Q2 FY27 (TO 30 SEP 2026)
Consolidated net profit ₹59 lakh against a loss of ₹20.3 Cr a year earlier · revenue about ₹673.6 Cr (+35%) · adjusted EBITDA about ₹14.2 Cr
The research brief said IPO plans were pending; the IPO had already priced and listed
THE ACCESS POINT
Shiprocket is listed on NSE and BSE and can be bought in the market.
Executive decision summary
THE BOTTOM LINE
Shiprocket is no longer a private company. It priced a ₹1,617.48 crore IPO at ₹97 in August 2026, 31% smaller than the ₹2,342 crore planned in December 2025, and listed on 19 August at ₹131 on NSE, a 35% gain on day one. The business routes sellers' parcels through many courier partners and sells software to them. FY26 revenue was about ₹2,024 crore with a net loss of ₹79.25 crore. The two parts differ sharply: the core business earned an adjusted EBITDA margin of 12.56% while an emerging-business unit lost about ₹169 crore. For the quarter to 30 September 2026 the company reported a net profit of ₹59 lakh on revenue of about ₹673.6 crore, but one source shows operating profit still negative, so the profit is probably not from core operations. The only source found for the quarter is a single news report.
WHICH INVESTOR
Shiprocket fits a listed-equity watch-list IF you want an asset-light logistics platform and accept thin margins and a young profit record.
Wait IF you need the exchange filing for the quarter, the post-listing share price or evidence that the emerging-business losses are shrinking.
COMFORT FIT
Aggregator = a platform that gives sellers one dashboard to ship with many courier companies.
Core versus emerging business = the established shipping software and services, versus newer lines that lose money.
Adjusted EBITDA = a company-defined operating profit measure; it is not the same as net profit.
Fresh issue versus OFS = new shares for the company, versus existing holders selling.
THE RUPEIA NUMBER
₹59 lakh. The Q2 FY27 consolidated net profit, which is about 0.09% of the quarter's revenue and not clearly from core operations.
1 CLAIM REGISTER: EVIDENCE GRADING
Claim
Source
Grade
Rupeia assessment
IPO ₹1,617.48 Cr (fresh ₹885.50 Cr, OFS ₹731.98 Cr); listed 19 Aug 2026 at ₹131
Free Press Journal; search summaries
B
Established
Updated DRHP of Dec 2025: ₹2,342 Cr
Entrackr; Business Today (search only)
C
Established; reason for the cut not given
FY26 revenue ₹2,024 Cr; loss ₹79.25 Cr
Substack and aggregator reviews of the prospectus
C
Secondary; not from a filing opened here
Q2 FY27 net profit ₹59 lakh
Sahi; YourStory and Univest (search only)
D
Single source; no exchange filing found
Pre-IPO holders: Bertelsmann 21.32%, Tribe 14.14%
Inc42 (UDRHP)
C
Established
GMV (US$2.5bn or US$4bn) and merchants
Various
D
Conflict; unverified
2 THE IPO: SIZE, PRICE AND LISTING
Saahil Goel, co-founder and CEO of Shiprocket · Image: Inc42
Item
Detail
Confidential pre-filing
Public notice 21 May 2025; expected size ₹2,000–2,500 Cr; managers Axis Capital, Kotak Mahindra Capital, JM Financial, BofA Securities
Updated DRHP
12 Dec 2025: fresh issue up to ₹1,100 Cr, OFS ₹1,242.3 Cr, total ₹2,342 Cr
Final issue
₹1,617.48 Cr: fresh ₹885.50 Cr, OFS ₹731.98 Cr
Price band and dates
₹92–97; priced at ₹97; bidding 12–14 Aug 2026
Subscription
99.38x overall on NSE data (102.28x in another report); QIB about 123–125x, retail about 46–48x
Listing, 19 Aug 2026
NSE ₹131 open (+35.05%); BSE ₹129.50; FPJ reported a gain of ₹5,236 per lot
Post-issue price and market value
Not found
Calculation (Rupeia)
Result
Fresh plus OFS
₹885.50 Cr + ₹731.98 Cr = ₹1,617.48 Cr
Final size against the December draft
₹1,617.48 Cr ÷ ₹2,342 Cr = 69%, a cut of 31%
Cut by part
Fresh issue −19.5% (₹1,100 Cr to ₹885.5 Cr); OFS −41% (₹1,242.3 Cr to ₹731.98 Cr)
Lot size implied by the per-lot gain
₹5,236 ÷ (₹131 − ₹97 = ₹34) = 154 shares; cost per lot at ₹97 is ₹14,938
BSE listing gain
₹129.50 ÷ ₹97 − 1 = 33.5%
RUPEIA READ
The company cut the offer by almost a third before pricing, mainly by reducing the share sale by existing holders, and then drew nearly 100 times subscription at the final size. That pattern means investors were asked to buy a smaller, more tightly priced issue, and the 35% listing gain shows demand outran supply on day one. No source read gives the share price after the first day.
3 THE NUMBERS: FY26 AND THE FIRST TWO QUARTERS OF FY27
₹ Cr
FY25
FY26
Q1 FY27
Q2 FY27
Revenue from operations
About 1,630 (implied)
About 2,024 (+24%)
592.09 (+33.8%)
About 673.6 (+35%)
Net profit or loss
−74.45
−79.25
−13.7
+0.59
Year-earlier comparison
−18
−20.3
Adjusted EBITDA
Not found
Core 12.56% margin; emerging about −169
Not found
About 14.2 (against 4.3)
Operating cash flow
+1.9
+52.6
Not found
Not found
Calculation (Rupeia)
Result
Loss as share of revenue
FY25 4.6%; FY26 3.9%
Loss growth FY25 to FY26
₹79.25 Cr ÷ ₹74.45 Cr − 1 = 6.4% (revenue +24%)
Core and emerging revenue
₹1,485 Cr (73%) and ₹539 Cr (27%), adding to ₹2,024 Cr
Core adjusted EBITDA
12.56% × ₹1,485 Cr ≈ ₹186.5 Cr
Core plus emerging
₹186.5 Cr − ₹169 Cr ≈ ₹17.5 Cr, about 0.9% of revenue (indicative; definitions may differ)
Q2 profit as share of revenue
₹0.59 Cr ÷ ₹673.6 Cr = 0.09%
First-half FY27 revenue annualised
(₹592.09 Cr + ₹673.6 Cr) × 2 ≈ ₹2,531 Cr
Univest shows operating profit still negative at about ₹2.62 crore in Q2 FY27, and an Investywise piece printed the profit as ₹6 crore in a headline and ₹6 million in the body. The profit therefore appears to come from non-operating items or an adjusted measure. The company also repaid all borrowings from IPO proceeds, which removes interest cost.
RUPEIA READ
The loss has narrowed in rupees and fallen as a share of revenue, and the quarter has reached break-even at the net level. The part that matters is what is underneath: a core business that makes money and an emerging business that loses nearly as much as the core earns. Break-even depends on the emerging unit shrinking its loss, and a reviewer cited in the research said the absolute loss was not narrowing.
4 SHAREHOLDERS, PEOPLE AND FUNDING HISTORY
Person or holder
Detail
Source
Saahil Goel
Managing Director and CEO, co-founder; stake 4.84% before the IPO
Inc42 (UDRHP)
Gautam Kapoor
Executive Director and COO, co-founder; 4.84%
Inc42
Vishesh Khurana
Co-founder; 1.01%
Inc42
Akshay Ghulati
Co-founder; CEO of international shipping
Inc42; YourStory 2020
Bertelsmann
21.32% before the IPO
Inc42
Tribe
14.14% before the IPO
Inc42
Funding history
Series E Dec 2021 US$185m (Zomato, Temasek, Lightrock), about US$930m post-money; Aug 2022 about US$32–33.5m at about US$1.2–1.3bn; Dec 2024 round reported at about US$1.2bn with size and lead disputed
Search summaries
Calculation (Rupeia)
Result
Three founders named above
4.84% + 4.84% + 1.01% = 10.69%
Two financial holders
21.32% + 14.14% = 35.46%
Series E post-money against the 2022 value
US$1.2–1.3bn ÷ US$0.93bn = 1.3x to 1.4x in eight months
RUPEIA READ
Founders held about 11% before the IPO and two financial investors held about 35%, so professional investors were the biggest owners. The spelling "Kapur" in the brief is "Kapoor" in the sources. Total funding raised ranges from US$260 million to US$336 million across trackers, which are not company figures.
5 THE MODEL AND THE COMPETITION
Item
Detail
Source quality
Model
Sellers reach carriers such as Delhivery, Blue Dart, Ecom Express, XpressBees, Shadowfax and FedEx through one dashboard; Shiprocket owns little carrier capacity
Search summaries
Scale claims
About US$4bn annual GMV and 250,000 merchants in one source; more than US$2.5bn GMV and 2.5 lakh sellers in another; shipment counts conflict
Unverified
Rivals
Delhivery (launched Delhivery One for small businesses, per one source); Shadowfax and Ecom Express are both partners and rivals; Shipkaro in software
RUPEIA READ
An aggregator earns a margin between what sellers pay and what couriers charge, which keeps capital needs low but leaves little room if couriers sell directly to sellers. The Delhivery push into small-business shipping is the clearest competitive threat named in the sources. Reported scale figures differ by about 60% between sources and cannot be used without a filing.
6 RISKS, SCENARIOS AND CHECKLIST
Risk
Evidence
Severity
Kill condition
Profit quality
Q2 profit ₹59 lakh while operating profit is negative
HIGH
Break-even proves one-off
Emerging-business losses
About −₹169 Cr adjusted EBITDA in FY26
HIGH
Losses stop narrowing
Competition
Delhivery and courier direct sales
MEDIUM
Sellers bypass aggregators
Receivables
Receivables reportedly grew faster than revenue (one analyst)
MEDIUM
Working capital strains
Shareholder supply
Bertelsmann and Tribe hold about 35%
MEDIUM
Lock-in expiries add shares
Evidence quality
Q2 figures from one report; GMV conflicts
MEDIUM
Exchange filing differs
Scenario
What happens
Outcome
Bull
Emerging unit loss shrinks; core margin holds above 12%
Operating profit becomes visible
Base
Revenue grows 25–30% with thin profit
Valuation tracks growth
Bear
Competition squeezes core and emerging losses persist
Back to net loss
Investor class
Fit
Why
Long-term listed-market investor
PARTIAL
Growing and now debt-free, but profit is thin
Short-term trader
WATCH
Lock-in dates and quarterly results
Logistics sector researcher
FIT
Clear example of an asset-light aggregator
Rupeia does not recommend buying or selling any security and is not a SEBI-registered investment adviser or research analyst. Open items are the exchange filing for Q2, the current share price and the trend in emerging-business losses.
7 KEY TERMS USED IN THIS REPORT
The terms below are used in this report. Each is explained in plain words.
Term
Meaning
Aggregator
A platform that gives users one place to buy a service from many providers.
GMV
Gross merchandise value: the total value of goods moving through a platform.
Adjusted EBITDA
A company-defined operating profit measure before interest, tax and depreciation.
Fresh issue and OFS
New shares for the company, versus existing holders selling.
Lot
The minimum number of shares a retail investor can bid for in an IPO.
Lock-in
A period after listing in which certain holders cannot sell.
Frequently asked questions
Has Shiprocket listed?
Yes. It listed on NSE on 19 August 2026 at ₹131 against an issue price of ₹97, a gain of about 35% on day one.
How big was the IPO?
₹1,617.48 crore: a fresh issue of ₹885.50 crore and an offer for sale of ₹731.98 crore. The December 2025 draft had been ₹2,342 crore.
What did Shiprocket earn in FY26?
Revenue of about ₹2,024 crore, up 24%, with a net loss of ₹79.25 crore.
Is Shiprocket profitable now?
A single report says it made a consolidated net profit of ₹59 lakh in the quarter to 30 September 2026, but operating profit was still negative in one source.
Who owns Shiprocket?
Before the IPO, Bertelsmann held 21.32%, Tribe 14.14%, and co-founders Saahil Goel and Gautam Kapoor 4.84% each.
What does Shiprocket do?
It lets online sellers ship through many courier partners from one dashboard and sells them software for checkout, returns and advertising.
Source log
Free Press Journal: Shiprocket shares list at 35% premium over IPO price
Inc42: Shiprocket DRHP, a look at shareholding pattern and key executives
Sahi: Shiprocket posts Q2 consolidated net profit of ₹59 lakh versus ₹20.3 crore loss
Angel One: Logistics firm Shiprocket secretly files draft papers for IPO with SEBI
Entrackr: Shiprocket files updated DRHP to raise ₹1,100 Cr via fresh issue
Kotak Neo: Shiprocket Q1 FY27 results, net loss narrows, revenue rises 34%
Univest: Shiprocket Q2 results FY27
DISCLAIMER
This document is published strictly for informational, educational and academic record-keeping purposes. The publisher is not a SEBI Registered Investment Adviser (RIA) or Research Analyst (RA). It does not constitute personal investment advice, a financial recommendation, or an offer or solicitation to buy, sell or subscribe to any securities. Investments in the securities market are subject to market risks. Read all related documents carefully before investing.