GNI Infrastructure: 9 months FY26 profit ₹49.7 crore
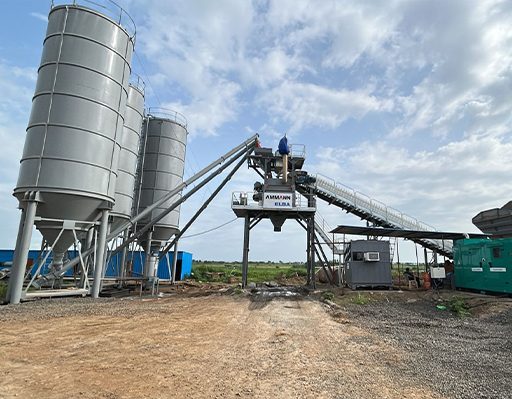
A concrete batching plant of GNI Infrastructure Source: GNI Infrastructure website
Independent report content
| OFFER | Book-built: fresh issue up to 2,10,29,642 shares + OFS of up to 93,88,212 shares = 3,04,17,854 shares; face value ₹10; ₹ size not published (no price band) |
|---|---|
| STATUS | DRHP 30 Jun 2026 (one tracker says 15 Jul) · SEBI observations 30 Oct 2026, valid 12 months |
| LEAD MANAGERS | SMC Capitals and Marwadi Chandarana Intermediaries Brokers; registrar KFin Technologies |
| FY25 | Total income ₹338.37 crore (+60.3%) · EBITDA ₹108.64 crore · profit ₹76.12 crore |
| 9 MONTHS TO 31 DEC 2025 | Total income ₹250.15 crore · EBITDA ₹87.64 crore · profit ₹49.66 crore · net worth ₹436.09 crore · borrowings ₹263.24 crore |
| ORDER BOOK (31 DEC 2025) | ₹1,021.03 crore; 99.88% in Maharashtra · 18 projects under execution (17 road + 1 environmental) |
| CONCENTRATION | Government clients 98.37% of revenue from operations; top five clients 87.02% (9M to Dec 2025) |
| USE OF FRESH ISSUE | Working capital ₹155.33 crore; balance general purposes |
| THE ACCESS POINT GNI Infrastructure is unlisted with SEBI observations dated 30 October 2026, valid 12 months. No price band or dates have been announced. |
|---|
Executive decision summary
| THE BOTTOM LINE GNI Infrastructure builds roads and highways, almost entirely for government bodies in Maharashtra, and has a second line in solid-waste biomining. It has completed over 50 road projects in five years and had an order book of ₹1,021 crore at 31 December 2025, three times FY25 income. Margins are high for a contractor (EBITDA 32–35% of total income) and profit was ₹76 crore in FY25, but income swung from ₹323 crore (FY23) to ₹211 crore (FY24) to ₹338 crore (FY25), and 98% of revenue is from government clients with 87% from the top five. Borrowings are ₹263 crore against net worth of ₹436 crore. The offer is three-quarters new shares and one-quarter promoter sale, and the public summaries give no price. Investors have to work from NAV, earnings and the order book to judge any band. |
|---|
| WHICH INVESTOR Fits you IF you want a profitable regional road contractor with a visible order book and promoters who keep about 69% after the issue. Look elsewhere IF you want diversification: nearly all revenue is government work in one state, with five clients dominating. |
|---|
| COMFORT FIT GNI = a regional road builder whose customers are state and central government bodies. HAM = hybrid annuity model: the government pays part during construction and the rest over time; GNI executes some through a subsidiary. Biomining = clearing old landfill waste, the company's second line. |
|---|
| THE RUPEIA NUMBER 87.02%. The share of revenue from operations contributed by the top five clients in the nine months to December 2025. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
A = government or regulator record. B = statutory filing. C = independent press. D = company announcement.
| Claim | Source | Grade | Rupeia assessment |
|---|---|---|---|
| Fresh issue up to 2,10,29,642 shares; OFS up to 93,88,212 shares; total 3,04,17,854; pre-issue 9,99,70,358; post-issue 12,10,00,000 | Chittorgarh; Bajaj Broking | A/B | Arithmetic ties; ₹ amounts not published. |
| SEBI observations 30 Oct 2026, valid 12 months | Chittorgarh; Groww; Investmentguru | B | Established. |
| DRHP 30 Jun 2026 (Bajaj, Kotak Neo, BSE file name) or 15 Jul (Chittorgarh) | As listed | B/C | Conflict. |
| FY23 / FY24 / FY25 total income ₹323.48 / 211.03 / 338.37 crore; EBITDA ₹110.41 / 63.58 / 108.64 crore; profit ₹75.41 / 46.96 / 76.12 crore | Chittorgarh; Bajaj Broking | B | FY26 full year not found. |
| 9M Dec 2025 total income ₹250.15 crore; EBITDA ₹87.64 crore; profit ₹49.66 crore; net worth ₹436.09 crore; borrowings ₹263.24 crore | Chittorgarh | B | Established. |
| Order book ₹1,021.03 crore (31 Dec 2025); 99.88% in Maharashtra | Bajaj Broking; Business Today | B | Established. |
| Government clients 98.37%; top five 87.02%; contingent liabilities ₹228.86 crore | Bajaj Broking (DRHP) | B | Established. |
| Objects: working capital ₹155.33 crore | Chittorgarh; Bajaj Broking | B | GCP balance not shown. |
| A Groww table of 417.23/271.68/247.52 income and 95.71/46.64/15.09 profit was excluded | Groww (not read) | D | Does not match GNI; resembles another company in the same article. |
2 COMPANY OVERVIEW & FOUNDING STORY
GNI Infrastructure traces its roots to a partnership, Gurunanak Industries (deed of 25 November 1980), became GNI Infrastructure Private Limited on 22 August 2007 and converted to a public company in October 2023. It is based in Chhatrapati Sambhajinagar (Aurangabad), Maharashtra, although one report calls it Mumbai-based. Five Bindra family members are promoters and hold 92.73% before the IPO.
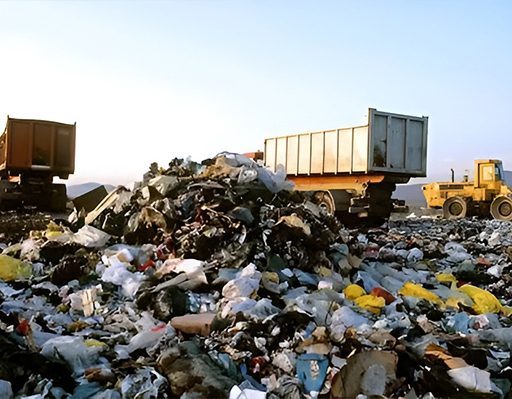
Its main business is road construction, widening, upgrading and maintenance, via EPC, item-rate and HAM contracts, the last through a consolidated subsidiary, MCGN Roadways LLP, and project JVs. Its second business is solid-waste biomining of legacy landfill. As of 31 December 2025 it had completed over 50 road projects in five years (over 400 km), and had 18 projects under execution (over 345 km).
The largest cited contract was ₹291.62 crore (Beed bypass road, completed in fiscal 2024). It had 670 permanent employees at 31 March 2026 and a fleet of batching and asphalt plants, crushers and road-building equipment. Road work was 87.6% of revenue from operations at December 2025.
3 TIMELINE
| Date | Event |
|---|---|
| 1980 | Partnership firm Gurunanak Industries |
| 22 Aug 2007 | Becomes GNI Infrastructure Private Limited |
| 25 Oct 2023 | Converts to a public limited company |
| FY24 | Total income ₹211.0 crore (−34.8%); profit ₹47.0 crore |
| FY25 | Total income ₹338.4 crore (+60.3%); profit ₹76.1 crore |
| 31 Dec 2025 | Order book ₹1,021 crore; net worth ₹436.1 crore |
| 30 Jun 2026 | DRHP filed |
| 30 Oct 2026 | SEBI observations received |
4 OFFER STRUCTURE, SELLERS AND PRE-ISSUE CAPITAL
| Item | Detail | Figure | Comment |
|---|---|---|---|
| Fresh issue | New shares | Up to 2,10,29,642 shares | 17.4% of 12.10 crore post-issue shares |
| Offer for sale | Eight sellers | Up to 93,88,212 shares | Five promoters, one promoter-group member and two corporates |
| Total | Offer | 3,04,17,854 shares | ₹ size not published |
| Pre-issue / post-issue shares | Equity | 9,99,70,358 / 12,10,00,000 | Ties arithmetically |
| Promoter holding | Before / after (Rupeia) | 92.73% / ~69.1% | After selling 90.85 lakh shares and fresh issue to the public |
| Object 1 | Working capital | ₹155.33 crore | Balance for general purposes |
| Reservation | Net offer | QIB ≤50%, NII ≥15%, retail ≥35% | — |
Largest sellers: Ravindersingh Khushbirsingh Bindra (31,96,918 shares), Narindersingh Basantsingh Bindra (14,97,001), Harvindersingh Basantsingh Bindra (14,98,920), Harpreetsingh H Bindra (14,05,239) and Prabjyotsingh Harvindersingh Bindra (14,05,239); Chanakya Opportunities Fund I sells 1,81,754 and RPV Holdings 1,21,169. Promoters sell 90.85 lakh of the 93.88 lakh shares.
| RUPEIA CALCULATION Price illustration. Annualising nine-month profit of ₹49.66 crore gives about ₹66.2 crore and EPS of about ₹6.62 on 9.997 crore shares. At 15x, 20x and 25x that EPS, the price would be about ₹99, ₹132 and ₹166, the post-issue market value about ₹1,200 crore, ₹1,600 crore and ₹2,000 crore, the fresh issue about ₹209 crore, ₹278 crore and ₹348 crore, and the OFS about ₹93 crore, ₹124 crore and ₹155 crore. A fresh issue of ₹209–348 crore against a working-capital object of ₹155.33 crore leaves ₹54–193 crore for general purposes. The price band is not published; these are Rupeia illustrations. |
|---|
5 FINANCIAL FORENSICS: HIGH MARGINS, LUMPY INCOME
| ₹ crore (restated consolidated) | FY23 | FY24 | FY25 | 9M to Dec 2025 |
|---|---|---|---|---|
| Total income | 323.48 | 211.03 | 338.37 | 250.15 |
| Growth | — | −34.8% | +60.3% | 74% of FY25 in 9 months |
| EBITDA | 110.41 | 63.58 | 108.64 | 87.64 |
| EBITDA margin on total income | 34.1% | 30.1% | 32.1% | 35.0% |
| Net profit | 75.41 | 46.96 | 76.12 | 49.66 |
| PAT margin on total income | 23.3% | 22.3% | 22.5% | 19.9% |
| Net worth | 202.63 | 249.73 | 386.19 | 436.09 |
| Borrowings | 152.92 | 182.96 | 235.01 | 263.24 |
| Borrowings ÷ net worth (Rupeia) | 0.75 | 0.73 | 0.61 | 0.60 |
| Total assets | 383.29 | 469.85 | 687.03 | 796.80 |
Income fell by a third in FY24 and rebounded 60% in FY25: a typical profile for a contractor whose revenue follows project milestones. Net worth has risen more than profits, and a ₹95.7 crore jump in share capital at December 2025 alongside a ₹45.8 crore fall in reserves suggests a bonus issue that moved reserves into share capital (Rupeia inference; the sources do not say). Borrowings grew steadily to ₹263 crore.
| RUPEIA CALCULATION Order-book cover. ₹1,021 crore is 3.0 times FY25 total income (1,021 ÷ 338) and about 3.1 times annualised nine-month income of ₹333.5 crore. That is three years of work at current run-rate, long for an EPC contractor, but 99.88% of it is in Maharashtra and the clients are government bodies, so payment timing and state budgets matter as much as the book itself. Contingent liabilities of ₹228.86 crore equal 52% of net worth (228.86 ÷ 436.09). |
|---|
6 BUSINESS MODEL & UNIT ECONOMICS
GNI earns contract revenue from building and maintaining roads for government agencies.
| Line | How it earns | Pressure point |
|---|---|---|
| Road construction (87.6% of revenue) | EPC and item-rate contracts for state and central bodies | Tender competition; payment delays |
| HAM projects (via MCGN Roadways LLP) | Government pays part during construction and the rest over time | Debt-funded; longer cash cycle |
| Solid-waste biomining (rest of revenue) | Clearing legacy landfill under municipal contracts | Small; municipal payment risk |
| Equipment fleet | Batching and asphalt plants, crushers, pavers | Capital intensity |
| Order book (₹1,021 crore) | 18 projects under execution | Concentrated in one state |
A road contractor lives on winning tenders at low enough prices to keep margins, then executing without delay. High margins here suggest efficient execution or a favourable mix; they will be tested if tender competition tightens.
7 MARKET & COMPETITIVE ANALYSIS
| Peer | Status | Position |
|---|---|---|
| Listed road and infrastructure EPC companies | Listed | Rupeia has not sourced names or multiples |
| Recently listed civil-construction IPOs | Listed | Shown on Chittorgarh, not captured |
| Large HAM and highway developers | Listed | Reference for HAM valuation |
No peer table was captured in the sources. The price band should be compared with listed regional road contractors on live earnings multiples.
8 1. INDIA AND MAHARASHTRA ROAD CONTEXT
| Metric | Figure | Source |
|---|---|---|
| India road network | ~6.7 million km (2025) | D&B via Bajaj Broking |
| National highways | 91,000 km (2014) to 146,145 km (2024) | Same; +60.6% (Rupeia: 146,145 ÷ 91,000) |
| Maharashtra road network | 328,526 km (FY2024) | Same |
| National highways in Maharashtra | 18,459 km | Same |
| GNI completed projects | Over 50 in 5 years; 400+ km | Bajaj Broking |
| GNI under execution | 18 projects; 345+ km | Chittorgarh; Bajaj Broking |
The company works in one of India's largest road networks. Government infrastructure spending is the driver; the sources do not give state-budget figures.
9 2. CONCENTRATION: CLIENTS, GEOGRAPHY AND ORDER BOOK
| Metric | Figure | Source |
|---|---|---|
| Government clients share of revenue (9M Dec 2025) | 98.37% | Bajaj Broking (DRHP) |
| Top five clients share of revenue | 87.02% | Same |
| Order book in Maharashtra | 99.88% | Same |
| Road share of revenue | 87.6% | Business Today |
| Contract size range | ₹3.74 crore to ₹291.62 crore | Bajaj Broking |
Three layers of concentration (client, state, product) coincide. A delay in payments from one or two government departments, or a state budget squeeze, would hit income directly. Client names such as PWD, MSRDC or NHAI were not in the sources.
10 3. THE BONUS-ISSUE CLUE AND PRE-IPO CAPITAL
| ₹ crore | Mar 2025 | Dec 2025 | Change |
|---|---|---|---|
| Net worth | 386.19 | 436.09 | +49.90 |
| Reserves and surplus | 363.76 | 317.95 | −45.81 |
| Implied share capital (net worth − reserves) | 22.43 | 118.14 | +95.71 |
| 9M profit added to reserves | — | 49.66 | — |
| Pre-issue shares × ₹10 face value | — | ~99.97 | Rupeia |
Rupeia derivation; the sources do not give share capital.
Reserves fell while profit was added, and share capital jumped by roughly ₹95.7 crore. The most plausible explanation is a bonus issue that capitalised reserves into 9,99,70,358 shares of ₹10. If so, EPS and NAV on the pre-issue share count are already bonus-adjusted (NAV ₹41.80 at December 2025). The RHP should confirm.
11 4. DEBT, RETURNS AND CONTINGENT LIABILITIES
| Metric | Mar 2025 | Dec 2025 |
|---|---|---|
| ROE (Chittorgarh) | 25.25% | 12.55% |
| ROCE | 20.34% | 12.59% |
| Debt / equity | 0.60 | 0.61 |
| PAT margin | 22.50% | 19.85% |
| NAV per share (₹) | 38.23 | 41.80 |
| Contingent liabilities | — | ₹228.86 crore (52% of net worth) |
Dec 2025 returns are for nine months and are not annualised on the source; annualised ROE would be about 17% (12.55% × 12 ÷ 9).
12 5. VALUATION BY EARNINGS
| Multiple of annualised EPS ₹6.62 | Price (₹) | Post-issue value (₹ crore) | Fresh issue (₹ crore) | OFS (₹ crore) |
|---|---|---|---|---|
| 15x | ~99 | ~1,200 | ~209 | ~93 |
| 20x | ~132 | ~1,602 | ~278 | ~124 |
| 25x | ~166 | ~2,003 | ~348 | ~155 |
Rupeia illustration from nine-month profit annualised ×4/3; the price band is not published. 12.10 crore post-issue shares; 2.103 crore fresh; 0.939 crore OFS.
| RUPEIA CALCULATION Rupeia calculation: at 20x annualised earnings, the price of about ₹132 compares with NAV of ₹41.80, a price-to-book of 3.2x (132 ÷ 41.8), for a business earning an ROE of 12.6% for nine months (about 17% annualised). A multiple of 20x on a 17% ROE is fair for a contractor with a strong order book; 25x would require a clean receivables record. |
|---|
13 6. GOVERNANCE AND SELLERS
Promoters: five family members, 92.73% before the IPO; about 69.1% after (Rupeia); they sell 90.85 lakh shares.
Corporate sellers: Chanakya Opportunities Fund I (1,81,754 shares) and RPV Holdings (1,21,169).
Lead managers: SMC Capitals and Marwadi Chandarana Intermediaries Brokers, both regional bankers.
Conflicts in public data: filing date 30 Jun versus 15 Jul; headquarters Sambhajinagar versus Mumbai; EBITDA margin KPIs do not equal EBITDA ÷ total income.
Not found: FY26 full-year figures, revenue from operations, peer comparison, client names, price band.
14 7. RISK MAP
| Risk | Mechanism | Where to look in the RHP |
|---|---|---|
| Government dependence (98%) | Payment delays and budget cycles | Receivable days; retention money |
| Client concentration (87%) | Loss or delay at one client | Top client names |
| Geographic concentration (99.9%) | One state's policies and budgets | Order book by state |
| Working capital intensity | Fresh issue funds ₹155 crore of working capital | Working-capital days |
| Contingent liabilities | ₹228.86 crore = 52% of net worth | Litigation note |
| Margin sustainability | EBITDA margin 32–35% is high for EPC | Cost structure; HAM mix |
| Income volatility | −35% in FY24, +60% in FY25 | Quarterly revenue |
15 8. QUESTIONS FOR THE RED HERRING PROSPECTUS
FY26 full-year financials and revenue from operations.
Client names, shares of revenue and payment terms.
Price band, final fresh-issue and OFS amounts.
Working-capital days and the balance of general corporate purposes.
Bonus issue details and the share-capital reconciliation.
Contingent liabilities and litigation.
HAM projects: equity commitments and debt.
Order-book execution schedule.
16 9. GLOSSARY
| Term | Meaning |
|---|---|
| EPC | Engineering, procurement and construction |
| HAM | Hybrid annuity model for road projects |
| Item-rate contract | Payment per unit of work done |
| Biomining | Excavating and processing old landfill waste |
| Bonus issue | Free shares issued from reserves |
| Order book | Contracts won but not yet executed |
17 VALUATION SCENARIOS
| Scenario | Post-issue value (₹ crore) | P/E on annualised FY26 | What must be true |
|---|---|---|---|
| Bear | 1,200 | 15x | Payment delays and concentration weigh |
| Base | 1,600 | 20x | Order book converts; margins hold near 33% |
| Bull | 2,000 | 25x | Clean receivables and diversified clients |
Rupeia scenarios from nine-month annualised profit; not guidance.
18 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 20% | Strong RHP; IPO at 25x+; order wins continue |
| Base | 45% | IPO near 18–20x earnings |
| Bear | 35% | Concentration or receivables concerns reduce the price |
19 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Kill condition |
|---|---|---|
| Government and client concentration | High | Top client share |
| Single-state exposure | High | Maharashtra budget |
| Income volatility | Medium | FY26 and FY27 revenue |
| Working-capital strain | Medium | Receivable days |
| Contingent liabilities | Medium | Litigation note |
| Information gaps in public summaries | Medium | RHP |
20 INVESTOR CLASS ANALYSIS
HNIs and family offices
Judge the price against NAV and the order book. Ask for FY26 audited figures and client names before accepting a premium multiple.
Institutions
Institutions will test receivables, client concentration and the state-budget exposure.
NRIs
NRIs can hold unlisted Indian shares under FEMA pricing and reporting rules; repatriation depends on the account route used.
21 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Nov 2026–Oct 2027 | RHP, price band and IPO within SEBI validity |
| FY26 results | First full-year audited figures |
| Ongoing | Order-book conversion |
22 RUPEIA FINAL INDEPENDENT VIEW
GNI is profitable with a deep order book and heavy concentration. It is a reasonable regional contractor at a fair price; a high multiple would not be supported by the diversification.
| THE RUPEIA NUMBER 87.02%. The share of revenue from operations contributed by the top five clients in the nine months to December 2025. |
|---|
| RUPEIA VERDICT Profitable but concentrated contractor. Wait for the band. |
|---|
Frequently asked questions
Has SEBI approved GNI Infrastructure's IPO?
SEBI issued observations on 30 October 2026, valid for 12 months.
How big is the offer?
3,04,17,854 shares: up to 2.10 crore fresh and 0.94 crore OFS. The rupee size depends on the price band.
What is GNI's order book?
₹1,021.03 crore at 31 December 2025, 99.88% in Maharashtra.
How concentrated is revenue?
Government clients are 98.37% and the top five clients 87.02% of revenue from operations.
Who sells?
Five promoters and a promoter-group member, plus two corporate sellers.
Source log
Chittorgarh: GNI Infrastructure IPO
Kotak Neo: GNI Infrastructure files draft IPO papers
Bajaj Broking: GNI Infrastructure IPO
Business Today: Renfra, Innoterra, GNI Infra file DRHPs
Investmentguru India: GNI Infrastructure obtains SEBI approval
Groww: GNI Infrastructure, Atomberg among four companies with SEBI nod
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|