Balwaan Krishi: ₹100 crore Series B
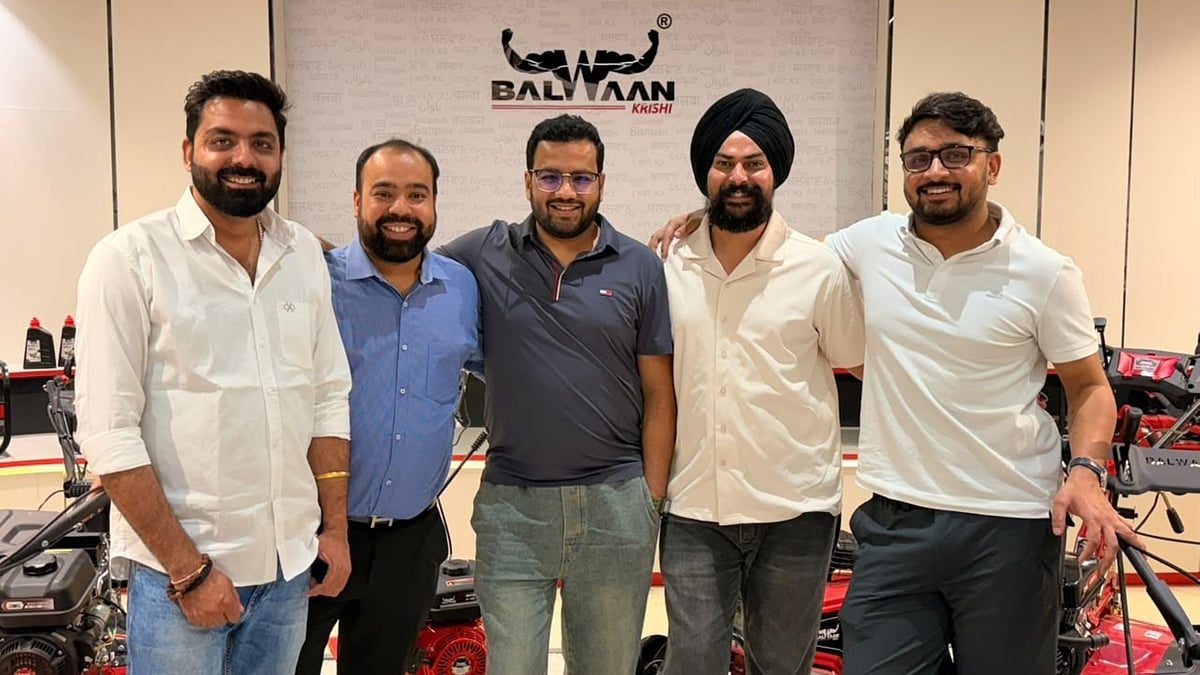
Balwaan Krishi leadership at the time of the Series B announcement Source: Outlook Business / Entrepreneur India, 28 Sep 2026
Independent report content
| ROUND | Series B · ₹100 crore (about US$10.4m) · announced 28 Sep 2026 |
|---|---|
| LEAD | First Bridge India Growth Fund Private Equity (₹70 crore per transaction counsel) |
| EARLIER ROUNDS | US$2m pre-Series A (2023); ₹40 crore Series A led by JM Financial Private Equity (June 2024) |
| VALUATION | Not disclosed |
| REVENUE | ₹87.9 crore in FY25 (Inc42 profile); later figures not published |
| OWNERSHIP | Founders held 51.6% at 31 March 2025 (Inc42 cap table) |
| USES | Own manufacturing, dealer expansion including South India, IoT and predictive-maintenance products |
| ADVISERS | Samisti Legal and Vertices Partners (company); Right Pillar Advisors |
| LEGAL ENTITY | Modish Tractoraurkisan Private Limited |
| THE ACCESS POINT Balwaan is private. First Bridge's Category II AIF led the round. Individuals can reach it only through funds that hold it or rare secondary sales. |
|---|
Executive decision summary
| THE BOTTOM LINE Balwaan Krishi sells compact farm machines such as power tillers, weeders and sprayers to small Indian farmers, through its own e-commerce and a growing dealer network. FY25 revenue of ₹87.9 crore makes it a real manufacturing business, not an app. The ₹100 crore Series B pays for factories, dealers and new products. The test is after-sales: a cheap machine that is slow to repair will not build a brand. |
|---|
| WHICH INVESTOR Fits you IF you want exposure to farm mechanisation among small-holders and accept an unlisted valuation you cannot see. Look elsewhere IF you need a listed name; Escorts Kubota, Mahindra and VST Tillers trade on exchanges. |
|---|
| COMFORT FIT Balwaan = the compact-car maker of Indian farming: affordable machines for fields too small for a tractor. Mahindra, Escorts Kubota = the tractor giants with huge dealer networks. VST Tillers = the listed pure-play on power tillers. |
|---|
| THE RUPEIA NUMBER ₹87.9 crore of FY25 revenue against ₹100 crore of new equity: the Series B is larger than a year of sales. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
| Claim | Source | Grade | Assessment |
|---|---|---|---|
| ₹100 crore Series B led by First Bridge | YourStory; Entrepreneur India; Outlook Business | C | Established. |
| First Bridge contributed ₹70 crore | Bar & Bench (transaction counsel) | C | Established. |
| ₹40 crore Series A, June 2024, JM Financial PE | Entrepreneur India; BusinessWorld | C | Established. |
| FY25 revenue ₹87.9 crore | Inc42 profile | C | Reported. |
| Founders hold 51.6% | Inc42 cap table (31 Mar 2025) | C | Before the Series B. |
2 COMPANY OVERVIEW
Modish Tractoraurkisan Private Limited trades as Balwaan Krishi. It designs and sells small-farm equipment and sells directly online as well as through dealers. The Series B is meant to fund its own factories, dealer growth in South India and connected-machine products.
3 FUNDING HISTORY
| Date | Round | Amount | Investors |
|---|---|---|---|
| 2023 | Pre-Series A | US$2m | Not itemised in coverage |
| Jun 2024 | Series A | ₹40 crore | JM Financial Private Equity (lead) |
| 28 Sep 2026 | Series B | ₹100 crore | First Bridge India Growth Fund PE (₹70 crore); others unnamed |
Total equity raised is about ₹155 crore across the rounds. A second investor in the Series B has not been named.
4 BUSINESS MODEL & UNIT ECONOMICS
Revenue comes from machine sales, with parts and service as secondary lines. The economics turn on four items, none disclosed.
| Driver | Why it matters |
|---|---|
| Dealer margin and credit | Dealers need stock and financing before the sowing season |
| Gross margin per machine | Competes with cheap imports and local fabricators |
| Parts and repair | Downtime during harvest damages the brand |
| Seasonality | Sales bunch before kharif and rabi seasons |
| RUPEIA CALCULATION At 10% net margin, FY25 revenue of ₹87.9 crore would earn about ₹8.8 crore. The company has not published its margin. |
|---|
5 MARKET & COMPETITIVE ANALYSIS
| Peer | Position |
|---|---|
| VST Tillers Tractors (listed) | Largest power-tiller maker; profitable |
| Mahindra, Escorts Kubota, TAFE | Tractors and implements with large dealer networks |
| Kirloskar, Honda and Chinese-brand imports | Engines, tillers and sprayers |
| Other agri-equipment start-ups (Farmpal, Gramophone, Kisankraft) | Rental and distribution models |
Low farm-labour supply and high labour cost are driving small-farm mechanisation. Smallholdings mean farmers buy cheap, rent often and judge on repair speed.
6 VALUATION ANALYSIS
No valuation has been published. If ₹100 crore bought 15–25% of the company, the post-money would be ₹400–670 crore, or 4.5–7.6x FY25 revenue. That is the range investors should test against any secondary offer. It is Rupeia arithmetic, not a reported figure.
7 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 25% | Revenue doubles in two years; own factory lifts margins; Series C or strategic sale |
| Base | 50% | Growth of 30–40% a year; South India dealers added |
| Bear | 25% | Monsoon shocks and dealer credit losses; service quality hurts the brand |
8 RISK ANALYSIS
| Risk | Severity | Kill condition |
|---|---|---|
| Weather and farm income | High | Two weak monsoons in a row |
| Dealer credit and working capital | High | Receivables stretch beyond a season |
| Competition from tractor majors | Medium | Majors launch cheap compact lines |
| After-sales quality | Medium | Rising warranty claims |
9 INVESTOR CLASS ANALYSIS
HNIs and family offices
Best reached through agri or growth-equity AIFs; First Bridge itself is a Category II AIF.
NRIs
FEMA rules apply to secondary purchases; the company is an Indian private limited company.
10 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Early 2027 | FY26 accounts filed |
| 2027 | New factory capacity and South India dealers |
| 2027 | IoT and predictive-maintenance launch |
| 2027–28 | Series C or strategic stake |
11 RUPEIA FINAL INDEPENDENT VIEW
Balwaan is a real manufacturer with a growing dealer network, a sensible market and a first institutional lead from a growth-equity fund. What it lacks is public margin, valuation and after-sales data. For a small-farm brand those matter more than the headline round.
| THE RUPEIA NUMBER ₹100 crore raised against ₹87.9 crore of FY25 revenue. |
|---|
| RUPEIA VERDICT A credible farm-equipment business at an undisclosed price. Suitable for patient agri-focused capital via funds. |
|---|
Frequently asked questions
How much did Balwaan Krishi raise?
₹100 crore in a Series B announced on 28 September 2026.
Who led the round?
First Bridge India Growth Fund Private Equity, which put in ₹70 crore.
What is Balwaan Krishi's revenue?
₹87.9 crore in FY25 according to Inc42.
What does Balwaan sell?
Compact farm machines such as tillers and sprayers, online and through dealers.
Can I buy Balwaan shares?
Only through funds or rare secondary sales.
Source log
YourStory: Balwaan Krishi raises ₹100 crore Series B
Entrepreneur India: Balwaan Krishi raises ₹100 crore
Outlook Business: Balwaan Krishi Series B
Bar & Bench: Samisti Legal, Vertices Partners act on the Series B
Inc42: Balwaan cap table
BusinessWorld: JM Financial PE invests in Modish Tractoraurkisan
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|