Yuma Energy: US$35m Series A
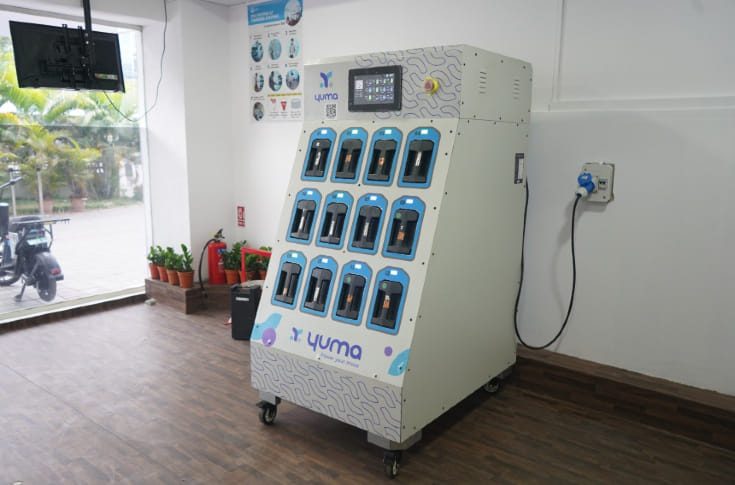
A Yuma Energy battery-swap station Source: Autocar Pro
Independent report content
| ROUND | Series A · US$35m · announced 31 Aug–1 Sep 2026 |
|---|---|
| INVESTOR | Magna International (Canadian automotive supplier), already the joint-venture parent |
| VALUATION | Not disclosed; Dealroom lists US$140m (third-party estimate) |
| NETWORK | 2,500+ charging units · 400+ locations · 17–18 cities · about 100,000 batteries · 60m+ swaps in total |
| REVENUE | About ₹100 crore for FY26 (management; one trade report) |
| PROFIT | Some older stations EBITDA-positive; company aims for EBITDA-positive overall by FY27 |
| PLANS | Roughly double the battery fleet to about 200,000; non-Yulu customers to about 25% of swaps within two years |
| DEAL | Acquired battery maker Grinntech alongside the round |
| COMPANY | Bengaluru · Yulu–Magna joint venture |
| THE ACCESS POINT Yuma is private and majority-held by its strategic parents (Magna with Yulu), so there is no open round. Exposure is possible only through funds that hold Yulu, or a rare negotiated stake. |
|---|
Executive decision summary
| THE BOTTOM LINE Yuma Energy runs battery swap stations so that delivery riders and shared-bike fleets can replace an empty pack in under two minutes. It is the infrastructure business that grew out of Yulu's bike fleet and now sells to others. Magna's US$35m raises its stake and funds more batteries, stations and cities. The network is large for India and revenue is reported near ₹100 crore, but battery packs are expensive assets and a swap network earns only if each pack is used many times a day. |
|---|
| WHICH INVESTOR Fits you IF you want exposure to Indian electric fleets and are comfortable that the parent, Yulu, is also the biggest customer. Look elsewhere IF you need an independent price or near-term profits. |
|---|
| COMFORT FIT Yuma = a petrol-pump chain for electric bikes, where the 'fuel' is a charged battery you rent per swap. Yulu = the biggest customer and co-founder: a bike-sharing fleet that needs the packs. Sun Mobility, Battery Smart = peer swap networks competing for the same fleets. |
|---|
| THE RUPEIA NUMBER 60 million swaps. At a few rupees per swap that is a business built from very small transactions, so utilisation per battery is the metric that matters. |
|---|
1 CLAIM REGISTER: EVIDENCE GRADING
A = government or regulator record. B = statutory filing. C = independent press. D = company announcement.
| Claim | Source | Grade | Assessment |
|---|---|---|---|
| US$35m Series A from Magna | TechCrunch; YourStory; Inc42; Autocar Pro | C | Established. Magna was already the JV partner. |
| 2,500+ charging units, 400+ locations, 100,000 batteries | Press coverage of announcement | D | Company claim. |
| FY26 revenue about ₹100 crore | Management to TechCrunch; Inforcapital | D | Not an audited figure. |
| Valuation US$140m | Dealroom | C | Third-party estimate. |
| Grinntech acquisition | Press coverage | C | Established; price not disclosed. |
2 COMPANY OVERVIEW
Yuma Energy was created from Yulu's battery-swap business after Magna International took a majority stake in a joint venture. It operates swap cabinets with charged lithium-ion packs for electric scooters, motorbikes and three-wheelers used by gig riders and fleets, and it lets other operators plug into the same network.
A 2026 trade report says the company launched swaps across Uttar Pradesh, including Noida, as part of its city expansion.
3 TIMELINE
| Date | Event |
|---|---|
| 2023 | Yulu and Magna form the joint venture; Magna takes a majority stake |
| 2024–26 | Network grows to 2,500+ units and 400+ locations in 17–18 cities |
| 31 Aug–1 Sep 2026 | US$35m Series A from Magna; Grinntech acquisition announced |
| FY27 target | EBITDA-positive overall |
4 FUNDING & OWNERSHIP
The Series A raises Magna's stake above the 51% it held after the joint venture was set up. Because the lead is also the parent, the round does not price the company at arm's length. No post-money valuation or cap table has been published. Dealroom's US$140m is a third-party figure.
| RUPEIA CALCULATION At Dealroom's US$140m, US$35m would be a 25% stake. That is only illustrative: Magna's actual price, share class and any debt component are not disclosed. |
|---|
5 BUSINESS MODEL & UNIT ECONOMICS
| Driver | What it means | Disclosed? |
|---|---|---|
| Swap fee | Paid per swap by rider or fleet | Price not published |
| Battery utilisation | Swaps per pack per day; the key to returns | Not published |
| Capex per pack and cabinet | Cost of packs, chargers, site | Not published |
| Battery life | Cycles before replacement; Grinntech brings in-house cells and packs | Not published |
| Anchor customer | Yulu is the largest user today | Share not published |
| RUPEIA CALCULATION ₹100 crore of revenue across 100,000 batteries is ₹10,000 of revenue per battery a year, about ₹27 a day. Whether that covers pack cost, power and site rent depends on figures the company has not published. |
|---|
6 MARKET & COMPETITIVE ANALYSIS
| Peer | Model | Note |
|---|---|---|
| Battery Smart | Swap network for e-rickshaws and two-wheelers | Larger commercial fleet focus; venture-backed |
| Sun Mobility | Swap network with Indian OEM ties | Backed by Chrysalis and others |
| Gogoro, NIO (global) | Swap networks abroad | Show the model at scale |
| Plug-in charging (Exponent Energy, Ather Grid) | Fast charge instead of swap | Alternative for the same riders |
Swapping wins where riders earn per hour and cannot wait for a charge. It loses if fast charging gets cheap and standard packs do not spread across vehicle makers.
7 VALUATION ANALYSIS
No official valuation exists. The US$140m estimate equals about ₹1,350 crore. On reported FY26 revenue of ₹100 crore that is 13.5x sales, rich for an asset-heavy business. Value rests on the Magna backing and on EBITDA turning positive in FY27.
8 SCENARIO ANALYSIS
| Scenario | Probability | What happens |
|---|---|---|
| Bull | 30% | Non-Yulu customers reach 25% of swaps; EBITDA positive in FY27; Magna extends the network abroad |
| Base | 50% | Gradual city expansion; profits arrive FY28 |
| Bear | 20% | Packs underused; cell prices or fire incidents hurt; Magna funds repeated top-ups |
9 RISK ANALYSIS: RED FLAG LEDGER & KILL CONDITIONS
| Risk | Severity | Kill condition |
|---|---|---|
| Related-party dependence on Yulu | High | Yulu above half of swaps after two years |
| Capital intensity | High | Pack and cabinet cost per swap does not fall |
| Battery safety | Medium | A fire or recall closes stations |
| Standardisation | Medium | OEMs choose other pack designs |
| Policy | Medium | Cut in FAME or state subsidies |
10 INVESTOR CLASS ANALYSIS
HNIs and family offices
No open round; look at funds holding Yulu or fleet-electrification funds.
Institutions
Strategic partners (OEMs, utilities, logistics firms) are the natural holders.
NRIs
Indian entity; FEMA rules apply to any secondary purchase.
11 THE EARLY SIGNAL: EVENTS TO WATCH
| When | Event |
|---|---|
| Early 2027 | FY26 accounts filed |
| FY27 | EBITDA-positive target |
| 2027 | Battery fleet toward 200,000; non-Yulu share of swaps |
| 2027 | Grinntech integration: in-house packs and cost |
12 RUPEIA FINAL INDEPENDENT VIEW
Yuma has real scale for India: hundreds of locations and tens of millions of swaps. It is also backed by a strategic parent willing to keep funding it. The price and the profit are not public, and customer concentration in Yulu is the risk to watch.
| THE RUPEIA NUMBER About ₹27 of revenue per battery per day (₹100 crore over 100,000 packs). |
|---|
| RUPEIA VERDICT Credible infrastructure, strategic backing, no independent price. A watch-list name until non-Yulu volume and EBITDA are shown. |
|---|
Frequently asked questions
How much did Yuma Energy raise?
US$35m in a Series A from Magna International, announced 31 August to 1 September 2026.
What is Yuma Energy?
A battery-swapping network for electric two- and three-wheelers, built from Yulu's swap business with Magna.
How big is the network?
2,500+ charging units at 400+ locations in about 18 cities, with about 100,000 batteries.
What is Yuma's revenue?
About ₹100 crore for FY26 according to management.
Is Yuma profitable?
Not overall. Some older stations are EBITDA-positive and the company targets overall EBITDA-positive in FY27.
Can I buy Yuma shares?
There is no open round; only strategic or fund routes.
Source log
Autocar Pro: Yuma Energy raises US$35m from Magna
YourStory: Yuma Energy raises US$35m in Series A
Inc42: Yuma Energy bags US$35m
Evertiq: Yuma raises US$35m
Dealroom: Yuma Energy
Autocar Pro: Yuma in Noida and Uttar Pradesh
| DISCLAIMER This report is independent research by Rupeia Investments Co. built only from public sources as of the date shown. It is not an offer, solicitation or investment advice, and it is not a recommendation to buy or sell any security. Private-company figures are drawn from filings and media reports and may be revised. Unlisted and private-market investments are illiquid and carry a risk of total loss. Investors should take independent advice. |
|---|